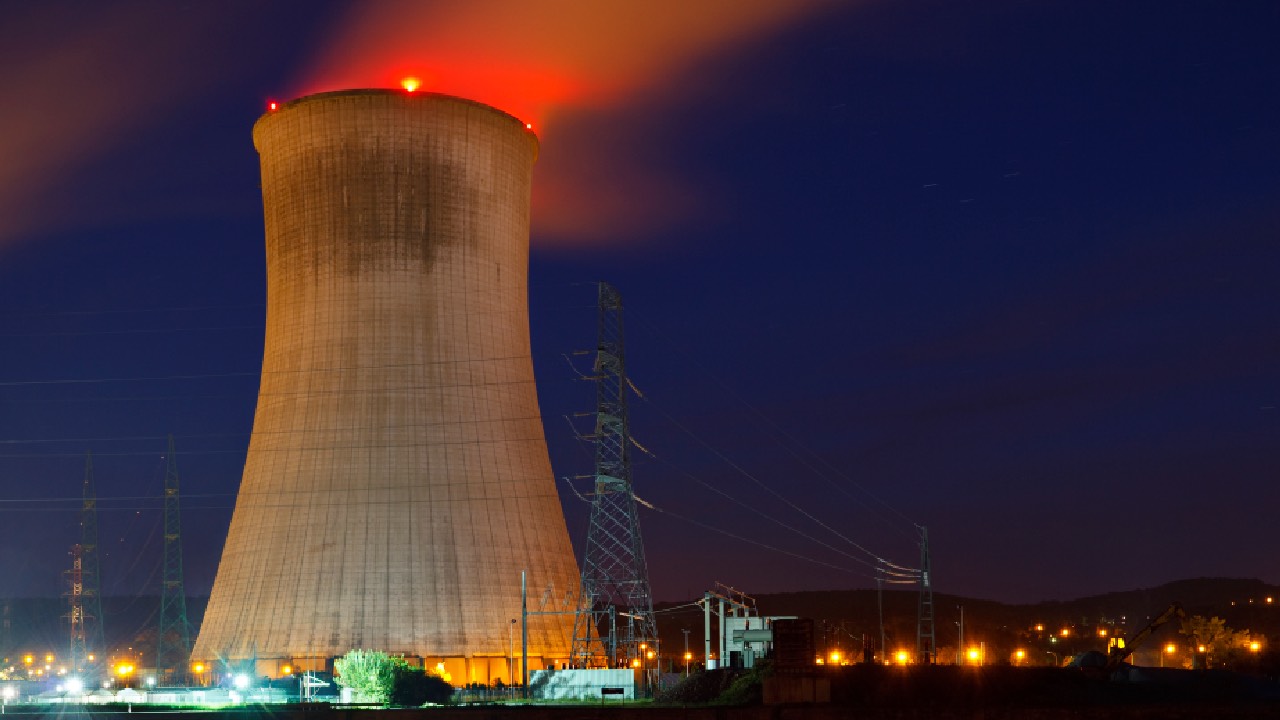

When one of America’s largest LNG export hubs formally endorses nuclear-powered shipping, it is not a press release — it is a policy signal that reprices an entire asset class. The Port of Corpus Christi’s alignment with nuclear maritime propulsion marks the moment a fringe technology debate became a mainstream infrastructure question, and for investors positioned correctly, the timing could not be more consequential.
A Port Changes Everything
Port infrastructure speaks in the language of capital commitments, not conference panels. When a premier U.S. LNG export gateway — one handling millions of barrels of crude and billions of cubic feet of gas annually — publicly backs nuclear-powered shipping, the signal travels far beyond maritime circles. It reaches shipyard financing desks, classification society underwriters, and IMO regulatory working groups simultaneously.
The question for investment professionals is not whether this technology transition will occur. The question is how fast, who captures the value, and which current equity positions are implicitly short the change.
Three Forces Converging Right Now
The Decarbonization Mandate. IMO carbon intensity requirements are tightening each year. LNG-fueled vessels — once marketed as the clean-transition solution — are being re-evaluated as the scientific consensus hardens around methane slip: unburned gas leaking from LNG engines that erodes the emissions advantage. Small Modular Reactors produce zero operational carbon. For a shipowner weighing a 25-year newbuild investment today, the regulatory calculus has fundamentally shifted.
The LNG Freight Collapse. The LNG carrier market is simultaneously creating the economic conditions that make nuclear propulsion attractive. FLEX LNG (FLNG) reported Q2 2026 spot rates of approximately $30,000/round trip — down from $120,000 in Q3 2025, a 75% decline in twelve months. Approximately 285 vessels are on order globally, representing 38% of the existing fleet, with deliveries peaking at 95–98 ships across 2026–2027. In a margin-compressed market, eliminating fuel costs via nuclear propulsion shifts from an aspiration to a competitive necessity.
Geopolitical Fuel Vulnerability. Capital Economics confirmed in August 2026 that Qatar’s LNG production capacity is 17% offline for two to three years following Iranian strikes, while Strait of Hormuz disruption has severed conventional bunkering routes. A nuclear-propelled vessel that never needs to stop at a vulnerable fuel hub is — in the bluntest possible terms — a geopolitically resilient asset. That attribute carries a real premium in today’s freight markets.
The lowest-risk entry sits with GEV. Its BWRX-300 is not a whitepaper — it is under active construction at Ontario Power Generation’s Darlington site in Canada, the most advanced SMR build in North America. A definitive agreement with Blue Energy targets a 2.5-gigawatt combined gas-and-nuclear facility in Victoria, Texas, with a final investment decision expected in 2027 and nuclear output beginning 2032. Gas turbine cash flows today are funding the nuclear build of tomorrow. The stock’s current price at $966.01 reflects a diversified industrial franchise — the nuclear optionality may not yet be fully priced.
The highest optionality belongs to SMR, which is also the highest risk. B.Riley maintains a Buy with a $15 price target (reduced from $19), citing not technology failure but a sector-wide valuation reset and increased share count. At $9.07 — down roughly 73% from its 52-week high — and holding $1.9B in cash with zero debt, the market appears to be pricing maximum uncertainty at precisely the moment the policy environment is improving. That is either a value trap or a generational entry. The distinction depends almost entirely on regulatory timeline assumptions.
The picks-and-shovels angle is STDN, up +8.35% on Aug 20 following its binding TRISO fuel supply agreement with Radiant Industries through 2031. The company describes itself as the only U.S. firm with industrial-scale TRISO fabrication capacity for advanced reactors. Nuclear-propelled commercial vessels need enriched fuel — whoever controls that supply chain controls the operating economics of the entire fleet. This is the maritime nuclear equivalent of owning the refinery, not just the shipping routes.
IMSR scored a critical milestone in May 2026 when the NRC issued a Safety Evaluation Report approving its IMSR Postulated Initiating Events Topical Report — a licensing gateway many considered years away. Its 7.8GW pipeline, anchored by a 4GW MOU with Riot Platforms for hyperscale data center power, establishes proof-of-concept commercial demand that maritime applications can follow. At $5.27, the stock dropped 7.38% on Aug 20 — potentially an overreaction worth examining given the licensing progress.
The LNG Fleet: Accidental Stranded Asset?
The maritime nuclear thesis creates a structural bifurcation in LNG shipping equities that the market has not yet fully priced.
Golar LNG (GLNG) just committed $2.45B to its fourth Floating LNG production vessel — a unit with 3.5 million tonnes per annum capacity, not expected until year-end 2029. The bull case: Golar’s FLNGs are production assets, not propulsion vessels. They liquefy gas offshore. Nuclear propulsion mandates target carriers, not floating production units. Golar’s backlog remains insulated near-term.
The bear case: If nuclear-propelled LNG carriers gain port access advantages — and Corpus Christi’s signal suggests this is a live regulatory possibility — every conventional carrier built today carries a latent stranded-asset risk embedded in its 25–30 year asset life.
FLEX LNG (FLNG), trading at $32.06 with a 20th consecutive quarterly dividend of $0.75 (yielding approximately 9.7%), offers a near-term income story. Its 51-year minimum firm contract backlog and 89% of 2026 available vessel days already covered suggest insulation from spot market carnage. But the 38% fleet expansion embedded in the global orderbook is a medium-term yield risk that investors should not overlook.
The Policy Tailwind: Washington Is Rowing in the Same Direction
President Trump’s National Security Presidential Memorandum on shipbuilding — directing the establishment of a fifth Naval shipyard, the first in over 80 years — creates a parallel infrastructure track for domestic nuclear maritime manufacturing. The U.S. Navy’s eight decades of nuclear propulsion operational experience represent an unmatched knowledge base. The transfer of that expertise to commercial maritime applications is, at its core, a policy decision — not an engineering one.
Meanwhile, China’s 15th Five-Year Plan targets 200 million tonnes per year of LNG receiving capacity by 2030. That build-out requires hundreds of additional carrier transits annually. If nuclear-propelled vessels gain preferential access at Chinese LNG terminals — a real possibility given Beijing’s own advanced nuclear ambitions — the entire carrier ordering cycle could reprice within a single regulatory window.
Three Investment Buckets
Enablers — SMR technology developers. Binary outcomes, long timelines, asymmetric upside. GEV offers the lowest-risk entry: diversified cash flows underwriting nuclear development. Pure-play names carry pre-revenue risk priced at, or near, maximum pessimism.
Adapters — LNG shipping equities. Near-term yield opportunities with long-dated technology risk embedded in fleet valuations. The trigger to watch: any IMO language establishing preference for nuclear-propelled vessels. That single regulatory event restructures asset values across the sector.
Infrastructure — Fuel supply chain and port enablers. STDN and TRISO manufacturers represent the “picks-and-shovels” layer — the one part of the nuclear maritime stack that is needed regardless of which reactor design wins.
The Bottom Line
Port endorsements are how infrastructure revolutions begin — not in laboratories, but when the terminals, the regulators, and the capital allocators align. That alignment is forming now, faster than consensus expects. The investors who wait for certainty will be paying full price. The investors reading the port signals correctly may not be.
At current valuations — SMR at $9.07 against $1.9B in cash, IMSR at $5.27 post a landmark NRC milestone — the market is pricing maximum regulatory pessimism at the exact moment the policy environment is accelerating. That is a tension worth examining closely.
Source: Investing.com


Related News.

Can Iran replace sea trade with land routes?
Can land corridors offset the impact of the maritime blockade on Iran? The US-led maritime blockade targeting Iranian ports has severely disrupted…
YoungShip puts focus on attracting and developing shipping’s next generation
Shipping needs to attract a new generation of talent, help young professionals navigate an industry being reshaped by technology, regulation and…
Russia shifts to Hong Kong tankers as Greek operators exit Black Sea
Russia turned to non-G7 tankers for seaborne crude sales to foreign buyers in August, especially those operated by Hong Kong companies, as Greek…

Capesize Market Review Brazil’s Ore corridors, the El Niño Rainfall Divide, and contracting against the C3
C3 route performance into the third-quarter close With the third quarter nearing its close, the focus remains on C3 route performance, the spotlight…
NeptuneZero named among the Thetius Top 150 for 2026
Greek marine data collection company recognised for its automated sensor data collection and validation platform, now deployed on more than 150…

xclusiv S&P Report 14th September 2026
Pls find below the [xclusiv] S&P Report 14th September 2026 [xclusiv] 2026_09_14

DHT Holdings, secures three-year time charter for DHT panther
DHT Holdings, announced it has entered into a three-year time charter agreement at $100,000 per day for the VLCC DHT Panther, built in 2016. The…
Leghorn TCO Terminal Calata Orlando comes under the control of Neri Group and Nova Marine Carriers
The Leghorn-based TCO (Terminal Calata Orlando) has come under the direct control of the Fratelli Neri and Nova Marine Carriers groups. A majority…
The Swedish Club warns Cape Horn should remain ‘Plan C’ for Panama diversions
The Swedish Club has warned that southern passages around South America should remain a third-choice option for shipowners trading between the US…
Hapag-Lloyd strengthens partnership with DP World to support growth in Africa
Hapag-Lloyd to secure long-term terminal capacity across 5 key terminals Committing to new and expanded port infrastructure to accommodate future…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
