North Sea still to come under pressure; Aramco OSP cuts target China

December 17, 2024
Commentary summary:
– WTI (Afras) and Black Sea crudes look less competitive against Forties, but Forties itself still undercut by Med and even WAF.
– EFS tradind down to $1/bbl, but many light European crudes look uncompetitive to Asia nonetheless. More reason to see the European market cool.
– TI/Brent to narrow to cool marginal flows to NWE following weeks of cheap landed WTI Afras into NWE.
– OSP cuts put Arab Light into a competitive position in Far East, ahead of the February cycle where there is anticipation of strong Chinese buying.
Flat price cared very little for OPEC+ decision-making. The market required something stronger to tighten up the notional long 2025 liquids balance (assumed without more OPEC+ barrels).
Futures timespreads continue in their holding pattern, refusing to go into contango and disconnecting a little from flat price over the last week or so.
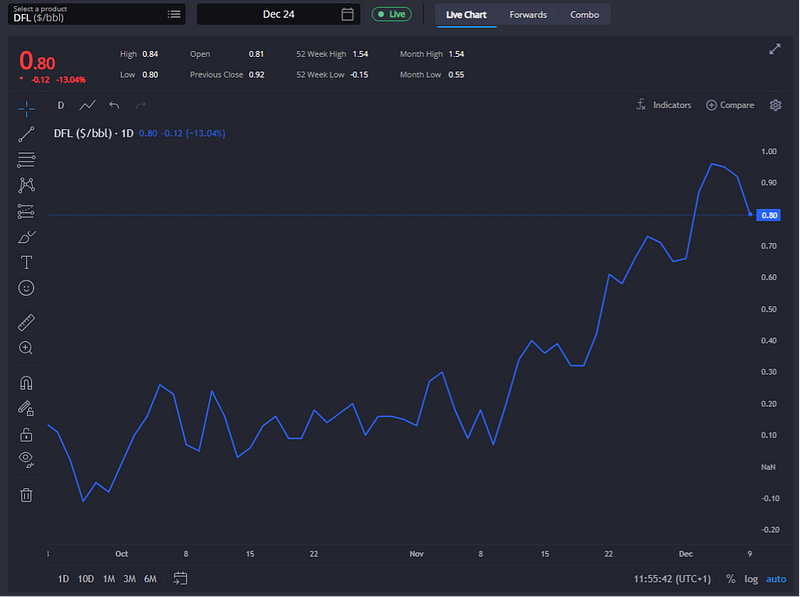
A further disconnect remains the North Sea which for some time has looked too strong against the physical arb in/out picture. DFLs and prompt CFDs are now cooling slightly.


Image
(DFLs looked to have peaked)
Europe
With that said, if you had not been following the context of the last week or two (including very high physical activity in the North Sea), you’d be forgiven for thinking that North Sea strength is now starting to look more in line with the rest of physical/arb picture in Europe.
One factor is that Black Sea premia have been bid up substantially recently, partly in sympathy with North Sea, but also unplanned and extended Tengiz maintenance.
Freight rates out of the Med are also on the rise to NWE, where Med/Black Sea cargoes (e.g. Azeri, Saharan) have seen open arbs for some weeks already (for Azeri this now looks less open as a result of freight, FOBs).


Image
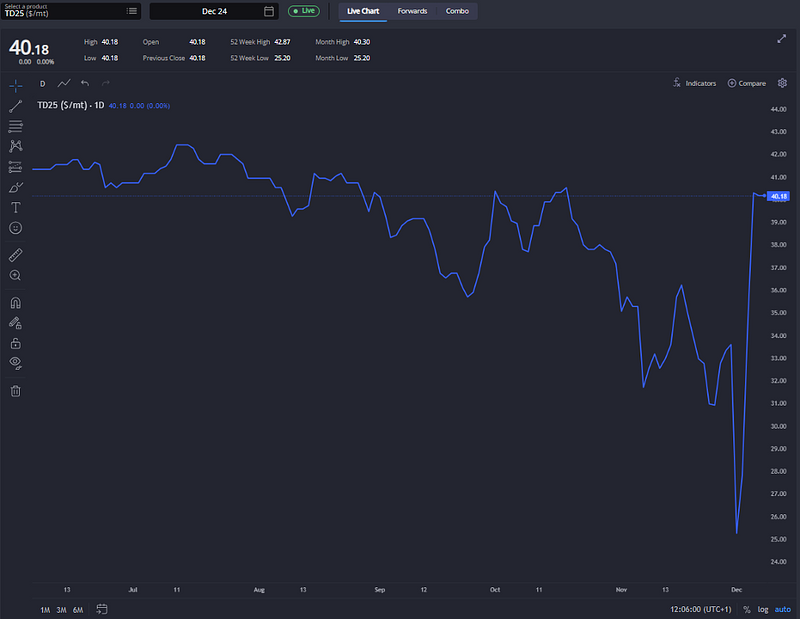
(TD25 has seen a major upward correction)
The other major factor is WTI into Europe. WTI Afras looked fairly cheap for some weeks and one can assume a result has been higher flows.
TD25 has (presumably as a result) now seen a very substantial repricing higher, with our Dec physical rate up some $2/bbl over the space of a couple of days.


Image
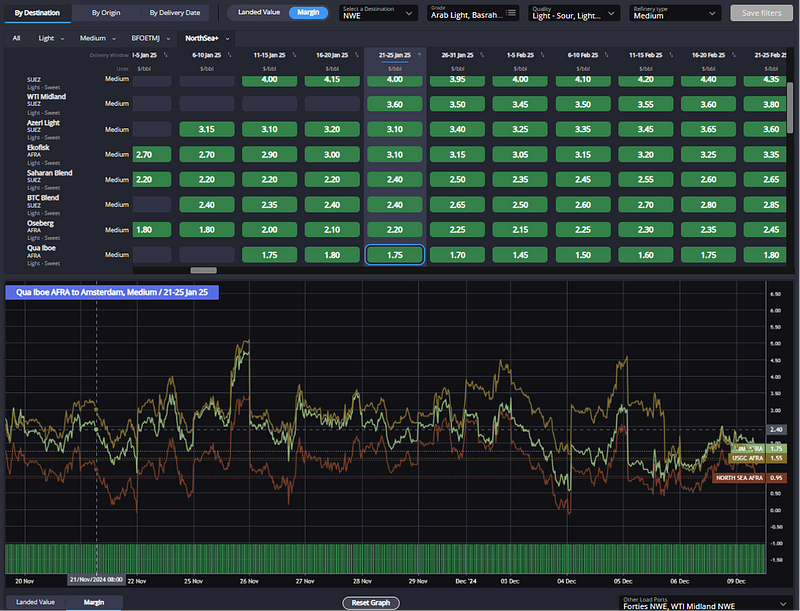
(Qua Iboe cracking is currently higher than WTI Afras and Forties in NWE)
The combination now means both e.g. Azeri and WTI Afra are looking more in line with normal levels against Forties in NWE.
However, the caveat is that Forties itself still looks expensive against a NWE basket, with the likes of Saharan Blend and even Qua Iboe looking cheaper than normal. January Qua Iboe cracking margins are actually above WTI (Afra), Brent, and Forties in NWE.
What is more, WTI is still able to land cheaply on larger vessels. We take the view therefore, that North Sea is still heading for a correction ahead on ample supplies and with limited arb opportunities out the region (particularly to Asia, despite a weak EFS).
We can also see a situation where TI/Brent now narrows despite TD25 with North Sea/NWE weakening and thereby calling for fewer incremental barrels out the US.
On the US side PADD-3 commercial stocks are drawing quite heavily and MEH may be unwilling to weaken for the purpose of arbing Afras into Europe.
One last note is on margins: most product cracks are on the decline, and a result of that and higher landed values, WTI Afra cracking margins are trending at around a 1-month low.
Forties cracking is at the lower end of the last two months and only roughly $1/b above water. That also seems to suggest that BFOETM needs to cool a little.
Asia
The market is waiting for the start of the February trading cycle with some anticipation for Chinese independents in particular coming out swinging in the legitimate crude market. Time will tell; the risk to spot MEG and WAF seems to be to the upside but with crude supply at the moment ample, there is likely a low ceiling.


Image
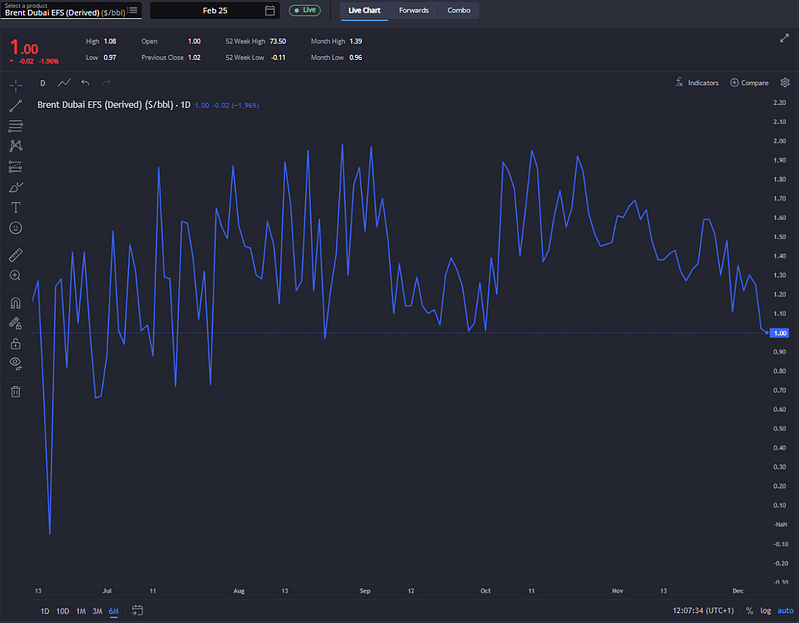
(The EFS is at multi-month lows)
The EFS has traded down to some $1/b this morning, from nearly $2/b in late October.
Despite this, few light crudes look competitive into SE Asia or Far East at the present from Europe.
One read is that this is related to relative FOB strength in Europe and the need to start to price these crudes more competitively into East (another reason to suspect North Sea strength is overdone).
Asian demand also seems lacklustre for the usual western crude diets. Argus has reported Saharan has not arbed to Asia over the last few weeks, a relatively rare occurrence.
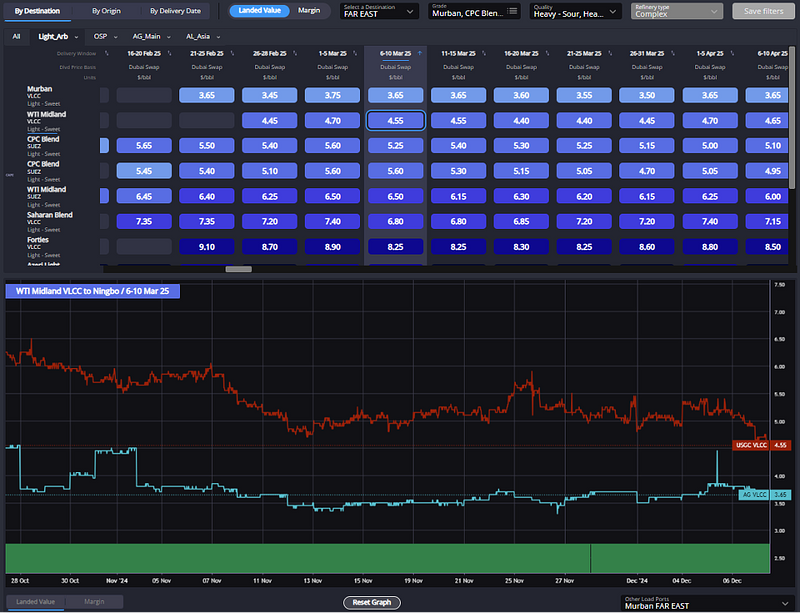
One notable trend has been WTI vs Murban with the former catching up on the latter in terms of landed values over the last day or two, mostly on freight, for early March landing.


Image
(WTI is catching up on Murban in the Far East)
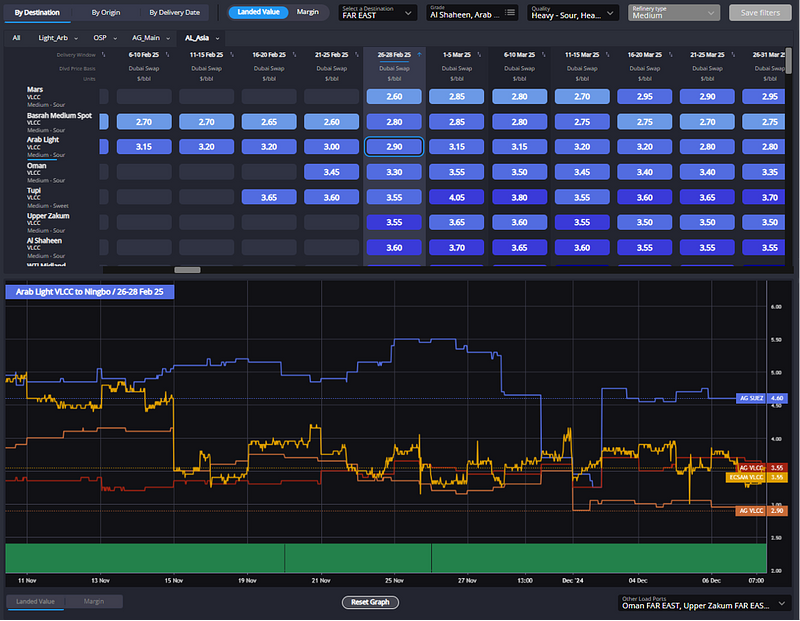
On medium crude, Aramco came out with largely anticipated but still sizeable cuts to Asia (Europe was also chopped substantially).
This reflects the recent weak status of the heavier segment of the crude market.


Image
(Arab Light looks more competitive with OSP cuts)
It puts February-landing Arab Light in a fairly competitive (landed value) position against e.g. spot Oman, UZ, and also Americas crude such as Tupi.
That will give pause for thought also in the context of Chinese decision-making heading into the next cycle, with the call on spot (relative to term) crude potentially less than anticipated.
Source: Sparta Commodities

Related News.

Subscribe to our newsletter!

if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!

* indicates required
Consent *
By submitting this form you agree to receive Email Marketing

Design & Development by P.KAN.DESIGNER

Design & Development by P.KAN.DESIGNER

Privacy Preference Center