
Record-high diesel prices and tight inventories have put US exports under scrutiny, but keeping more barrels at home may offer only temporary relief. With refiners already running near capacity and strong global margins pulling US diesel overseas, export restrictions could support domestic inventories while weakening refinery economics. From a full ban to quotas and regulatory flexibility, each policy option comes with trade-offs for US supply and prices.
US refiners are already running hard. Utilisation has remained above 95% for much of the summer, reaching around 98% in the final week of August, with August 2026 crude runs near 17.3 Mbd. Strong refining margins and export demand continue to incentivise refiners to maximise throughput, as constrained Russian and Middle Eastern product supply increases global reliance on US barrels.
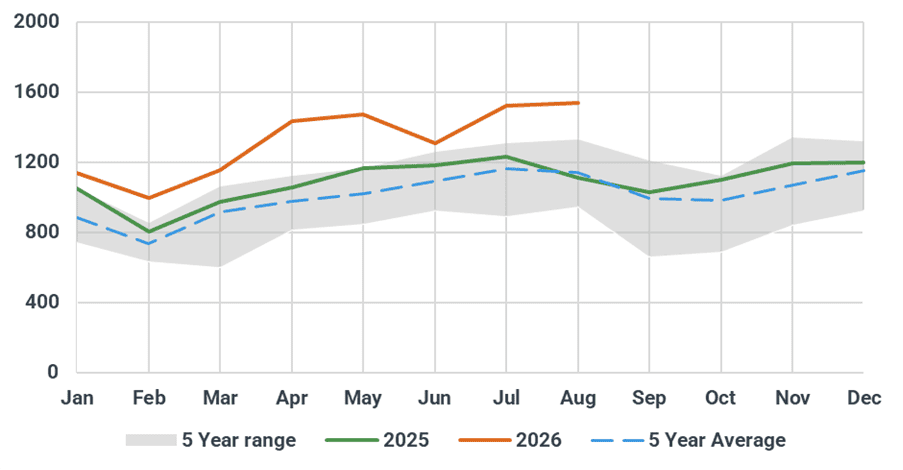
US diesel exports
Source: Kpler
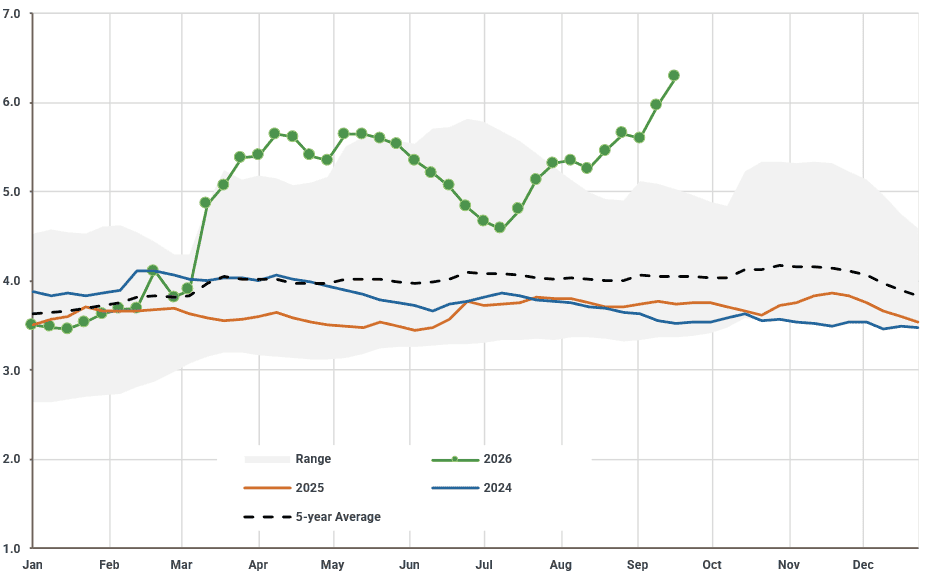
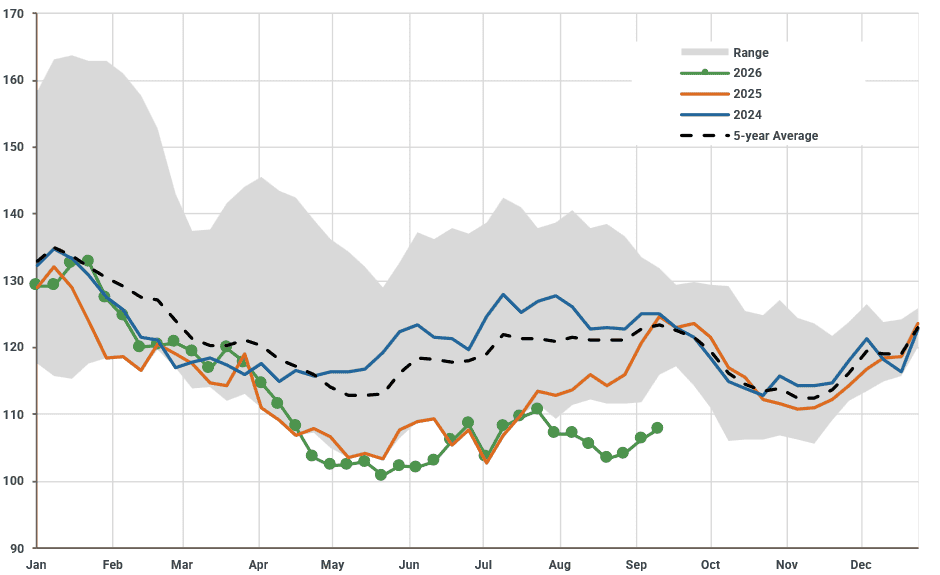
Despite exceptionally strong refinery runs, high export demand has limited the extent to which additional US production has translated into higher domestic availability. Distillate inventories have struggled to rebuild, falling to around 108 million barrels, 13% below the five-year average, while tight diesel balances have continued to push prices higher (EIA). Meanwhile, weekly average retail diesel prices rose by $0.37/gal w/w and $0.71/gal m/m to $5.97/gal, the highest level in EIA’s series.
US weekly ULSD retail prices
Source: EIA
US weekly diesel inventories versus five-year range
Source: EIA
Record-high diesel prices have increased the pressure on the US administration to find ways to ease the burden on domestic consumers. While the administration has so far emphasised increasing domestic supply, the strength of US exports has also brought potential export ban into the discussion. Below, we explore the main options the US could consider and their potential implications for the US market.
What options does US have?
Option 1: no restrictions — maximise domestic supply
Leaving exports unrestricted and focusing on increasing supply remains closest to the administration’s current position. However, with refinery utilisation already multi-year high at around 95–98%, there is effectively no further headroom to increase crude runs.
Option 2: regulatory flexibility
Refiners could optimise middle-distillate yields, while temporary regulatory flexibility could provide some additional room to expand the diesel pool. This could include specification waivers, greater flexibility to blend suitable kerosene-range material into diesel, or changes around RFS/RVO compliance.
However, in the absence of a meaningful recovery in Russian or Middle Eastern supplies, US diesel prices would remain heavily influenced by global market conditions.
Option 3: a temporary full export ban
A full export ban would represent the most aggressive intervention. With the US currently exporting around ~1.540 Mbd of diesel, keeping these barrels at home would initially increase Gulf Coast inventories, putting downward pressure on USGC diesel prices and cracks.
However, the second-order effects could offset some of the initial benefit. Significantly weaker Gulf Coast margins could reduce refiners’ incentive to maintain exceptionally high throughput, potentially resulting in lower refinery runs and diesel production.
Moreover, surplus Gulf Coast barrels cannot necessarily be easily redistributed across the US due to logistical constraints — such as limited pipeline connectivity out of the Gulf Coast and shortage of Jones Act-compliant tankers for coastwise shipping and regional market constraints. A ban could therefore result in a sharp initial decline in USGC prices without delivering an equivalent reduction in retail prices nationwide.
Option 4: export quotas or licensing
A less disruptive option would be to cap rather than eliminate exports. Limiting export volumes could leave additional barrels in the domestic market while allowing US refiners to maintain access to export market.
This is broadly similar to China’s approach, which allocates refined product export quotas to individual refiners. A comparable company-level quota tied to historical export levels could give the US more precise control over the scale of restriction. This could support inventory rebuilding while limiting the downside to PADD 3 refining margins and reducing the risk of refiners responding by cutting throughput. The impact on domestic prices would ultimately depend on the scale of the restriction and how effectively additional USGC barrels could be redistributed within the US.
Option 5: export duty
An India-style export duty could theoretically discourage exports while preserving greater market flexibility than a ban. Implementing such a measure in the US, however, would face significant legal constraints.
Article I, Section 9 of the US Constitution prohibits taxes or duties on exports from US states, making a straightforward per-barrel diesel export levy difficult to implement.
Overall, restricting exports could provide some near-term support to domestic inventories and pressure Gulf Coast diesel prices lower, but it would not address the underlying global supply shortage. With US refiners already operating near capacity, measures that redirect existing barrels may offer temporary relief, but the scope to materially increase domestic diesel supply remains limited.
Source: Kpler.


Related News.
Register Now for the CSN London Maritime Forum “Shipping: Predicting an Unpredictable Future”, 13 October – Two Weeks Left
“Shipping: Predicting an Unpredictable Future” REGISTER HERE Date: 13 September 2026 Time: 09:00-16:00 Venue: Marriott Hotel Regent's Park Following…
Working visit of the Shipping Deputy Minister of Cyprus to Brussels
The Shipping Deputy Minister to the President, Ms. Marina Hadjimanolis, departed on Monday, 28 September 2026, for Brussels, following an official…
Navigating the S-100 Transition: Real-World Trials and the Future of Digital Navigation
As the maritime industry prepares for the implementation of the S-100 data standard, the shift from traditional Electronic Navigational Charts (S-57)…
Electronic evidence is transforming maritime casualty investigations, says The Nautical Institute
New edition of Guidelines for Collecting Maritime Evidence Volume 2 addresses electronic records, AI, digital reconstruction and the changing…
Xeneta freight rates set to climb in early October
“For the high-flying spot rates from Far East to US East and West Coasts, we may just begin to see the end of that rising trend as we get into the…
A new gateway to Turkey – Stolthaven Terminals and Rönesans Holding on the DAPEK Ceyhan Terminal
Stolthaven Terminals and Rönesans Holding are building a new chemical and industrial terminal at Ceyhan, on Turkey’s Mediterranean coast. The…
KME & KMSM Family Day 2026 held in Singapore
Promoting Business Understanding and Employee Engagement Through Interaction Between Employees and Their Families K LINE MARINE & ENERGY a…
Maritime Coastguard Agency celebrates World Maritime Day 2026
Transport Secretary Heidi Alexander has written to the International Maritime Organization on World Maritime Day. On Thursday 24 September,…
Paracel Carbon Forestry Project verifies first carbon removal credits
Paracel, a large-scale carbon removals project in Paraguay backed by Trafigura, has verified its first carbon removal credits, totalling over 190,000…
When the Levee Breaks
The weakest June for Chinese crude imports in a decade did not cost a single barrel of throughput. Imports fell 41.3% on the year, runs held above…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
