[xclusiv] S&P Report 10th August 2026


Please find below the [xclusiv] latest Weekly S&P Report, along with following opening market commentary
Market Commentary:
The dry bulk freight market delivered a considerably stronger performance during the first seven months of 2026, with Baltic Exchange time-charter equivalent earnings improving across all four major vessel segments compared with January–July 2025. The recovery was broad-based rather than dependent on a single vessel class, reflecting stronger cargo volumes, improved fleet utilisation and firmer demand across both major and minor bulk trades. Based on the available daily assessments, the Capesize 5TC averaged approximately USD 30,400/day, up 81% from USD 16,800/day during the corresponding period of 2025. Capesize earnings reached a high of USD 46,538/day in late May, while the market closed July at USD 35,457/day, well above the USD 26,858/day recorded at the end of July last year. The improvement extended across the smaller segments. Kamsarmax earnings averaged around USD 17,600/day, increasing 53% year-on-year from USD 11,500/day, while the Ultramax 11TC rose by 48% also near to USD 17,600/day. Handysize earnings recorded the smallest, but still substantial, increase, averaging USD 14,100/day compared with USD 10,100/day in 2025, representing growth of 39%. The progression of rates was also important. Following a relatively stable opening quarter, earnings strengthened sharply during April and May, particularly for Capesizes and Kamsarmaxes. Ultramax and Handysize markets advanced more steadily, reaching their strongest levels during June and July and demonstrating healthier underlying support across geographically diversified trades. This stronger freight environment was accompanied by an increase in total seaborne dry bulk volumes. Based on the Signal Ocean data, approximately 3.41 billion tonnes were transported during January–July 2026, compared with 3.35 billion tonnes during the same period of 2025, representing growth of almost 2%. Capesize-carried cargo increased by 4.8% to 936.7 million tonnes, lifting its share of total trade from 26.7% to 27.4%. Panamax, Supramax and Handymax volumes also increased, while VLOC, Handysize and Small vessel cargoes declined. The figures therefore indicate that trade growth was concentrated mainly in the larger and medium-sized vessel categories, supporting the segments that experienced the strongest freight improvement. Commodity flows remained dominated by iron ore and coal, which together represented more than 52% of total dry bulk trade. Iron ore volumes increased by 1.5% to 992.2 million tonnes, while coal shipments rose by 2.1% to 788.9 million tonnes. Grain trade delivered a more pronounced increase of 10.4%, reaching 358.9 million tonnes and overtaking other ores and rocks as the third-largest cargo category. By contrast, fertilizers, steel, cement and forestry products declined, confirming that overall growth was driven primarily by the traditional core commodities. Australia remained the largest origin, increasing exports to 844.8 million tonnes, followed by Brazil at 374.1 million tonnes. Guinea recorded one of the strongest increases, rising 22% to 131.9 million tonnes, supporting long-haul bauxite movements. China remained overwhelmingly the largest destination, receiving 1.36 billion tonnes, up 2.9% year-on-year and representing almost 40% of global dry bulk imports. South Korea, Vietnam and Indonesia also increased intake, while India declined by almost 5%. Overall, the 2026 freight recovery appears firmly connected to improving physical trade. Higher iron ore, coal and grain volumes, combined with stronger long-haul exports from Australia, Brazil and Guinea, increased vessel employment and supported rates across the market. The particularly strong Capesize performance reflects both higher cargo volumes and the tonne-mile intensity of major ore trades, while the gains in smaller vessels confirm that the recovery has developed into a genuinely broad-based dry bulk market.
S&P Activity:
Dry:
On the Capesize sector, Seanergy acquired the “Asanagi” – 182K/2022 Tadotsu for USD 50 mills basis delivery Q4 2028 – Q2 2029. On the same sector, the “Aanya” – 180K/2012 HHIC was sold for USD 36.9 mills, while European buyers acquired the “Orange Tiger” – 181K/2011 Imabari for USD 36.5 mills. Moving down the sizes, the Kamsarmax “Aquavita Aim” – 82K/2019 Oshima changed hands for USD 38.2 mills to European buyers. On the same sector, the Scrubber fitted “Medi Positano” – 82K/2015 Tsuneishi and the “Royal Hope” – 81K/2015 JMU were sold for USD 31.6 mills and USD 31.2 mills, respectively, while the Scrubber fitted “Velos Jasper” – 82K/2012 Tsuneishi found new owners for USD 23.5 mills. On the Ultramax sector, the “Union Lotus” – 64K/2015 China Shipping Ind. was sold for USD 26 mills. Finally, the “Glory Bridge” – 50K/2001 Mitsui changed hands for USD 7.4 mills, while the Handysize “V Due” – 38K/2015 Avic Weihai was sold for USD 18.8 mills basis TC attached till the end of 2026 at USD 12K/day.
Tanker:
The tanker S&P market remained quiet this week, with no sales to report.


Related News.
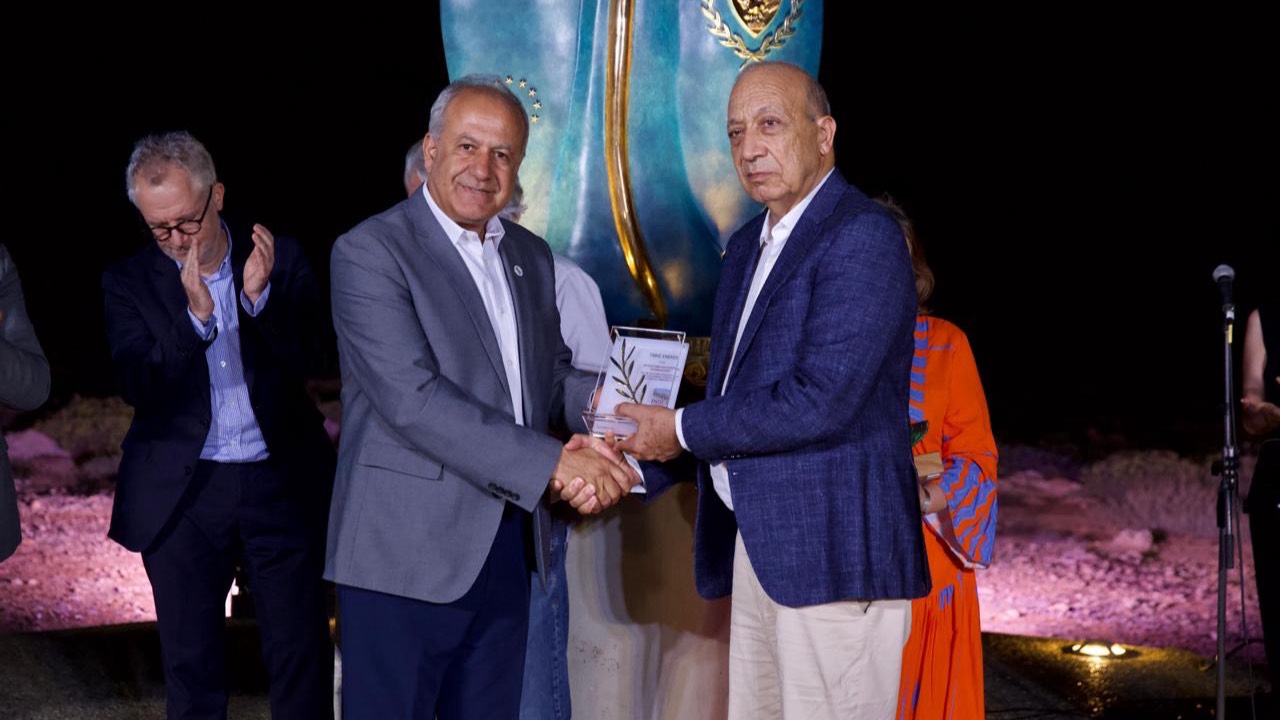
ISLAND OIL: Unveiling of the Sculpture “Cyprus’s Journey Through the Ages” in Protaras – A Tribute and Landmark to Cyprus’s Historical Memory and Cultural Heritage
In a modest ceremony marked by a moving atmosphere, the sculpture “Cyprus’s Journey Through the Ages”, created by acclaimed Cypriot sculptor…
World Maritime Day 2026 from Policy to Practice – powering Maritime Excellence
Global regulations will deliver safer, more resilient shipping when they are implemented worldwide. The international maritime community marks…

Diana Shipping announces Time Charter Contract for m/v DSI Polaris with Dai An Ocean Shipping
Diana Shipping , a global shipping company specializing in the ownership and bareboat charter-in of dry bulk vessels, announced that, through a…
Chief Economists Expect Global Economy to Stabilize, but Fiscal Constraints, Rising Living Costs and AI Investment Uncertainty Threaten Growth
The global economy is stabilizing, but the fiscal support that cushioned successive shocks since 2020 is unlikely to play the same role in the year…
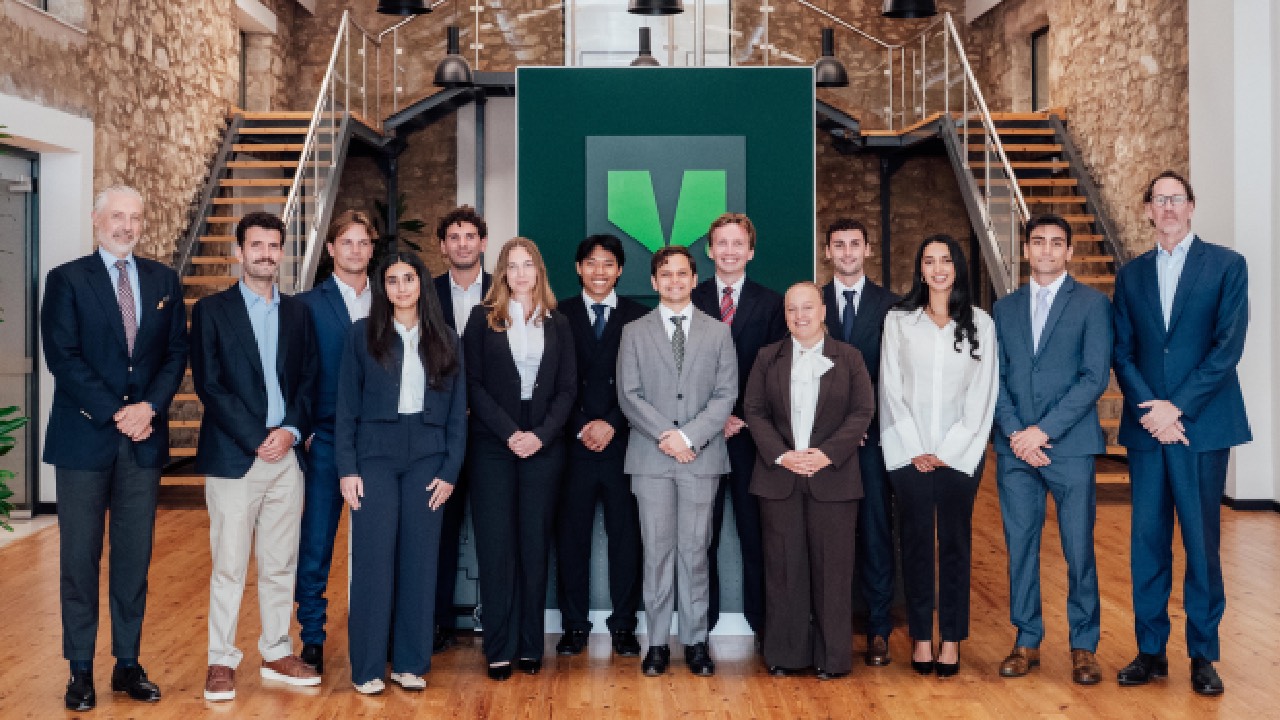
V. welcomes its new graduate cohort as programme expands across the group
Twelve graduates from nine nationalities join 11th year of V.’s expanded international management programme. V., the global ship manager and marine…
From Policy to Practice: Why Seafarers Are the Key to Maritime Excellence
The shipping industry is no stranger to regulation. Seafarers and ship operators work within a vast framework of international conventions, national…

Intermodal Report – Week 38 2026
Please find below the Intermodal market report for week 38 2026. Intermodal Report Week 38 2026 Market Insight By Nikos Tagoulis, Head of…

Allied – Weekly Market Review – Week 38
Please find below the Allied Weekly Report for Week 38 | 2026 ALLIED - Weekly Market Report- Week 38
Record year on the Northeast Passage but Arctic shipping remains very limited
In 2025, a record 103 transit voyages were made via the Northeast Passage. However, this is still equivalent to only around a day and a half of…
[xclusiv] S&P Report 21th September 2026
Please find below the [xclusiv] latest Weekly S&P Report [xclusiv] 2026_09_21 Market Commentary: VLCCs: Freight Boom Reprices the Fleet The VLCC…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
