VLCC 5Y tonnage now trades above Newbuild

Spotlight | Asset Benchmark Assessments — NB vs 5Y & NB vs Resale
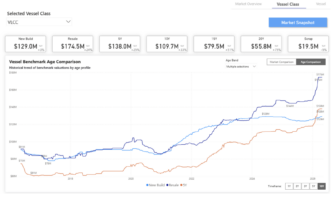
We take a closer look at the evolution of ship price assessment in the crude carrier segment. At the end of February, we highlighted growth in values for the VLCC segment and foresaw an upward trend, despite the threat of geopolitical risk at the time. We also highlighted the age discount tightening and the narrowing of the spread between five- and ten-year-old vessels, with buyers’ interest in mid-aged tonnage. Now, after more than 60 days of Hormuz disruption, we review the evolution again, and it seems that the age depreciation curve has been lost.
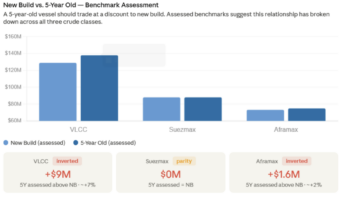
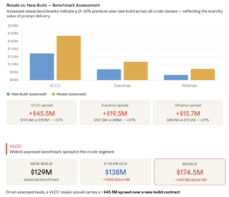
In normal conditions, a resale vessel earns a modest premium for saved wait time, and a 5-year-old ship trades at a clear discount to a new build. Neither is true today. VLCC 5-year-old tonnage trades $9M above a new build contract; Suezmax sits at dead flat; Aframax has also inverted. On the resale side, buyers are paying 21–35% over NB, $45.5M excess on a VLCC alone, purely for prompt availability.
Vessel Crossings | May Observations
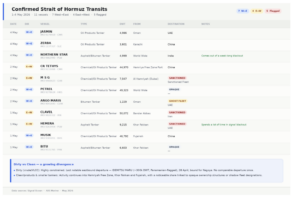
Disruption in the Middle East has continued to dominate oil and tanker market dynamics, with tanker transits through the Strait remaining >95% below pre-conflict levels.
Transits on Iranian Waters
Iran’s new routing regime around Larak Island has increased the degree of political and military oversight applied to commercial transit through the Strait of Hormuz. Iran’s Islamic Revolutionary Guard Corps (IRGC) has instructed commercial vessels seeking transit through the strait to coordinate with Iranian authorities and follow designated routes near Larak Island.
Under the reported routing pattern, inbound vessels heading into the Gulf pass north of Larak Island near the Iranian coastline, while outbound vessels transit south of the island. The arrangement shifts traffic closer to waters claimed by Iran and gives the IRGC greater ability to monitor passing ships.
Iran has also described controlled or restricted monitoring areas between the traffic lanes overseen by the IRGC. This represents a departure from the traditional traffic separation scheme, which relied more heavily on routes associated with Omani waters and internationally managed navigation patterns. While international maritime law still recognises transit rights through the Strait of Hormuz, critics argue that the new system increases Iranian operational control over vessels during passage.
The Mine Threat
Crucially, the operational outlook remains constrained by the mine threat. Although US and allied naval forces are expected to prioritise mine countermeasure operations, some warnings indicate that fully securing the Strait could take months, and that some residual mine risk may persist even after clearance efforts.
This lingering uncertainty is central to the freight outlook, as marine insurers are generally less constrained by volatility than by difficult-to-quantify security risk. Without clear visibility on residual mine threats, predictable operating conditions, and sustained freedom of navigation, war risk cover is likely to remain restricted, selectively available, or prohibitively expensive.
As a result, even if partial transit resumes through routes designated by Iranian authorities, traffic is likely to remain constrained and operationally inefficient, reinforcing vessel displacement toward the Atlantic Basin and sustaining elevated freight rates. The net effect could be a more durable reconfiguration of tanker markets, in which insurance constraints and security uncertainty, not just physical disruption, support Atlantic Basin strength and increase the strategic importance of US Gulf-driven flows.
Oil Macro
Hormuz transit risk is no longer a temporary overhang, and the East-West split deepens in the freight market. The supply shock is historic in scale. IEA has placed the current disruption above 1973, 1979, and 2022 in severity, 12 million bpd of crude supply affected versus 5 million bpd during the OPEC embargo. Brent above $110 and WTI above $100 are the market’s response to that arithmetic. Two producer-side developments complicate the picture. The UAE’s departure from OPEC signals a longer-term pivot toward unconstrained output growth, relevant for post-normalisation supply, less so for today’s constrained flows. Meanwhile, the 188kbd OPEC+ increase agreed by remaining members, including Kuwait, appears to be too small to significantly offset Hormuz-scale disruption and reads more as a political signal than a market intervention. Asian importers are feeling the squeeze most acutely, with Middle Eastern crude arrivals down sharply and US barrels partially, but not fully, filling the gap.
With Atlantic freight markets increasingly driven by supply-side signals, one clear trend has been the growing number of ballast VLCCs in the US Gulf. Average vessel counts have risen toward the 60 mark, contributing to the downward pressure on rates observed at the start of May.
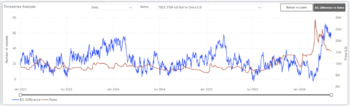
Based on the current supply levels, the TD22 route has shown an increasing trend over the last 15 days, with the daily vessel count now more than 20, compared with a record low of 2 at the start of April.
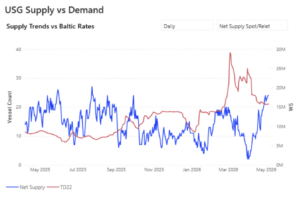
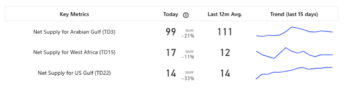
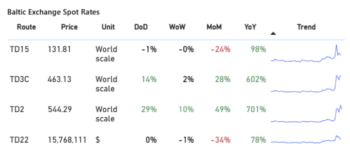
Current monthly freight metrics indicate a 34% decline, though the year-on-year increase remains substantial at 78%. While net supply has been trending upward since mid-April, this has not yet translated into a significant market correction. However, the rapid buildup of ballasting vessels may begin to exert more downward pressure in the near term. A review of the net supply over the past 15 days shows that the West African (TD15) route is experiencing a downward trend; despite this, market sentiment for the current week remains stable with no notable volatility.
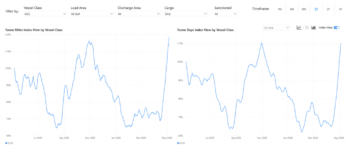
For freight markets, the impact is less about a complete halt in global flows and more about the severe distortion of vessel availability and trade patterns caused by the dual-sided blockade of the Strait of Hormuz. The combination of physical transit restrictions, unresolved mine risk, elevated war risk premiums, and the absence of reliable freedom of navigation has effectively prevented a large share of the mainstream international tanker fleet from operating through the region. This has accelerated the reallocation of vessels from the Gulf toward the Atlantic Basin, reinforcing the role of the US Gulf as a key marginal supplier, particularly into Asia, and driving a substantial increase in tonne-mile demand as longer haul Atlantic routes replace disrupted Middle Eastern exports.
Source: Signal Ocean



Related News.

Navigating the Multi-Orbit Era: In Conversation with Intellian’s Jon Harrison at SMM 2026
At SMM 2026 in Hamburg, the rapid evolution of maritime satellite communications took centre stage. Across the exhibition halls, discussions among…

Cyprus ports need joint energy and investment strategy, shipping agents chief says
Cyprus needs a coordinated strategy for shipping, energy and environmental protection to support port investment and modernisation, Cyprus shipping…

MASO Public Affairs introduces MASO Regulatory Intelligence
A new subscription service helping businesses understand what is changing and what it means for them MASO Public Affairs introduces MASO Regulatory…

Anglo-Eastern helps turn CMBTECH’s ammonia ambition into an operational reality
From early feasibility study and risk-based design to newbuilding supervision, crew readiness and technical management, Anglo-Eastern drew on its…

Escalation of attacks threatens to derail recovery in Middle East oil exports
World oil demand is forecast to fall by 2.5 mb/d y-o-y in 4Q26 and 2.6 mb/d on average in 2026. As the Iran war manifests itself through restricted…

New study finds shipping pays twice its share to EU ETS earmarked revenues should triple to help build market for sustainable fuels and technologies
Shipping is responsible for around 10% of EU ETS emissions but pays almost 20% of the ETS bill. Unlike other sectors, it has never received free…

MSARC strengthens maritime mass rescue readiness through training and national live exercise off Dakar, Senegal
Joint MSARC–FHAS programme combines three days of SAR training with a national multi-agency live exercise The Maritime Search and Rescue Council ,…

Sogese report deliveries are still being delayed as container freight rates fluctuate
FOR IMPORTERS Spot rates into the Mediterranean are back at January levels, Far East to Europe reliability sits at pandemic lows, and nearly…

Glencore begins trading on Australian Securities Exchange
Glencore has begun trading on the Australian Securities Exchange under the ASX code GLC. Gary Nagle, Glencore’s CEO, said it was an exciting day for…

BIMCO Shipping Number of the Week
Suez Canal container ship transits exceed 50% of pre-disruption levels "During the first two weeks of October, weekly container ship capacity…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
