Gulf Congestion rises as Fujairah takes 28% of Waiting Bulkers

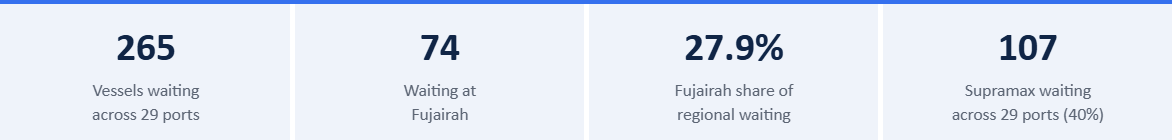
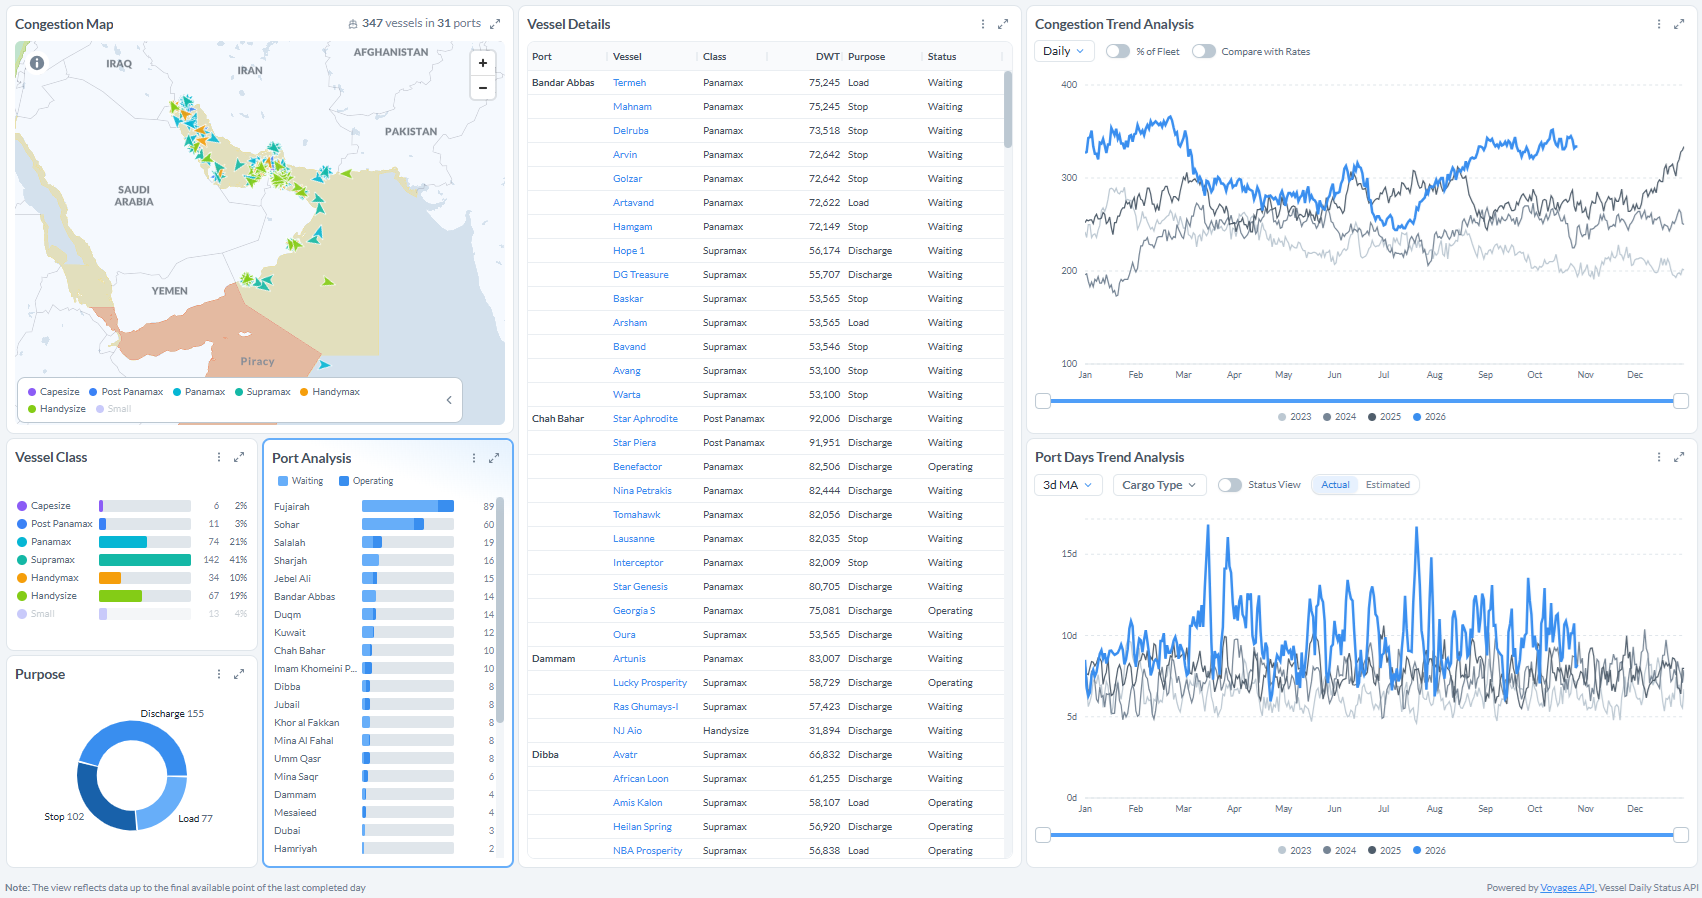
Fujairah records the largest concentration of waiting bulk vessels. More than six months into the Middle East shipping crisis, vessel waiting remains elevated across the Arabian Gulf and Gulf of Oman. As of 28 October, 265 dry bulk vessels were recorded waiting across 29 selected ports, led by Fujairah with 74 vessels (28%) and Sohar with 50. Together, the two ports account for 47% of the regional waiting fleet. Supramax represents the largest segment, with 107 vessels (40%), followed by Panamax (56) and Handysize (53). Prolonged waiting, particularly among Supramax vessels, can reduce prompt tonnage availability, although the freight impact depends on waiting duration and subsequent vessel employment.
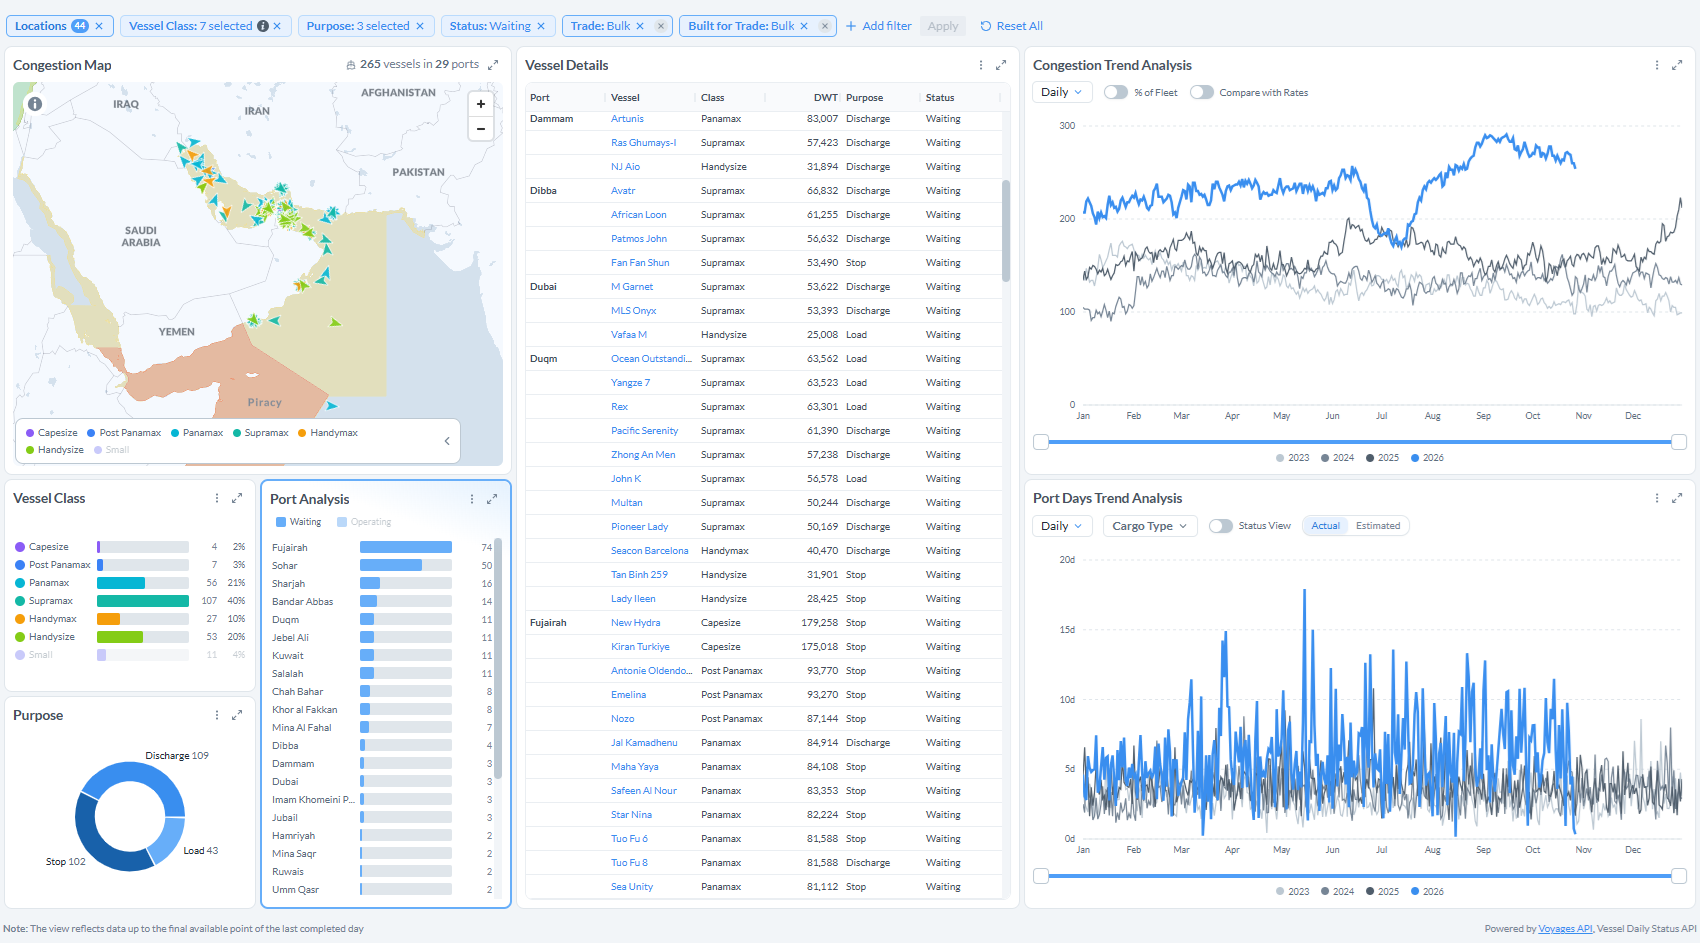
Regional waiting is running 75% above last year. The regional waiting series averaged 268 vessels in 1–27 October, against 154 in the same period of 2025 and 139 in 2024. The count dipped to 170 in mid-July, rebuilt through August to a peak of 291 on 15 September, and stood at 254 on 27 October.
Inside Fujairah: Supramax Accounts for Half of Waiting Dry Bulk Vessels
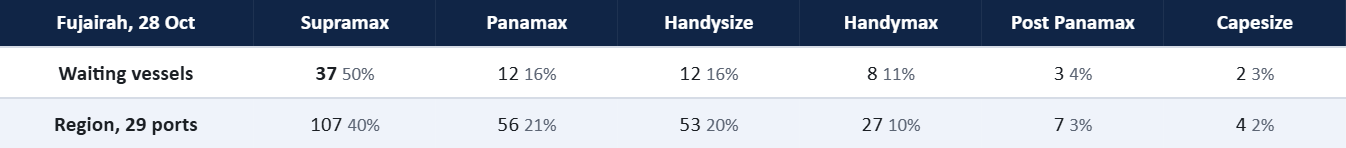
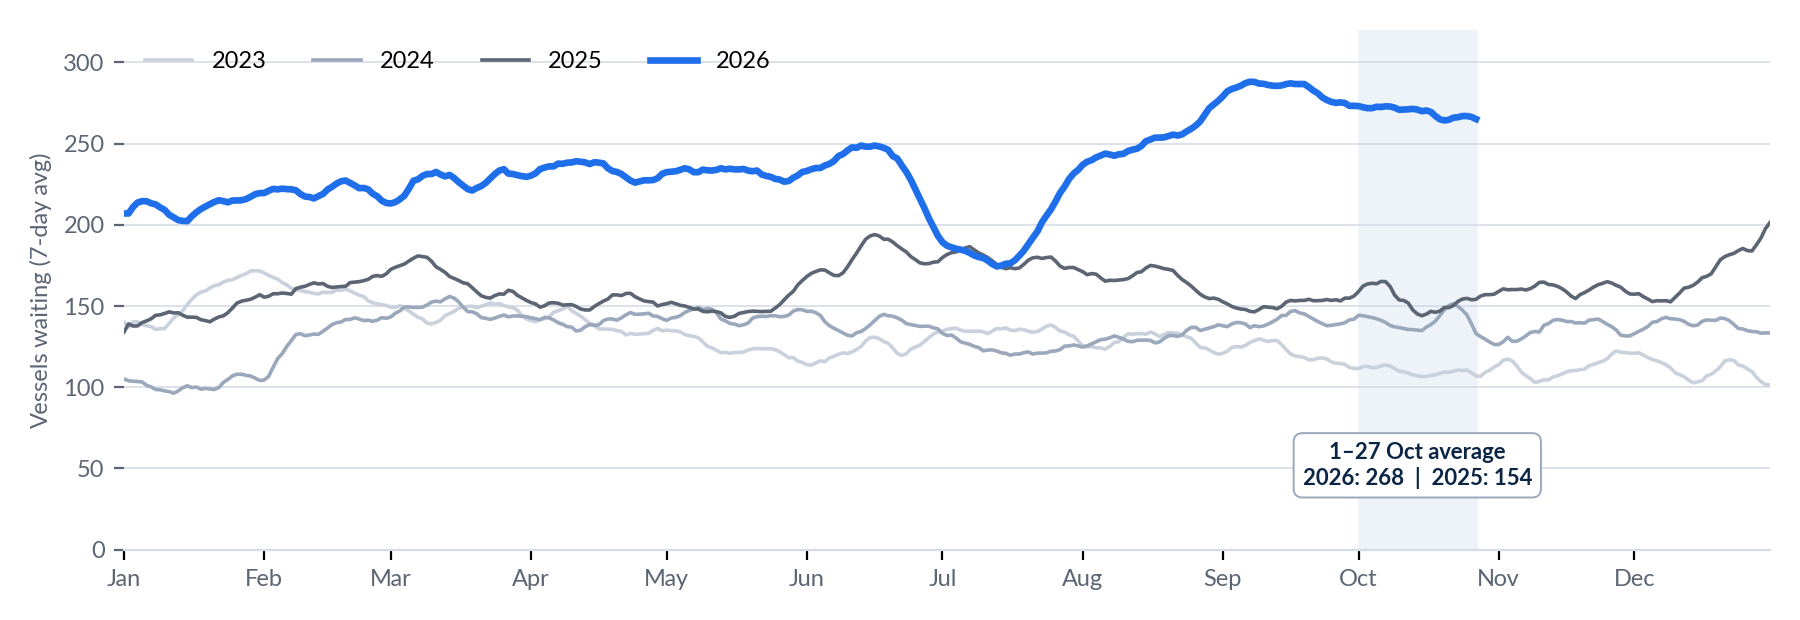
Supramax dominates Fujairah’s waiting fleet. Of the 74 vessels recorded waiting on 28 October, 37 were Supramaxes, representing 50% of the port’s total compared with 40% across the wider 29-port region. Fujairah alone accounts for nearly 35% of all waiting Supramaxes in the regional sample, while Panamax and Handysize follow with 12 vessels each.
Stop calls dominate vessel activity. Of the 74 waiting vessels, 48 (65%) are classified as stop calls, compared with 22 for discharge and just four for loading. This contrasts with the wider regional pattern, where discharge accounts for 109 vessels and stops for 102. Fujairah consequently represents almost half of all regional waiting stop calls, suggesting that its vessel accumulation extends beyond conventional loading and discharge activity.
Congestion has intensified since mid-year. Fujairah’s daily waiting count remained largely below 40 vessels during the first half of 2026 before rising through July and August. The fleet subsequently reached approximately 80–95 vessels during September and October, before easing to 74 by 28 October. Despite the recent moderation, waiting levels remain elevated compared with the first half of the year.
SPOTLIGHT OF THE WEEK | FUJAIRAH
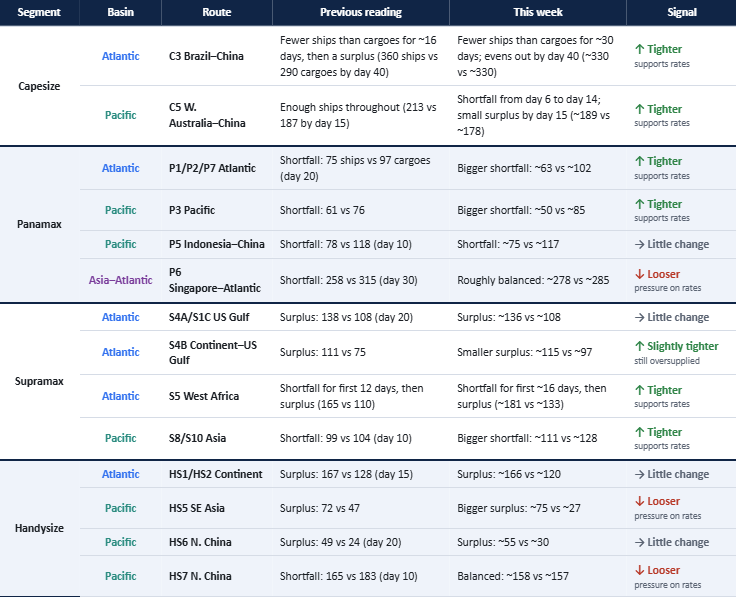
Capesize iron ore routes and Asian Supramax tightened, Panamax Atlantic shortfalls deepened, while Handysize HS7 (North China) and Panamax P6 moved into balance; HS6 remains in surplus. The US Gulf remains oversupplied for Supramax.
FREIGHT MARKET OVERVIEW
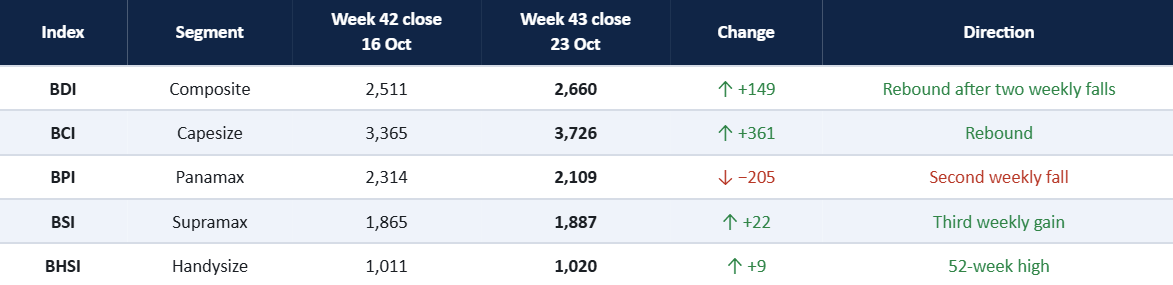
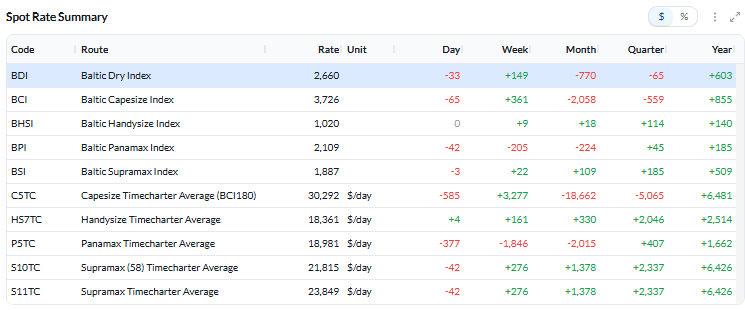
From Week 42 to Week 43. Week 42 was a heavy week for Capesize: the BCI fell 975 points to 3,365, and C5TC(180) dropped to $27,015/day, pulling the BDI down 406 points to 2,511. The previous week, the market recovered part of that loss. The BDI rose 149 points to 2,660 as the BCI regained 361 points and C5TC(180) climbed to $30,292/day. Supramax and Handysize kept their steady climb (BHSI at a 52-week high), while Panamax fell for a second week, with P5TC down from $20,827 to $18,981/day.
Smaller sizes lead. The geared segments are the steadiest part of the market: the BHSI is at a 52-week high, and the BSI is 3 points below its own, with HS3_38 (South Atlantic) +$1,550 and Supramax S3 (North China–West Africa) +$2,050 this week.
KEY TAKEAWAY
- Capesize rates recovered a portion of their Week 42 declines as vessel availability tightened relative to cargo demand on the C3 and C5 iron ore routes.
- Asian Supramax markets strengthened amid regional tonnage scarcity. Conversely, Panamax stood out as a clear exception, dropping for a second consecutive week despite expectations of a deficit in forward vessel supply; a growing ballast fleet in the South Atlantic may be adding downside pressure. Geared tonnage remains oversupplied in the US Gulf.
- Across 29 Middle Eastern ports, 265 vessels are currently waiting—74 at Fujairah, mostly Supramaxes, and mostly on stop calls. With regional congestion running 75% above last year’s levels, available geared tonnage outside the Strait of Hormuz could face persistent operational constraints as long as these ships remain idle.
CAPESIZE
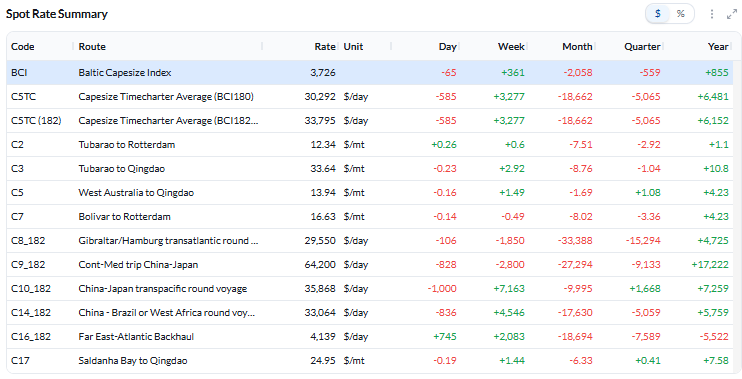
Freight. The BCI rose 361 points to 3,726 and C5TC(180) $3,277 to $30,292/day (C5TC(182) $33,795). The Pacific led: C10_182 +$7,163 to $35,868/day and C5 +$1.49 to $13.94/mt. C3 gained $2.92 to $33.64/mt, and C14_182 gained $4,546 to $33,064/day; C8_182 fell $1,850 to $29,550/day. C9_182 remains the top route at $64,200/day.
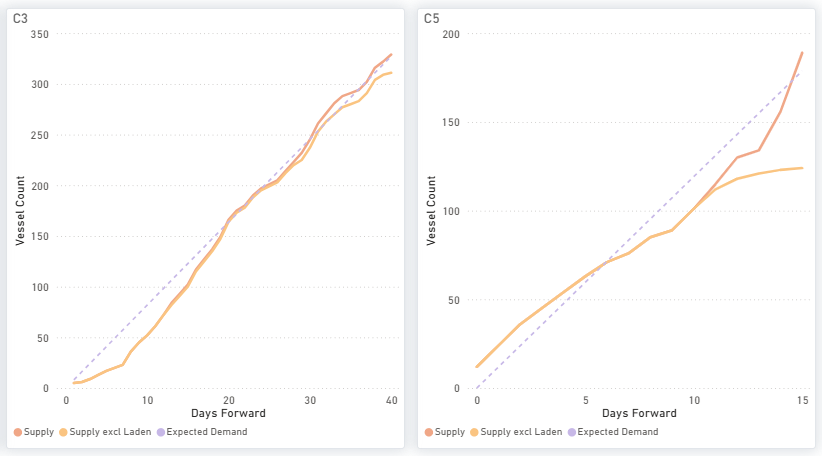
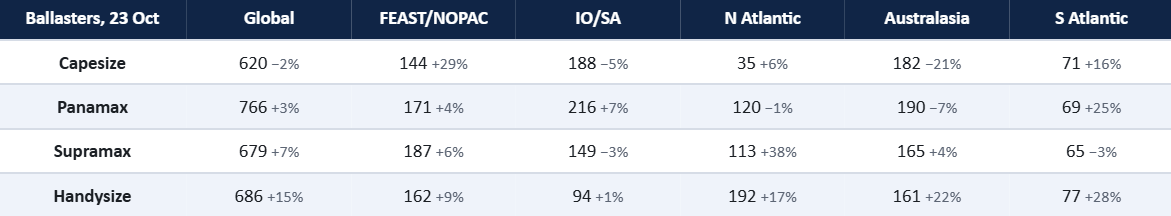
Ships vs cargoes. On C3, there are now fewer ships than cargoes for about the next 30 days, evening out only around day 40 (~330 each), against about 16 days in the previous reading. On C5, ships fall short of cargoes between days 6 and 14. Australasia ballasters fell 21% while FEAST/NOPAC rose 29%, so open tonnage is shifting north rather than disappearing.
PANAMAX
Freight. The BPI fell 205 points to 2,109 and P5TC fell from $1,846 to $18,981/day, with all routes lower. The Atlantic led the fall: P1A_82 −$2,809 to $17,736/day and P2A_82 −$2,577 to $26,520/day (still the top route); P6_82 −$2,455. P7 and P8 eased to $71.94/mt and $53.69/mt.
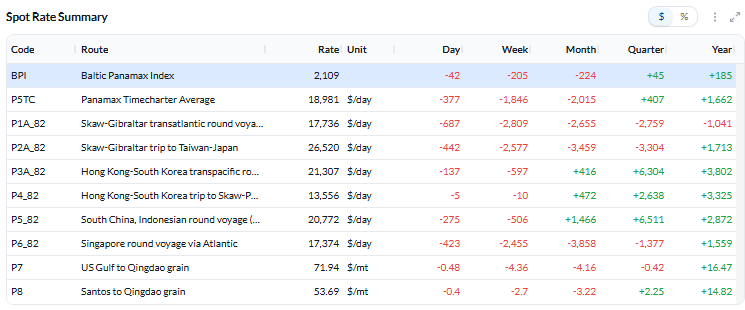
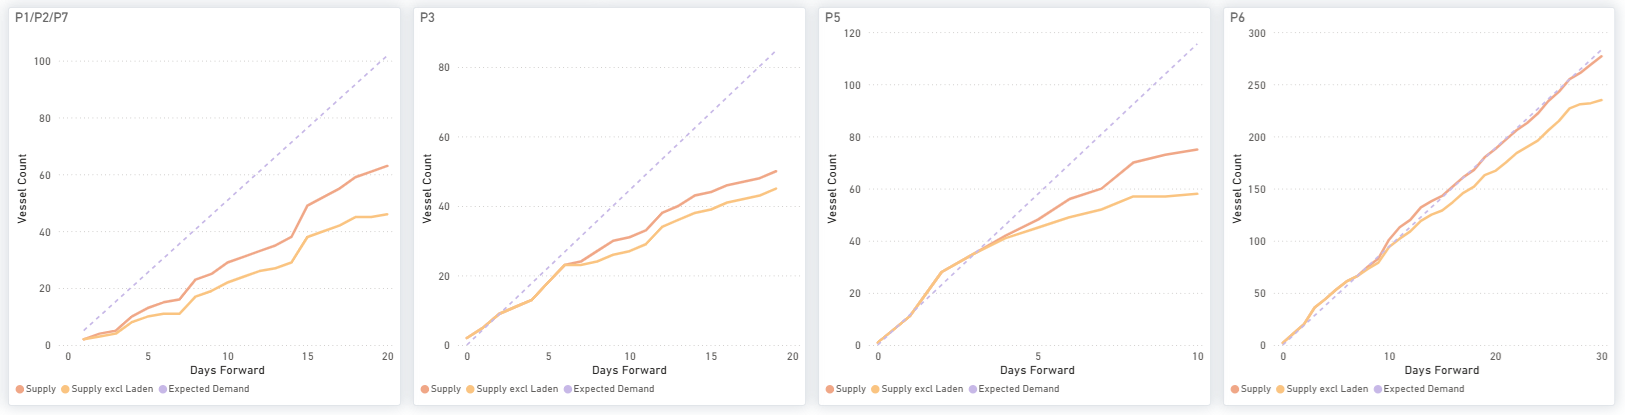
Ships vs cargoes. Forward vessel supply continues to lag behind expected demand across the P1/P2/P7 (~63 vessels against ~102 by day 20), P3, and P5 routes, whereas P6 has approached market balance. Despite these ongoing deficit conditions, freight rates trended lower. Although an influx of ballasters into the South Atlantic (+25%) and Indian Ocean/South Africa region (+7%). The divergence between forward supply–demand balances and declining freight rates suggests that the projected shortages have yet to translate into sustained support for earnings.
SUPRAMAX
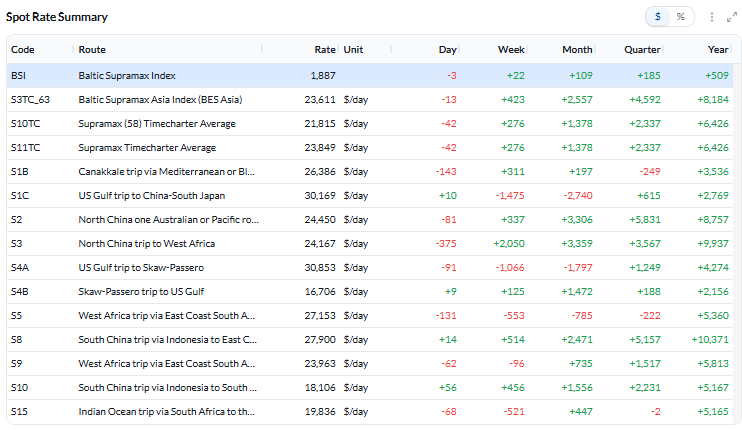
Freight. The BSI edged up 22 points to 1,887, just below its 52-week high of 1,890, and S11TC $276 to $23,849/day. Asia led: S3 +$2,050 to $24,167/day, S8 +$514 to $27,900/day and S10 +$456. The US Gulf eased: S1C −$1,475 to $30,169/day and S4A −$1,066 to $30,853/day (still the top route).
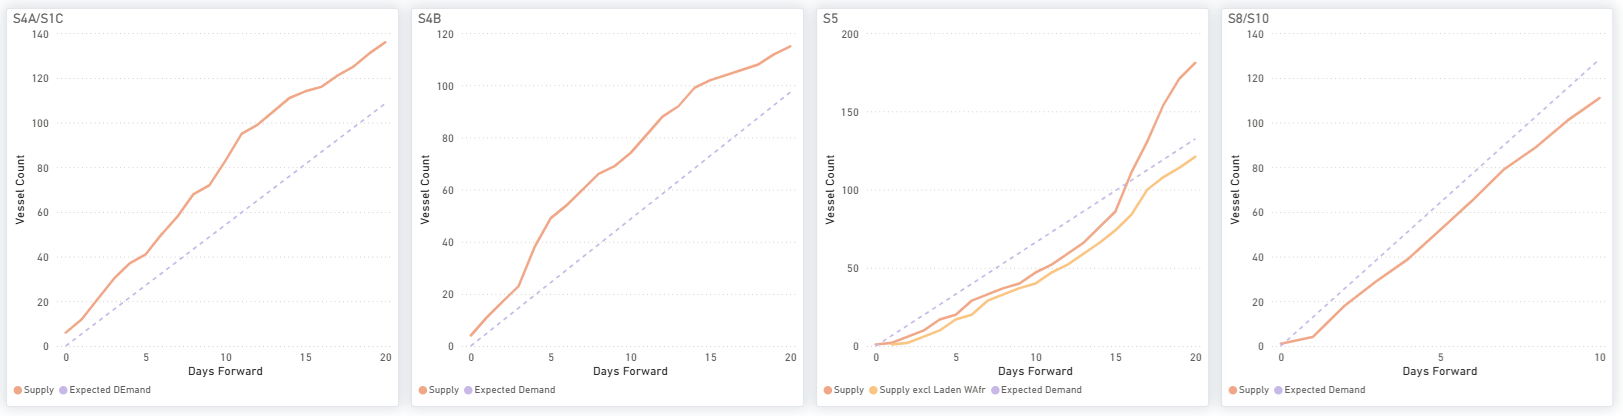
Ships vs cargoes. The US Gulf routes (S4A/S1C, S4B) still have more ships than cargoes, and North Atlantic ballasters jumped 38% to 113. In Asia (S8/S10), ships fall short of cargoes throughout (~111 vs ~128 by day 10), and West Africa (S5) is short for the first ~16 days.
HANDYSIZE
Freight. The BHSI rose 9 points to 1,020, a 52-week high, and HS7TC rose from $161 to $18,361/day. HS3_38 (South Atlantic) gained $1,550 to $30,022/day and remains the top route; HS4_38 (US Gulf) fell $772 to $19,657/day. Asia firmed modestly (HS5 +$200, HS6 and HS7 +$163).
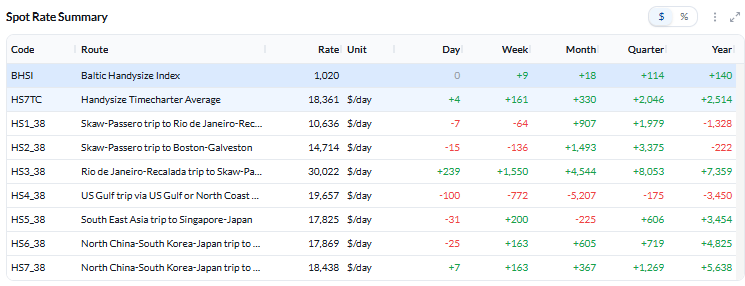
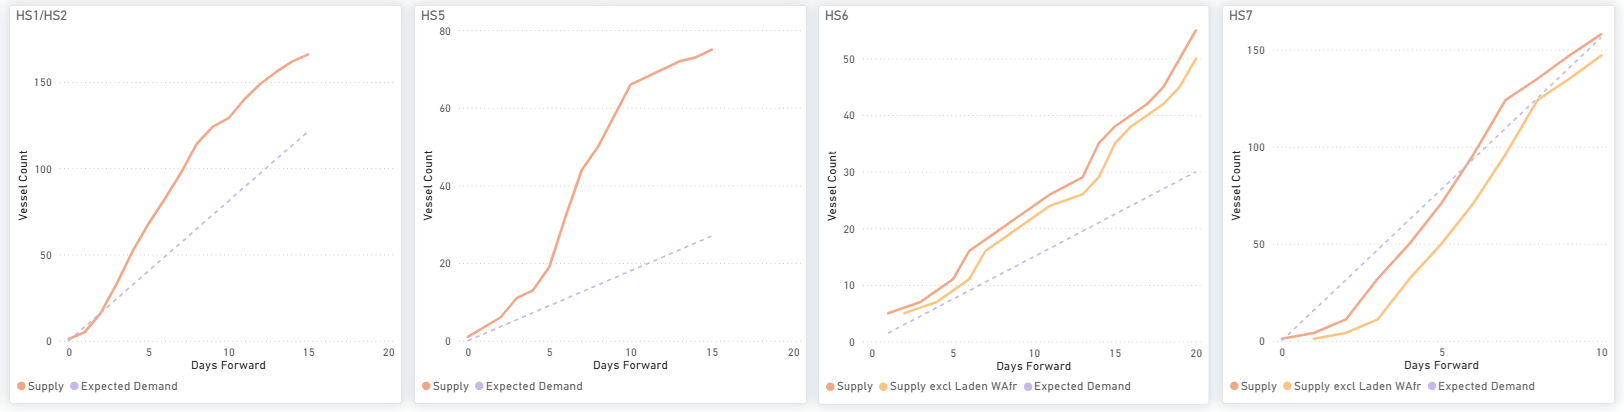
Ships vs cargoes. HS1/HS2, HS5 and HS6 all have more ships than cargoes. HS7, where ships were short of cargoes in the previous reading, is now balanced (~158 vs ~157 by day 10). Global ballasters rose 15% to 686, with gains in every region, which caps further upside.
Source:Signal Ocean



Related News.
ECB keeps rates on hold as Christine Lagarde announced her resignation
With still very little knock-on effects from higher energy prices and headline inflation on the rest of the economy, the ECB kept interest rates on…
ASA SC highlights geopolitical risks to seafarers while tackling workforce and regulatory challenges
The 33rd Interim Meeting of the Asian Shipowners’ Association (ASA) Seafarers Committee (SC) convened online on 16 October 2026, hosted by the China…
US awards $498m to 35 port projects across 19 states
The round uses the last US$450 million of the infrastructure law's port grant commitment. Alaska's Whittier receives US$50.6 million to replace the…
Maritime leaders push for stronger action on global shipping rules in Busan
World Maritime Day Parallel Event spotlights theme “From Policy into Practice: Powering Maritime Excellence”. International delegates meeting in…
Hapag-Lloyd strengthens its position in Italian ports
Italian export volumes of Hapag-Lloyd continue its upward trend, with a further relevant growth expected in 2026 compared with 2025, bringing…
DORIC MONTHLY CHINA BAROMETER OCTOBER 2026
Pls find below the DORIC MONTHLY - CHINA BAROMETER OCTOBER 2026 CHINA_BAROMETER_OCTOBER_2026
BIMCO Dry Bulk Shipping Market Overview & Outlook
Escalating attacks on ships heighten uncertainty "Geopolitical disruptions continue to cloud the dry bulk market outlook. The effective closure of…
Nor-Shipping aims to demystify ship recycling with new conference for 2027
With industry estimates suggesting more than 15,000 vessels will need to be recycled by 2032*, more than double the number recycled in the previous…
San Pedro Bay Ports outline path for Cleaner Marine Fuels
The ports of Long Beach and Los Angeles have released a comprehensive report identifying promising clean marine fuels for oceangoing vessels and…
SFL Newbuild agreements and long-term charters of two 8,800 TEU container vessels and one very large ammonia carrier
SFL Corporation announced that it has agreed to acquire two 8,800 TEU Container Vessels with scheduled delivery in 2027 and one 93,000 cbm dual-fuel…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
