
Rates for shipping containers from east Asia and China to the US were mixed this week as import demand remains soft, capacity ample, but some rate hikes have gained traction.
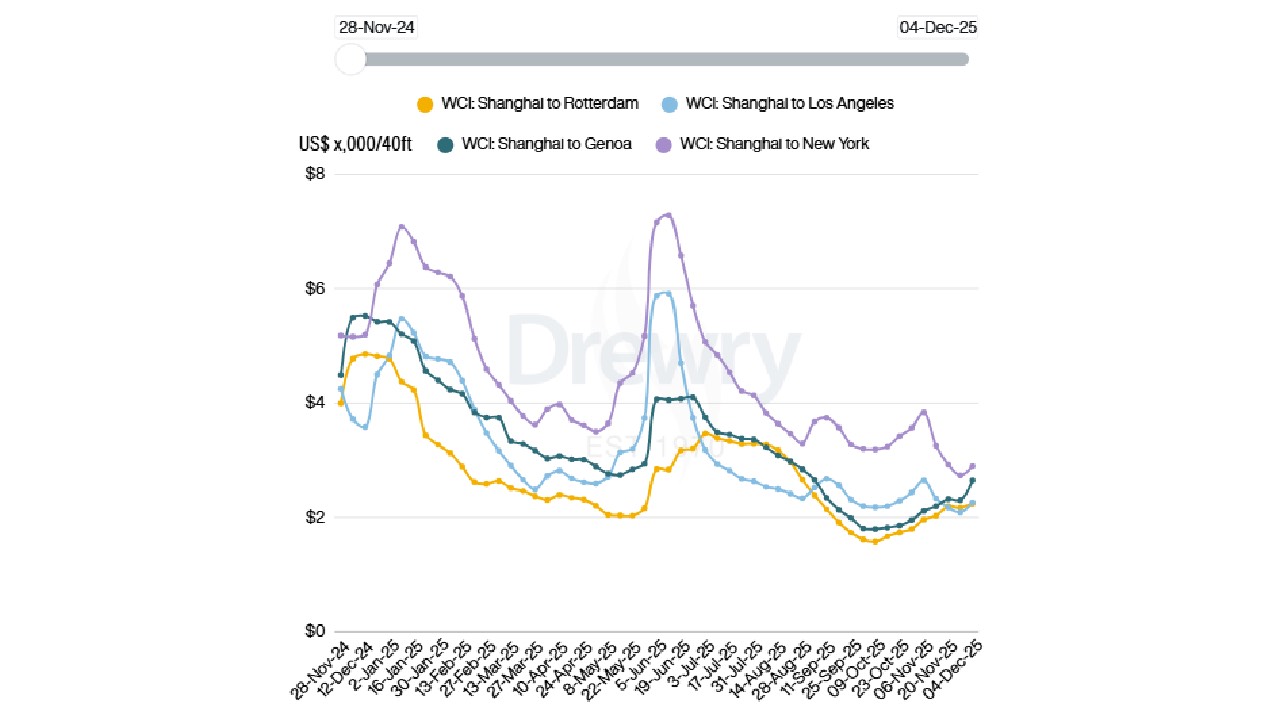
Rates from supply chain advisor Drewry edged higher this week, as shown in the following chart.
Drewry said carriers are shifting away from traditional fortnightly adjustments, with some adopting a weekly strategy for GRIs, Drewry said.
“Instead of announcing large hikes that tend to erode quickly, carriers are now introducing smaller, more frequent increases to maintain consistent upwards pressure on spot rates,” Drewry said. “This strategy appears to have been effective this week, leading Drewry to forecast stable rates in the week ahead.”
Weekly spot rates from online freight shipping marketplace and platform provider Freightos rose this week as demand is as low as it has been since early 2023 and supply side growth is also weighing on rates.
But Judah Levine, head of research at Freightos, said daily rates are trending higher this week, which could signal another general rate increase (GRI) attempt to start December.
Rates from global logistics company Freight Right on its TrueFreight Index (TFX) were mostly steady week-on-week.
Robert Khachatryan, founder and CEO of Freight Right Logistics, said carriers announced 1 December GRIs of $400/FEU (40-foot equivalent unit).
“But at least one line reversed the increase within hours, and others are expected to follow,” Khachatryan said. “As the dust settles, effective spot levels are reverting back to roughly where November closed, in the $1,400–1,500/FEU range, leaving the lane essentially flat week-on-week, despite a very brief spike.”
Rates from ocean and freight rate analytics firm Xeneta also ticked higher this week, but Peter Sand, chief analyst, said fundamentals are still pressuring rates lower.
“The backdrop is still one of oversupply compared to demand and that is seen clearly in the fact rates are still not back to where they were a month ago despite a fairly chunky increase in the past week,” Sand said. “Shippers should reflect on this weaker market the next time a carrier asks for a GRI, because it would not appear to be justified against the level of demand versus capacity.”
Container ships and costs for shipping containers are relevant to the chemical industry because while most chemicals are liquids and are shipped in tankers, container ships transport polymers – such as polyethylene (PE) and polypropylene (PP), which are shipped in pellets. Titanium dioxide (TiO2) is also shipped in containers.
They also transport liquid chemicals in isotanks.
LIQUID TANKER RATES MOSTLY STEADY
The US chemical tanker freight rates were unchanged this week for several trade lanes, except for the USG-Brazil trade lane as spot tonnage remains tight. The market in this direction remains firm, supported by demand for glycols and caustic soda.
Overall, there is all-basis limited spot activity to most regions and as contract of affreightment (COA) nominations are taking longer than usual for the regular vessel owners.
Carriers have tried to delay sailings but there has been very little spot space in the market leaving no other options for full cargoes and in turn impacting spot rates.
Along the route to Asia there are very few fresh cargo inquiries that were seen in the market; however, rates remain relatively stable as most space has been already booked well into the New Year.
MEG, ethanol and styrene still are being seen quoted in the market by various traders, for January loadings to Asia.
Eastbound space had not yet been fully absorbed despite the few fresh inquiries for small specialty parcels stemming from USG bound for Antwerp, and most owners are waiting for full contract nominations. However, there seems to be increased demand for ethanol along this route as several cargoes were seen quoted in the market.
Various glycol, ethanol, methyl tertiary butyl ether (MTBE) and methanol parcels were seen quoted to ARA and the Mediterranean as methanol prices in the region remain higher.
For the USG to India route, the usual cargoes of ethanol, methanol and glycols continue to be seen on this trade lane, although the level of activity seems to be a bit softer than previously seen.
Source: ICIS



Related News.

ISLAND OIL: Unveiling of the Sculpture “Cyprus’s Journey Through the Ages” in Protaras – A Tribute and Landmark to Cyprus’s Historical Memory and Cultural Heritage
In a modest ceremony marked by a moving atmosphere, the sculpture “Cyprus’s Journey Through the Ages”, created by acclaimed Cypriot sculptor…

World Maritime Day 2026 from Policy to Practice – powering Maritime Excellence
Global regulations will deliver safer, more resilient shipping when they are implemented worldwide. The international maritime community marks…

Diana Shipping announces Time Charter Contract for m/v DSI Polaris with Dai An Ocean Shipping
Diana Shipping , a global shipping company specializing in the ownership and bareboat charter-in of dry bulk vessels, announced that, through a…

Chief Economists Expect Global Economy to Stabilize, but Fiscal Constraints, Rising Living Costs and AI Investment Uncertainty Threaten Growth
The global economy is stabilizing, but the fiscal support that cushioned successive shocks since 2020 is unlikely to play the same role in the year…

V. welcomes its new graduate cohort as programme expands across the group
Twelve graduates from nine nationalities join 11th year of V.’s expanded international management programme. V., the global ship manager and marine…

From Policy to Practice: Why Seafarers Are the Key to Maritime Excellence
The shipping industry is no stranger to regulation. Seafarers and ship operators work within a vast framework of international conventions, national…

Intermodal Report – Week 38 2026
Please find below the Intermodal market report for week 38 2026. Intermodal Report Week 38 2026 Market Insight By Nikos Tagoulis, Head of…

Allied – Weekly Market Review – Week 38
Please find below the Allied Weekly Report for Week 38 | 2026 ALLIED - Weekly Market Report- Week 38

Record year on the Northeast Passage but Arctic shipping remains very limited
In 2025, a record 103 transit voyages were made via the Northeast Passage. However, this is still equivalent to only around a day and a half of…

[xclusiv] S&P Report 21th September 2026
Please find below the [xclusiv] latest Weekly S&P Report [xclusiv] 2026_09_21 Market Commentary: VLCCs: Freight Boom Reprices the Fleet The VLCC…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
