Customer login Buy now Commodities Industries Solutions Consulting Insights Events & Training About Try ICIS Home News Asia-US container rates mixed as November rate hikes gain traction on some trade lanes Asia-US container rates mixed as November rate hikes gain traction on some trade lanes
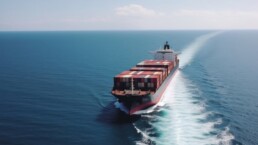

Rates for shipping containers from east Asia and China to the US were mixed this week but increases on some trade lanes indicates that 1 November general rate increases (GRIs) have been partially successful.
Rates from online freight shipping marketplace and platform provider Freightos rose by 4% to the East Coast and fell by 1% to the West Coast.
Rates from supply chain advisors Drewry rose by high-single digits to both coasts, as shown in the following chart.
Drewry said carriers continue to implement GRIs to counter the downward pressure on spot rates from increased capacity.
“However, this upward momentum is expected to be short-lived, with rates likely to soften unless further GRIs are introduced,” Drewry said.
Judah Levine, head of research at Freightos, said daily rates to the West Coast have jumped and are near levels last seen in July.
However, Levine said there are already reports that carriers are offering lower rates.
“Prices to the East Coast have already fallen about $100/FEU (40-foot equivalent unit) this week, suggesting that rate increases on this lane did not take at all,” Levine said.
Spot rates on the Shanghai Containerized Freight Index (SCFI), which tracks rates for containers leaving Shanghai, fell this week after rising for the previous four weeks.
Rates from ocean and freight rate analytics firm Xeneta also rose this week.
Peter Sand, chief analyst at Xeneta, said offered capacity is driving rates in the current environment.
“If you want to understand the dynamics in ocean container shipping right now – just look at the relationship between offered capacity and freight rates on the major fronthaul trades,” Sand said. “Offered capacity is down across all major front hauls compared to a month ago, despite increases on some trades in the past week.”
Sand said carriers are managing capacity very carefully at an important time of year ahead of 2026 contract tenders and this has contributed to average spot rates increasing after an earlier uptick in mid-October.
“There were similar spot rate upticks on 1 November 2024 and 1 November 2023 – this is not a coincidence; it is carriers doing what they do best at a crucial time of year,” Sand said. “Carriers will be pleased with their work of late, but they are battling subdued demand no matter how well they manage capacity, so it is likely gravity starts to win and rates fall back.”
Rates from global logistics company Freight Right on its TrueFreight Index (TFI) showed weekly increases from about $500-800/FEU.
Robert Khachatryan, founder and CEO of Freight Right Logistics, said even with the new agreements between the US and China, businesses globally are now operating in an environment of heightened uncertainty, adapting to tariff risk and recalibrating sourcing and distribution strategies accordingly.
Container ships and costs for shipping containers are relevant to the chemical industry because while most chemicals are liquids and are shipped in tankers, container ships transport polymers, such as polyethylene (PE) and polypropylene (PP), are shipped in pellets. Titanium dioxide (TiO2) is also shipped in containers.
They also transport liquid chemicals in isotanks.
LIQUID TANKER RATES STEADY TO HIGHER
US chemical tanker freight rates assessed by ICIS were stable to higher this week with increases on the US Gulf (USG) to Brazil and USG to Asia trade lanes.
Along the USG to ARA route, there has been relatively slow spot demand from NW Europe. Despite this space remains tight for November, which is keeping the rates stable for now. On the other hand, from the USG moving in this direction, it continues to be supported by contract of affreightment (COA) volumes along with smaller parcels to complete voyages.
We saw 9,000 tonnes ETBE Houston and 7,000 tonnes MEG Lake Charles fixed for early November dates.
Similarly, from the USG to Brazil, COA cargoes continue employing a sizable part of the tonnage, providing support for the market. Overall, the market remains very challenging, and spot rates rose significantly on this trade lane.
The market remains sluggish from the USG to Asia, with very few new inquiries although most traders are trying to work cargoes along this route, pushing rates slightly higher. However, COA volumes remain healthy particularly for specialty chemicals. This could indicate a bit of an end-of-year push for material coupled with taking advantage of the pause on port fees between the US and China.
As a result, there seems to be a tightening of space amongst the regular carriers. If this continues into December, we expect only limited pockets of space to available putting upward pressure on rates.
The USG to India route seems to have emerged as an alternative destination for cargoes bound for Asia as there have been quite a few larger fixtures reported in the market. While we do not quote rates for these types of parcels it is worth noting that if it persists, it could impact smaller volumes. We saw large slugs of ethanol as well as caustic soda for November dates.
Source:ICIS



Related News.
European Shipowners call on MEPs to back Commission proposal to include two Indian yards in the EU ship recycling list
The Environment Committee of the European Parliament votes on 4 November on a motion for resolution objecting to the Commission’s proposal to add two…
Oversea signs commercial agreement with UECC following Successful Pilot
Following a successful pilot onboard Auto Advance, UECC has chosen to enter into a commercial agreement with Oversea. The pilot demonstrates how…
First NABEP Crude Cargo Under U.S. Agreement Arrives in Texas
Shipment of 1 million barrels arrived as NABEP production passes 223,000 barrels of oil equivalent per day. Two tankers carrying 1 million barrels of…
LNG carrier prices fall to $245 million, threatening Korean Shipbuilders’ Margins
Prices for high-value vessels, including liquefied natural gas carriers and ultra-large container ships, have begun to decline despite rising…
Vehicle Carrier Safety Forum publishes new Fire Drill Guidelines for vehicle carrying vessels
The Vehicle Carrier Safety Forum has published new Fire Drill Guidelines for Vehicle Carrying Vessels, providing vessel operators with a practical…
Is an Atlantic Basin crude glut on the cards?
Atlantic crude discounts fail to offset high freight to Asia, raising the risk of a regional glut as VLCC availability tightens. Freight…
The future of trade infrastructure in Europe is connectivity
One year after its inauguration, Rijeka Gateway offers a glimpse into the future of European trade. On 10 September last year,…
Allied – Weekly Market Review – Week 43
Please find below the Allied Weekly Report for Week 43 | 2026 ALLIED - Weekly Market Report- Week 43
Intermodal Report – Week 43 2026
Please find below the Intermodal market report for week 43 2026. Intermodal Report Week 43 2026
Wind Challenger-Equipped LNG Dual-Fueled Coal Carrier ‘MAIZURU KAZENOMAI’ Delivered
-While Supporting a Stable Energy Supply, Reducing Environmental Impact - Mitsui O.S.K. Lines announced the delivery and entry into service of an…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
