Structural Market shifts, not just Barrels, powering the Dirty Rally

Freight Rates Surge as Inefficiencies Mount
Crude freight markets are experiencing another surge, with spot rates for VLCC, Suezmax, and Aframax segments reaching multi-month highs exceeding WS100. Crude freight markets are experiencing another surge, with spot rates for VLCC AG–China, Suezmax WAFR–Continent, and Aframax Mediterranean routes all climbing to multi-month highs. As of 6 November 2025, VLCC AG–China stands around WS107 (up +114% y/y), Suezmax WAFR–Continent near WS160 (up +76% y/y), and Aframax Med at roughly WS198 (up +66% y/y), while the Baltic Dirty Tanker Index (BDTI) has reached 1,403, marking a +49% y/y gain. While this might initially suggest a surge in tonne-mile demand from longer-haul trades, the data tells a more complex story. Tonne-miles in 2025 have averaged around 40–41 billion, staying consistently below early-2024 levels of roughly 42–43 billion. The 2025 trend curves lower throughout most of the year, only narrowing the gap in late Q3.
The Hidden Driver: Tonne-Days Remain ElevatedTonne-days have risen to about 250 million by Q4, hitting multi-year peaks from the lows of below 220 million in early 2025. This indicates not shorter trade distances, but slower fleet circulation and increasing inefficiencies. Oil still reaches its destination; it just takes longer to arrive. Operational hurdles are causing a slowdown due to sanctions, port fees, and compliance issues that have disrupted voyage routes and vessel deployment. Ships are experiencing longer clearance times, not necessarily from physical port delays, but from strategic repositioning to avoid expensive terminals and reassign vessels for ship-to-ship operations. Each voyage now faces a greater administrative load, including sanction checks, insurance verifications, and document compliance, all of which add extra days at sea. Overall, this results in inflated tonne-days and an artificially tight freight market. The Oil Glut Narrative
At first glance, the market appears to be facing an emerging oil surplus. Floating storage among non-sanctioned dirty tankers has risen to just over 70 million barrels as of late October, surpassing recent seasonal norms and inviting comparisons with earlier periods of oversupply. Yet, the current buildup may indicate more of a logistical pause than a genuine excess of crude.
Part of the recent increase seems linked to longer discharge intervals and uneven cargo scheduling, as trade flows adjust to shifting freight economics and evolving compliance frameworks. Some vessels are remaining on the water longer than usual, not necessarily because of weak demand but as a by-product of operational reshuffling across routes and terminals. These barrels are perceived as “stored” by the market, yet they are, in fact, merely awaiting clearance or redirection. Compared with past supply-driven gluts, today’s conditions appear more transitional than structural. The rise in floating storage seems to reflect temporary friction in seaborne logistics rather than a breakdown in underlying balances. Even with the recent uptick, volumes remain well below the 150 million barrels recorded in late June and far beneath the pandemic highs of 2020. Should the sanctioned fleet be included, the picture becomes more complex. Floating storage among sanctioned vessels has recently climbed above 30 million barrels, marking one of the highest levels since mid-2022. This rise may reflect growing challenges in clearing sanctioned oil, either because cargoes face delays in obtaining discharge approvals, vessels become sanctioned mid-voyage and are subsequently rejected, or buyers quietly adjust their procurement policies to mitigate compliance risk. Collectively, these dynamics suggest that geopolitical segmentation and shifting regulatory behavior now appear to play a larger role in determining how and where oil is held, subtly influencing perceptions of available supply.
Recent Individual Vessel Behaviour Further Illustrates Market Distortion Recent voyage behaviour in the dirty tanker segment has highlighted cases of mid-route reversals and destination changes, illustrating how market uncertainty can affect fleet efficiency. In two notable instances, tankers initially appeared bound for U.S. discharge zones before altering course toward European destinations, while another shifted direction via the Mediterranean before continuing west. These shifts may reflect a mix of revised trading programs, buyer policy adjustments, or compliance reviews introduced late in the voyage. In certain instances, vessels have remained in waiting positions for extended periods before receiving new discharge instructions, suggesting clearance complications or shifting commercial priorities rather than simple port congestion. Each change adds time-on-water and limits effective fleet rotation, tightening the supply of available tonnage in the spot market. |


Source: Signal Ocean



Related News.
European Shipowners call on MEPs to back Commission proposal to include two Indian yards in the EU ship recycling list
The Environment Committee of the European Parliament votes on 4 November on a motion for resolution objecting to the Commission’s proposal to add two…
Oversea signs commercial agreement with UECC following Successful Pilot
Following a successful pilot onboard Auto Advance, UECC has chosen to enter into a commercial agreement with Oversea. The pilot demonstrates how…
First NABEP Crude Cargo Under U.S. Agreement Arrives in Texas
Shipment of 1 million barrels arrived as NABEP production passes 223,000 barrels of oil equivalent per day. Two tankers carrying 1 million barrels of…
LNG carrier prices fall to $245 million, threatening Korean Shipbuilders’ Margins
Prices for high-value vessels, including liquefied natural gas carriers and ultra-large container ships, have begun to decline despite rising…
Vehicle Carrier Safety Forum publishes new Fire Drill Guidelines for vehicle carrying vessels
The Vehicle Carrier Safety Forum has published new Fire Drill Guidelines for Vehicle Carrying Vessels, providing vessel operators with a practical…
Is an Atlantic Basin crude glut on the cards?
Atlantic crude discounts fail to offset high freight to Asia, raising the risk of a regional glut as VLCC availability tightens. Freight…
The future of trade infrastructure in Europe is connectivity
One year after its inauguration, Rijeka Gateway offers a glimpse into the future of European trade. On 10 September last year,…
Allied – Weekly Market Review – Week 43
Please find below the Allied Weekly Report for Week 43 | 2026 ALLIED - Weekly Market Report- Week 43
Intermodal Report – Week 43 2026
Please find below the Intermodal market report for week 43 2026. Intermodal Report Week 43 2026
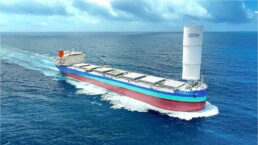
Wind Challenger-Equipped LNG Dual-Fueled Coal Carrier ‘MAIZURU KAZENOMAI’ Delivered
-While Supporting a Stable Energy Supply, Reducing Environmental Impact - Mitsui O.S.K. Lines announced the delivery and entry into service of an…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
