The immediate outlook for Q1 2025 appears bullish, but despite turnarounds and a cold approaching winter, the time to get short feels around the corner

December 6, 2024
Commentary summary:
– USGC arbs to Europe just about closed still whilst Middle Eastern diesel arbs still marginally point East
– Asian diesel and jet spreads gain over the last week whilst every other distillate spread and crack falter over the last fortnight. However, diesel remains in backwardation until late Summer 2025.
– Whilst Chinese diesel and jet exports continue to struggle, Russian and South Korean exports continue to increase.
– We are set for a particularly cold winter in Europe and North America.
– Bullish in the very prompt, but once the diesel arbs fully reopen to Europe we would be looking to get short. It should be noted here that Middle Eastern diesel arbs have to navigate the Cape still which results in a close to 6 week journey time before they can relieve Europe.
Image
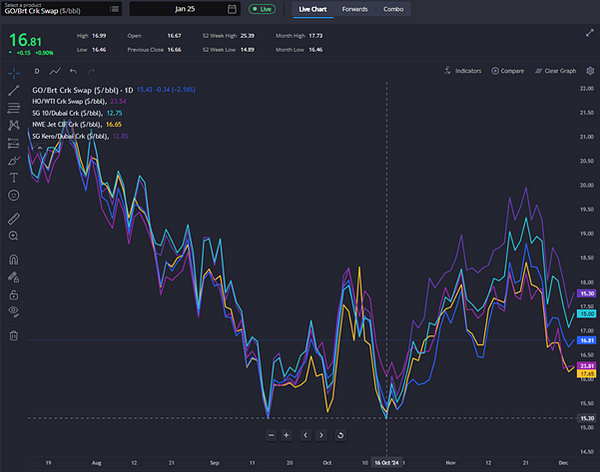
(December’s global diesel and jet cracks)
The global distillate market, while broadly bullish since the start of Q4 2024, has shown signs of softening over the past fortnight, with diesel and jet cracks faltering.
Nonetheless, there remain compelling bullish signals in the prompt, bolstered by approaching US Gulf Coast maintenance in Q1 2025 as part of larger global maintenance in that period, lingering Middle Eastern maintenance currently, and the onset of a cold winter—factors that continue to underpin market optimism.
Although contentious, the prompt outlook for distillates remains positive.
Image
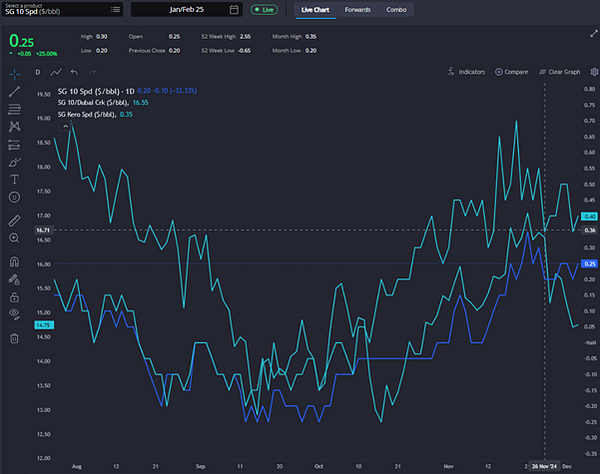
(January’s Singapore diesel spread & crack and jet spread)
In Asia, Singapore diesel and jet cracks have declined, yet spreads for both products have strengthened over the past week, reflecting resilience in the region.
Image
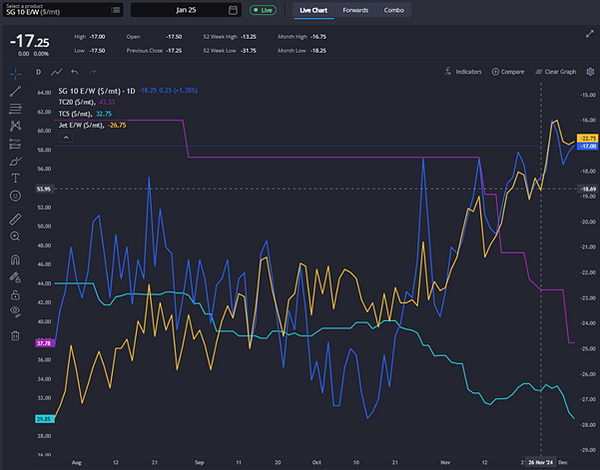
(January’s GO & Jet E/W and TC5 & TC20 freight rates)
East Asian distillate continues to show strength, as evidenced by narrowing jet and gasoil East-West spreads.
While Middle Eastern jet cargoes are now heading West, diesel flows remain marginally East-bound, though arb margins between East and West continue to narrow.
Image
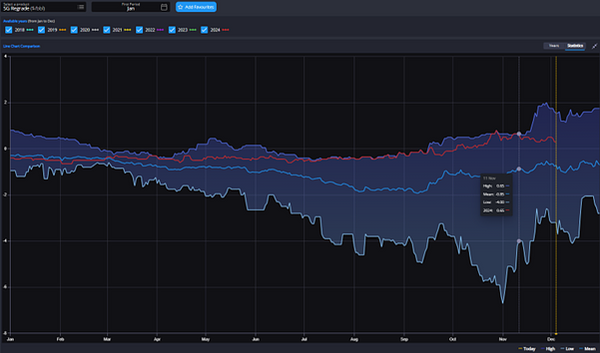
(January’s Singapore regrade)
Meanwhile, global supply dynamics are shifting. Diesel exports from Russia (Tuapse refinery is back online) and South Korea are increasing, adding complexity to trade flows.
Singapore regrade has also been declining for three consecutive weeks, reducing the incentive for diesel to move into the jet pool—a trend mirrored in the fuel oil market. However, HSFO cracks are almost positive so there is some strength there.
Image
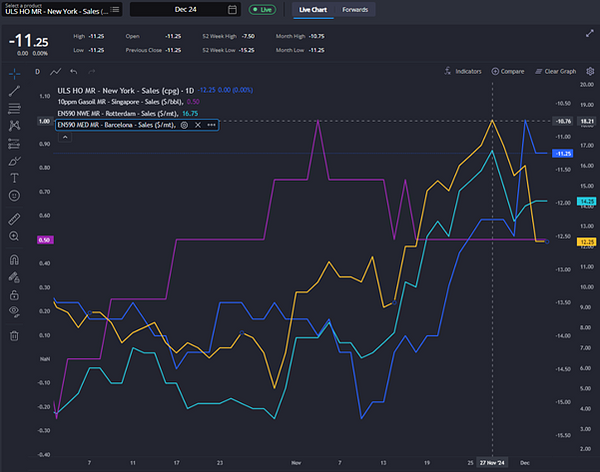
(December’s New York, Singapore, Rotterdam and Barcelona sales premia)
In Europe and the US, a cold winter has driven up NWE and US Atlantic Coast diesel premia, contrasting with declines in Singapore and Mediterranean diesel premia over the past fortnight.
These regional variations highlight the diverse drivers influencing the market, from weather to geopolitics (including its influence on natural gas prices) and refining economics.
Overall, while cracks and premia exhibit a mixed picture, the market remains tilted towards bullishness in the prompt.
As the industry navigates these dynamics, monitoring arb flows, maintenance schedules, and export trends will be critical to understanding whether the recent softening marks a turning point or a temporary pause in the global distillates market’s upward trajectory.


Image
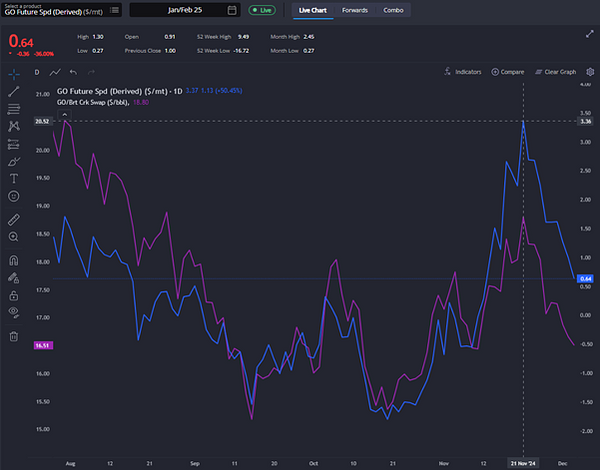
(January’s GO & HO crack and spread)
Image
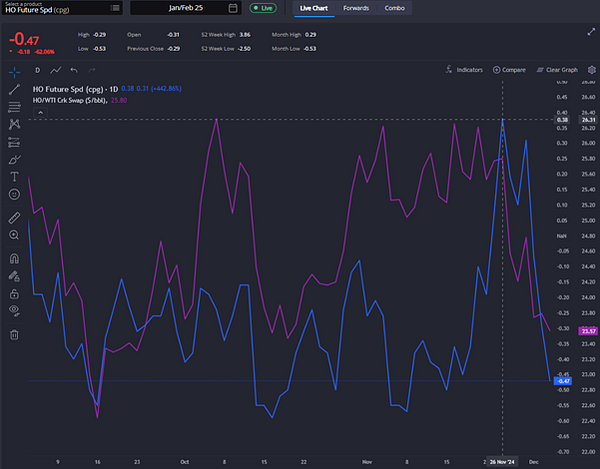
(January’s GO & HO crack and spread)


ICE Gasoil (GO) and Heating Oil (HO) cracks and spreads have shown signs of faltering over the past week, yet both markets (apart from prompt HO) remain in backwardation until summer 2025.
This reflects underlying tightness, despite signs of stock builds in some regions, particularly the US.
Image
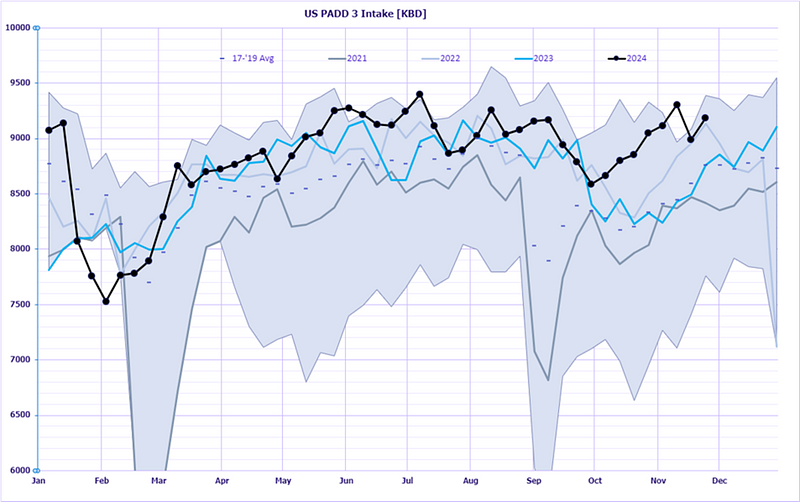
(US PADD 3 crude runs)


Image
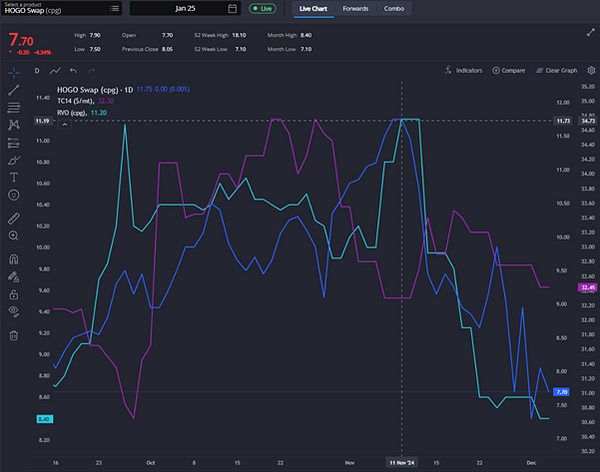
(January’s HOGO swap, TC14 freights and RVO)
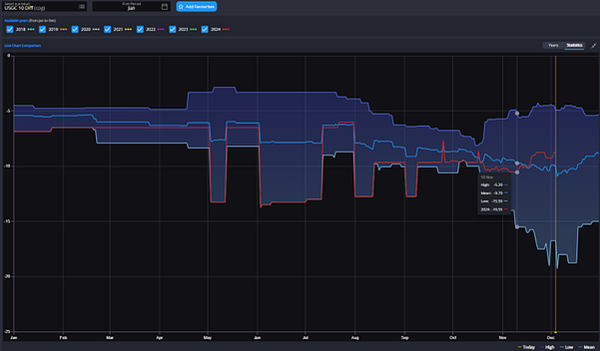
In the USGC, crude runs and middle distillate stocks continue to rise, yet the USGC differential has narrowed, driven by anticipation of regional turnarounds in January and February, tightness in the southeastern US, and rising Colonial Pipeline line space values, which indicate a robust pipeline arb to the northeastern states currently.
Image
(January’s HOGO swap, TC14 freights and RVO)
Despite narrowing HOGO spreads over the past few weeks, (declining Renewable Volume Obligation (RVO) costs are important to consider also) and falling TC14 freight rates, the transatlantic arb from the USGC to Europe remains firmly closed.


Image
(Rotterdam)
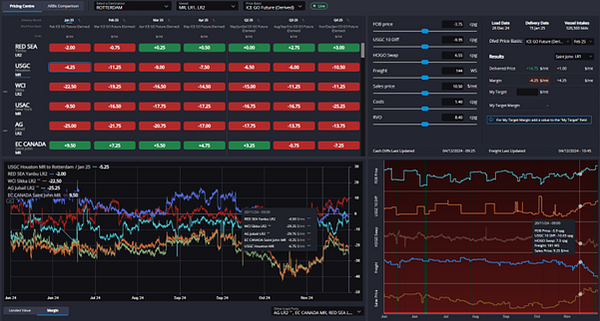
Brokers report no offers for December waterborne diesel loadings in the USGC, underscoring this lack of transatlantic movement.
Image
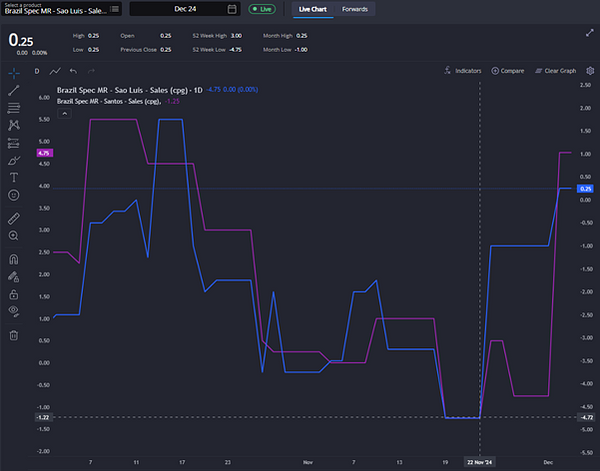
(December’s Sao Luis, Brazil and Santos, Brazil MR sales premia)
This occurs even as Brazilian diesel sales premia rise, pointing to stronger pull from Latin America, though increasing Russian diesel exports should help to offset much of this demand.
The persistent closure of USGC arbs to Europe, coupled with strengthening demand in the East that continues to draw Middle Eastern distillates, maintains the bullish sentiment for December/January and January/February spreads.
However, this bullish outlook is likely to soon wane. With the reopening of transatlantic arbs to Europe expected in early 2025 or sooner, and as bullish drivers such as USGC maintenance and Middle Eastern tightness dissipate, February/March positions could soon present a compelling short opportunity.
In this context, while immediate sentiment remains tilted towards strength, market participants must remain vigilant.
The shift from tight prompt conditions to improved supply flows could mark the point at which the balance tilts, providing a clear path for recalibrating trading strategies.
Source: Sparta Commodities

Related News.

Subscribe to our newsletter!

if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!

* indicates required
Consent *
By submitting this form you agree to receive Email Marketing

Design & Development by P.KAN.DESIGNER

Design & Development by P.KAN.DESIGNER

Privacy Preference Center