Container trading and leasing rates stabilize in China amid high inventories in the US and approaching peak season

Container xChange, the global online marketplace for container trading and leasing, released new data that provides insights into the latest container leasing rate trends from China to the U.S. and Europe. As the global container shipping industry faces ongoing challenges, the data indicates a plateauing trend in container leasing rates, with significant regional variations.
According to the U.S. Census Bureau, U.S. retail sales demonstrated resilience, reaching $615.00 billion in July 2024, a 1.08% increase from the previous month and a 2.55% rise compared to the same period last year. This growth, coupled with a 0.3% month-over-month increase in wholesale inventories and a 0.8% rise in retail inventories, indicates that businesses are gearing up for the upcoming peak season. However, the key question remains how consumer demand will unfold in the coming months, which will determine the effectiveness of this inventory buildup.
The current situation is a very crucial one for the container shipping industry because the consumer demand momentum for the peak season will determine further container price development in the near term.
According to the global container market forecaster published by Container xChange, the global Container Price Sentiment Index (xCPSI) peaked at 83 in May, reflecting strong optimism for rising container prices. However, by mid-August, the index had moderated to around 39. Each week, we survey supply chain professionals on their expectations for future container prices, and from this data, we compute and index the sentiment to generate our Container Price Sentiment Index (xCPSI).
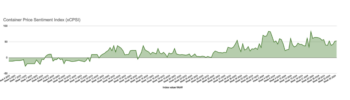
Figure 1: xCPSI, Container Price Sentiment Index by Container xChange, as on 04 September 2024
China to U.S. Leasing Rates: Stabilizing After Steady Increases
According to Container xChange, average one-way leasing charges for 40 ft high cube containers from China to the U.S. saw a noticeable increase from July to August 2024. Key stretches such as:
- Ningbo to Seattle: Leasing rates increased from $695 in July to $858 in August.
- Qingdao to Seattle: Rates rose from $1,334 in July to $1,545 in August.
- Shanghai to Savannah: Rates climbed from $1,245 in July to $1,336 in August.
- Shenzhen to Savannah: Rates jumped from $1,530 in July to $1,830 in August.
- Shenzhen to Seattle: Rates surged from $1,106 in July to $1,482 in August.
While these routes experienced rising leasing rates, other stretches from China to the U.S. have seen decreases, signaling that the upward trend may be starting to plateau. This stabilization is in line with broader market trends observed in average container prices for trading, which have also shown signs of leveling off.
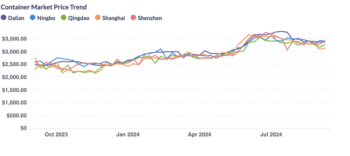
Figure 2: Average prices for 40 ft high cube cargo worthy containers across key ports in China, source: Container xChange
China to Europe: Rates Peaking After Prolonged Increases
Container leasing rates from China to Europe followed a similar pattern, with prices increasing steadily until June 2024. Since then, rates have plateaued, with some routes even reporting slight declines. This stabilization is likely due to order fulfillment activity ahead of the Golden Week holiday in early October, a seasonal effect that typically influences shipping dynamics.
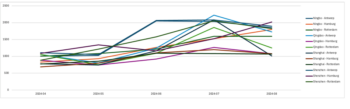
Figure 3: Average one-way pickup charges for 40 ft high cube cargo worthy containers on China to Europe stretches, Source: Container xChange
Regional Volatility in August 2024
The global container market also witnessed significant regional volatility in August 2024. Central Asia reported the highest container spot rate increase, with prices rising by an average of 40%. The Middle East & Indian Subcontinent region followed with a 10% increase, while Japan & Korea experienced an 8% hike. These regional disparities highlight the complexities of the global container market and the varying demand dynamics across different regions.
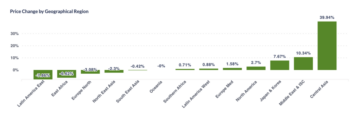
Figure 4: Regional Volatility in average container prices – August 2024, Source: Container xChange
Christian Roeloffs, CEO of Container xChange, commented on the findings: “As we move through 2024, the stabilization of container leasing rates, particularly from China to key global destinations, reflects a market that is adjusting to ongoing disruptions and evolving demand. While we are seeing plateauing rates, it’s crucial to monitor these trends closely, especially with the upcoming Golden Week in China and potential shifts in global economic conditions.”
“As we look ahead, the key question remains: How will freight rates and container prices evolve over the next 3 to 6 months? On the one hand, several factors could keep rates elevated or at least stable. Ongoing disruptions in the Red Sea, for example, continue to absorb capacity, with no clear resolution in sight. Additionally, labour disputes at Canadian railroads and U.S. East Coast terminals are causing delays in container turnaround times. This means containers are spending more time in transit, requiring more containers to handle the same amount of freight, which supports higher rates.” Shared Christian Roeloffs, cofounder and CEO of Container xChange.
“However, there are strong arguments for rates to decline in the coming months. 2024 is on track to become the second-highest year for container deliveries, with manufacturers booked solid through October. The year is shaping up to be one of the strongest years for container production on record. As the same is true for new vessel deliveries, these capacity injections could lead to oversupply despite ongoing disruptions. There’s also uncertainty around the U.S. economy, with pressure on the Fed to cut interest rates at a relatively fast pace due to looming challenges in the labour market. If the economy slows, we may not see the continued demand growth needed to support current freight rates.”
“Moreover, new entrants on trans-Pacific routes, such as TS Line, SeaLead Shipping, and others, are already putting pressure on established carriers by undercutting rates. This could trigger a price war, which may extend to other trade lanes, putting further downward pressure on rates.” inferred Roeloffs.



Related News.

ISLAND OIL: Unveiling of the Sculpture “Cyprus’s Journey Through the Ages” in Protaras – A Tribute and Landmark to Cyprus’s Historical Memory and Cultural Heritage
In a modest ceremony marked by a moving atmosphere, the sculpture “Cyprus’s Journey Through the Ages”, created by acclaimed Cypriot sculptor…

World Maritime Day 2026 from Policy to Practice – powering Maritime Excellence
Global regulations will deliver safer, more resilient shipping when they are implemented worldwide. The international maritime community marks…

Diana Shipping announces Time Charter Contract for m/v DSI Polaris with Dai An Ocean Shipping
Diana Shipping , a global shipping company specializing in the ownership and bareboat charter-in of dry bulk vessels, announced that, through a…

Chief Economists Expect Global Economy to Stabilize, but Fiscal Constraints, Rising Living Costs and AI Investment Uncertainty Threaten Growth
The global economy is stabilizing, but the fiscal support that cushioned successive shocks since 2020 is unlikely to play the same role in the year…

V. welcomes its new graduate cohort as programme expands across the group
Twelve graduates from nine nationalities join 11th year of V.’s expanded international management programme. V., the global ship manager and marine…

From Policy to Practice: Why Seafarers Are the Key to Maritime Excellence
The shipping industry is no stranger to regulation. Seafarers and ship operators work within a vast framework of international conventions, national…

Intermodal Report – Week 38 2026
Please find below the Intermodal market report for week 38 2026. Intermodal Report Week 38 2026 Market Insight By Nikos Tagoulis, Head of…

Allied – Weekly Market Review – Week 38
Please find below the Allied Weekly Report for Week 38 | 2026 ALLIED - Weekly Market Report- Week 38

Record year on the Northeast Passage but Arctic shipping remains very limited
In 2025, a record 103 transit voyages were made via the Northeast Passage. However, this is still equivalent to only around a day and a half of…

[xclusiv] S&P Report 21th September 2026
Please find below the [xclusiv] latest Weekly S&P Report [xclusiv] 2026_09_21 Market Commentary: VLCCs: Freight Boom Reprices the Fleet The VLCC…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
