Europe & Africa Market Update 11 Jul 2024 by ENGINE

Regional bunker benchmarks in European and African ports have moved in mixed directions, and bunker demand is low off Malta.
Changes on the day to 09.00 GMT today:
- VLSFO prices up in Durban ($1/mt), and down in Rotterdam and Gibraltar ($2/mt)
- LSMGO prices up in Durban ($6/mt) and Gibraltar ($5/mt), and unchanged in Rotterdam
- HSFO prices up in Rotterdam ($3/mt) and unchanged in Gibraltar
HSFO supply remains tight in Rotterdam and in the wider ARA hub, according to two sources. Suppliers are unsure when the replenishment cargoes will arrive. This has contributed to push Rotterdam’s HSFO price up in the past day, while its VLSFO price has decreased some. As a result, the port’s Hi5 spread has narrowed from $63/mt yesterday to $58/mt now.
Recommended lead times for HSFO in Rotterdam have increased from 3-5 days last week to 5-7 days now.
Bunkering is progressing normally in Ceuta amid conducive weather conditions. 14 vessels are due to arrive for bunkers in Ceuta today, up from 10 yesterday, said shipping agent Jose Salama & Co. Two vessels are currently waiting to bunker at berth and one vessel at the anchorage in Ceuta, it said.
Demand has been poor in other Mediterranean ports like Piraeus, Malta Offshore and Istanbul, a trader said. Bunker fuel availability is good for prompt delivery dates in these ports, with recommended lead times of 3–4 days for all grades.
The Canary Islands’ port of Las Palmas continues to face subdued bunker demand, a trader told ENGINE. Lead times of 3-5 days are recommended there. Availability of all grades is said to be normal.
Brent
The front-month ICE Brent contract gained $0.35/bbl on the day, to trade at $85.26/bbl at 09.00 GMT.
Upward pressure:
Brent crude price has rebounded as the global oil market focused on oil demand growth factors, following a decline in US crude stocks. Commercial crude oil inventories in the US dropped by 3.44 million bbls to 445 million bbls in the week ending 5 July, the US Energy Information Administration (EIA) reported.
The EIA reported a drop in crude stockpiles, “more than the API report suggested,” ANZ Bank’s senior commodity strategist Daniel Hynes remarked. The robust travel around the US Independence Day holiday was the driving force behind the strong demand, he added.
Market reports released yesterday have added to the market’s expectations of increased oil demand this year. In its July oil market report, the EIA stated that it anticipates a 1.1 million b/d increase in global oil demand to reach 102.9 million b/d in 2024 and an increase of 1.8 million b/d to 104.7 million b/d in 2025.
OPEC, on the other hand, has maintained its demand growth forecast at 2.25 million b/d in 2024 and 1.85 million b/d next year. The oil-producers group continues to bank on its “aggressive” demand growth forecast, two analysts from ING Bank said.
Oil prices also gained after the US Federal Reserve’s chairman Jerome Powell, delivered a second testimony at the US Senate Banking Committee, prompting market participants to expect an interest rate cut in September. Lower interest rates help to support demand growth by making dollar-denominated commodities, such as oil, more affordable for non-dollar holders.
“Federal Reserve Chair Jerome Powell’s second day of testimony on Capitol Hill keeps the hopes of a September rate cut alive and kicking,” SPI Asset Management’s managing partner Stephen Innes said.
Downward pressure:
Following Hurricane Beryl’s minimal disruption to the Gulf Coast energy infrastructure, supply concerns from the US have subsided, which has resulted in some downward pressure on Brent.
The OPEC+ oil market report for the current month mentioned that key producers from the coalition continued to pump above their designated production quotas in June.
“Data published by the OPEC secretariat showed some members, including Iraq, Kazakhstan and Russia, are collectively producing several hundred thousand barrels a day above quota,” Hynes noted.
These producers are expected to reduce oil output to make up for the overproduction in the first six months of this year.
The US Consumer Price Index (CPI) data is due later today. The data is expected to shed light on US inflation growth last month, which will be a key indicator for the Fed to decide the roadmap for interest rate cuts in 2024.
Source: ENGINE by Manjula Nair and Aparupa Mazumder


Related News.
ISLAND OIL: Unveiling of the Sculpture “Cyprus’s Journey Through the Ages” in Protaras – A Tribute and Landmark to Cyprus’s Historical Memory and Cultural Heritage
In a modest ceremony marked by a moving atmosphere, the sculpture “Cyprus’s Journey Through the Ages”, created by acclaimed Cypriot sculptor…
World Maritime Day 2026 from Policy to Practice – powering Maritime Excellence
Global regulations will deliver safer, more resilient shipping when they are implemented worldwide. The international maritime community marks…

Diana Shipping announces Time Charter Contract for m/v DSI Polaris with Dai An Ocean Shipping
Diana Shipping , a global shipping company specializing in the ownership and bareboat charter-in of dry bulk vessels, announced that, through a…
Chief Economists Expect Global Economy to Stabilize, but Fiscal Constraints, Rising Living Costs and AI Investment Uncertainty Threaten Growth
The global economy is stabilizing, but the fiscal support that cushioned successive shocks since 2020 is unlikely to play the same role in the year…
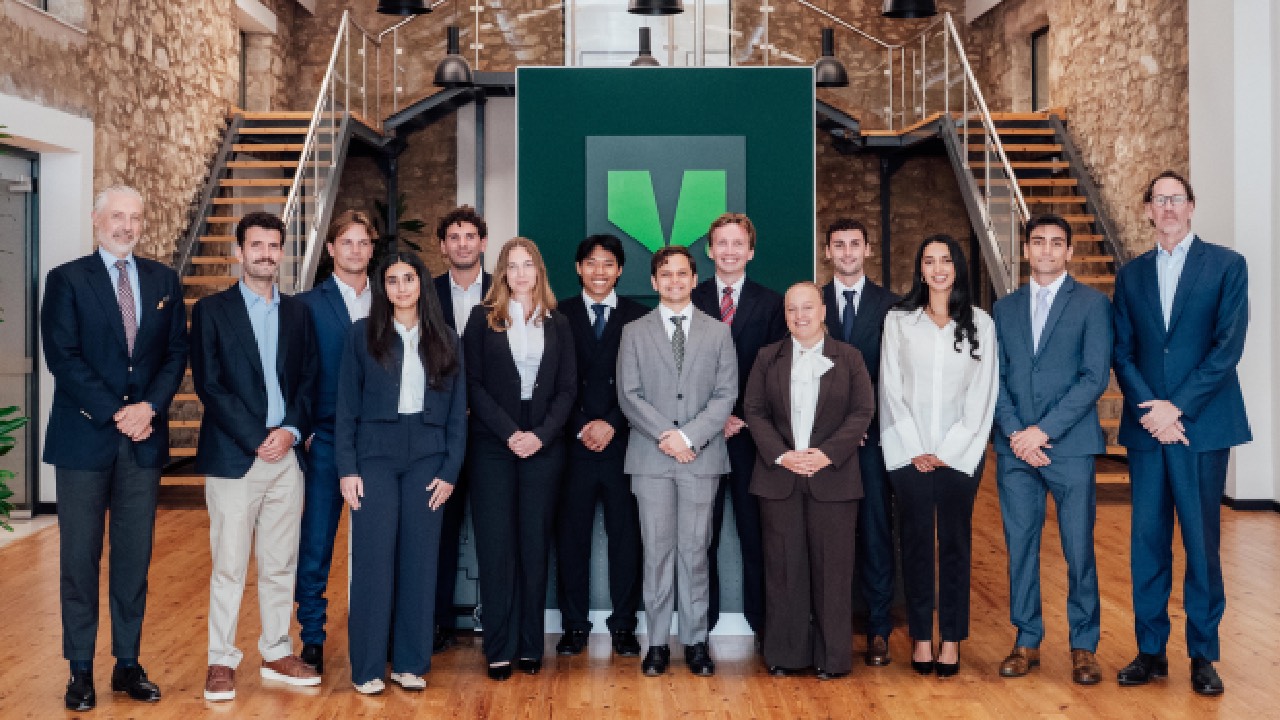
V. welcomes its new graduate cohort as programme expands across the group
Twelve graduates from nine nationalities join 11th year of V.’s expanded international management programme. V., the global ship manager and marine…
From Policy to Practice: Why Seafarers Are the Key to Maritime Excellence
The shipping industry is no stranger to regulation. Seafarers and ship operators work within a vast framework of international conventions, national…

Intermodal Report – Week 38 2026
Please find below the Intermodal market report for week 38 2026. Intermodal Report Week 38 2026 Market Insight By Nikos Tagoulis, Head of…

Allied – Weekly Market Review – Week 38
Please find below the Allied Weekly Report for Week 38 | 2026 ALLIED - Weekly Market Report- Week 38
Record year on the Northeast Passage but Arctic shipping remains very limited
In 2025, a record 103 transit voyages were made via the Northeast Passage. However, this is still equivalent to only around a day and a half of…

[xclusiv] S&P Report 21th September 2026
Please find below the [xclusiv] latest Weekly S&P Report [xclusiv] 2026_09_21 Market Commentary: VLCCs: Freight Boom Reprices the Fleet The VLCC…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
