Utility-scale renewable capacity additions set to pass 220 GW for the first time, but slowdown may be imminent

New utility-scale renewables capacity is set to break records in 2022, hitting an all-time high of 220 gigawatts globally with investments surpassing $300 billion for solar and wind combined, Rystad Energy research indicates. However, a slowdown of capacity additions could be around the corner as construction start-ups of large-scale projects are expected to stall.
Utility-scale renewable capacity additions are expected to increase by 38 GW in 2022 compared with last year, boosted by the array of government targets and policies announced in the wake of the COP26 climate summit in November. Annual investments in solar and wind additions will rise to more than $300 billion, up 20% compared to last year’s total of $240 billion. The annual growth is primarily driven by surging solar PV investments, which are set to rise by 18%, from $117 billion to $138 billion.
As a result, solar PV and wind dominate the expected capacity additions, contributing 85% of the 220 GW to be installed this year. The remaining 15% is split between pumped hydro, battery, solar thermal and storage. Although battery additions in 2022 will amount to only 12 GW, or 6% of total new renewable capacity, this represents a huge jump for the sector as worldwide battery installations are projected to reach a total of 24.6 GW by the end of 2022, a 96% increase over 2021 capacity. The hydrogen pipeline is also set for a large increase this year, with more than 400 megawatts (MW) of capacity additions, a 70% growth on last year.
Out of the 220 GW of renewable energy capacity expected to be installed this year, 195 GW, or 88%, is already under construction, with the remaining 12% in various development stages. Solar PV accounts for 46% of the total under-construction capacity, followed by onshore wind (34%). Almost 50% of the under-construction capacity is in Asia, mainly in China and India.
“Despite record capacity additions in 2022, the outlook is not all positive. Projects expected to start construction this year will face challenging economics, delays and even cancellation risks. For instance, rising steel prices are already having an impact on onshore wind projects, and utility-scale solar PV developers are concerned about surging commodity prices, signaling a potential downturn at least for the first half of the year,” says Gero Farruggio, head of renewables research with Rystad Energy.
The first sign of dark clouds on the horizon is the projected fall in large-scale renewable capacity breaking ground in 2022 versus 2021. A decrease in project start-ups is expected in 2022, mainly due to rising steel prices that have constrained onshore wind projects, as the cost of steel accounts for almost 70% of the final price of wind installations. The utility PV industry may also come under pressure, at least during the first half of the year, with developers keeping a close eye on commodity price spikes. However, increased polysilicon manufacturing capacity – projected to surpass 1 million tonnes per year in 2022 – will provide some respite to prices following a 300% spike in 2021.
Regional trends: China leads
Asia will account for 103 GW or 46% of the total new capacity added in 2022, followed by North America with 49 GW (22%). In Asia, most of the capacity additions will come from China, which is set to account for 64 GW – around 62% of the total Asian capacity gains and 29% of the total global capacity additions. Despite the fact that China phased out national subsidies for onshore wind and solar PV at the start of this year, plans for large-scale renewable energy projects continue to be announced in the country.
China also continues to be the leading developer of offshore wind, with over 14 GW of capacity added last year. While this year is expected to see only 11.5 GW added, 2022 will become the second consecutive year with capacity additions of more than 10 GW. China is expected to be the largest contributor to new capacity again in 2022, accounting for 40% of additions, followed by Europe and particularly the UK, which is forecast to add more than 3 GW of capacity.
Total worldwide battery installations are estimated to reach 24.6 GW by the end of the year, constituting a 96% increase compared to 2021. Forecasts show battery capacity will surge to 52.4 GW by 2025, representing a 42% compound annual growth rate (CAGR) from 2021 and four times higher than current levels. While all regions in the world are waking up to the benefits of battery storage, nowhere is this more apparent than in the US, where 53% of the world’s battery capacity will be located by 2025, totaling 28 GW.
Source: Rystad Energy



Related News.
Global study finds Cyprus ranks SEVENTH and set for $1.1 billion AI GDP boost
Cyprus beats India and New Zealand to come SEVENTH in major AI study – with potential €1.1 billion GDP boost and youth jobs opportunity Some 86% of…
Global shipping’s trillion dollar climate bill according to Zero Carbon Analytics
A new study by Zero Carbon Analytics finds that emissions from international shipping cost the global economy around USD 963 billion between 1990…
Keeping Children Safe Online at Sea Seafy® earns friendly WiFi Certification across 26 vessels
Seafy becomes Friendly WiFi’s first partner in the maritime sector, helping protect kids from harmful content online. Friendly WiFi is delighted…
ShipManager joins Star Information Systems to accelerate the maritime industry’s transition to cloud
CFARER, a DNV Company selects Star Information Systems as the longterm home for ShipManager and its cloud future Star Information Systems (Star)…
Seafarer experience must shape maritime technology, initial STEER Project report finds
New research finds technology can shift rather than remove risk as The Nautical Institute, with support from Lloyd’s Register Foundation, calls for…
New LR service targets cargo disruption when trade routes fail
New LR Advisory service helps ports, governments and logistics operators respond to disruption, protect critical cargo flows and strengthen trade…
DORIC WEEKLY INSIGHT 06 NOVEMBER 2026
Please find below the DORIC Market Insight for the week ending 06th November 2026. Weekly Report 06.11.2026
BIMCO Shipping Number of the Week
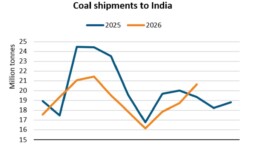
Coal shipments to India drop 7%, but limited recovery may lie ahead "Between January and October, coal shipments to India dropped 7% y/y due to the…
Hapag-Lloyd marks 20 years in South Africa and targets further growth
South Africa has become a cornerstone of Hapag-Lloyd's business in Africa Hapag-Lloyd surpasses 1 million TEU in Africa for the first time in its…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
