Intermodal Report – Week 46 2026
Please find below the Intermodal market report for week 46 2026.
Intermodal Report Week 46 2026
Market Insight
By Vasilis Fousekis, Research Analyst
This week’s spotlight is on the LPG carriers, as VLGC earnings are at exceptional levels. The trade is also now attracting capacity from the broader gas segment: the ACS SP Nereus, a 100k cbm VLEC, has loaded the first LPG cargo for its ship type at Houston. Rates on the US routes surpassed the record-high levels of September 2023 and the summer of 2026 this week, as fixture activity in the West held steady. Houston to Chiba is currently traded at about a TCE return of $184,600/day and Houston to Flushing at approximately $233,600/day TCE.
Behind these earnings lies the continued loss of Middle East supply. Hormuz has remained effectively under geopolitical uncertainty in November, with talks on a reopening yet to produce an agreement. Volumes remain below 50% of pre-war levels and Red Sea loadings remain exposed to further attacks. Long haul US cargoes, therefore, have become the main replacement for lost Middle East supply for Asian buyers, keeping the Baltic LPG index to 21k territory, above the Q3 average.
Vessel availability, rather than export capacity, had so far set the pace of US flows, which are crucial for the LPG trade. A constraint has since emerged on the supply side. Phillips 66, a US based company which operates the Freeport LPG export terminal in Texas, declared force majeure on butane loadings after a power outage and compressor failure incident in early November, lifting US butane prices and raising concern over prompt availability, although overall US LPG loadings have so far shown no clear slowdown. A prolonged outage would mainly tighten butane supply to Asian buyers, rather than reduce the number of cargoes available to fix.
In Asia, demand remains firm and at the same time price sensitive. Chinese imports rose by about 1m tonnes q-o-q in Q3, supported by positive margins at propane-to-propylene plants. India consumed 2.6m tonnes in October, approaching the monthly volumes seen before the Middle East conflict, while holiday-season inventory building may extend import strength into November and December. However, if spot prices of propane and butane remain elevated, further buying by Indian importers is likely to slow, especially without any state support.
On the supply side, the outlook is less comfortable, with 8 VLGCs delivered within Q3 and 3 more expected within Q4. About 170 VLGC and VLAC newbuildings, totalling 15.5m cbm, are due through 2030, equivalent to roughly 40% of the existing fleet. Contracting has continued at a strong pace, with 8.5m cbm of LPG carriers ordered in the first nine months and a further 14 large gas carriers signed in October. With the fleet averaging about 11.7 years, demolition is unlikely to offset much of this growth.
Looking ahead, long-haul US exports and Asian restocking should keep earnings well supported in the near term, despite periodic corrections. Seaborne volumes are expected to fall by around 12% this year, yet longer voyages should still lift tonne-miles by about 2.5%. High rates are also drawing marginal tonnage into the market, as the Nereus lifting shows, although such crossovers are likely to stay occasional, mainly when ethane employment is weak. The orderbook is a more significant source of new capacity. A potential settlement of the Hormuz crisis should support the rebound projected for 2027, but a possible recovery in Middle East exports would also shorten average voyages, just as deliveries accelerate in 2027 and 2028. The key question is whether US export growth can absorb that tonnage once trade routes normalize, with the timing of a settlement between Iran and the U.S. remaining the decisive factor.


Related News.
Greenland’s scrubber restrictions – Clean Shipping Alliance response
Greenland scrubber ban – reactive comment We are disappointed to see Greenland announce restrictions on exhaust gas cleaning systems (EGCS, or…
Trafigura signs long-term LNG supply agreement with Woodside Energy
Trafigura Pte Ltd, a global leader in the commodities industry, has signed a sale and purchase agreement with Woodside Energy Trading Singapore Pte…
Inventra by Seafy®, onboard retail that keeps sailing even offline
The new retail platform centralises the management of shops, boutiques and duty free, unifying catalogues, inventories and sales data across the…
Nova Marine Carriers acquires a 25% stake in Terminal Nord S.p.A.
Sider Navi S.r.l., the Italian sub-holding company of the international shipping group Nova Marine Carriers, based in Lugano, has acquired a 25%…
Shipping industry urges governments to agree on global GHG regulations to provide regulatory certainty and incentivize maritime decarbonization
In advance of the UN International Maritime Organization (IMO) Marine Environment Protection Committee (MEPC 85), which meets in London from 30…
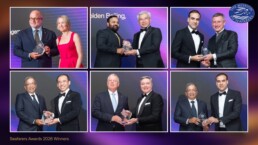
The Mission to Seafarers announces winners of 2026 Seafarers Awards
The Mission to Seafarers (MtS), a leading international seafarer welfare charity, is delighted to announce the winners of its 9th International…
NGOs Urge UN Shipping Body – including India – to adopt Crucial Climate Agreement before Year End
Ahead of an upcoming meeting of the International Maritime Organization’s (IMO) Marine Environment Protection Committee (MEPC 85, November…
Allied – Weekly Market Review – Week 46
Please find below the Allied Weekly Report for Week 46 | 2026 ALLIED - Weekly Market Report- Week 46
Gulf Earnings Fall, Atlantic rates retreat faster
In Week 46, freight weakness spread to Gulf routes, following a Week 45 correction that had primarily impacted the Atlantic (where Gulf VLCC…
Sallaum Logistics opens inland customs bonded compound in the Port of Limburg, Genk
The new site extends the Sallaum Terminal in Antwerp inland reachable by river, rail and road Sallaum Logistics is opening an inland customs bonded…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
