MABUX Bunker Outlook Week 25 2024

The Weekly Outlook was contributed by Marine Bunker Exchange (MABUX)
During Week 25, the MABUX global bunker indices continued their upward trend. The 380 HSFO index saw an increase of 5.90 USD, rising from 544.76 USD/MT to 550.15 USD/MT. The VLSFO index climbed by 3.62 USD, moving from 635.05 USD/MT to 638.67 USD/MT. The MGO index showed the most significant growth, adding 12.79 USD to reach 838.55 USD/MT, up from 825.76 USD/MT last week. As of the current update, the global bunker market maintains a moderate upward trend.
MABUX Global Scrubber Spread (SS) – the price difference between 380 HSFO and VLSFO – decreased slightly: minus $1.77 ($88.52 versus $90.29 last week). Despite this dip, the spread remains stably below the $100.00 mark (the SS Breakeven). Conversely, the average weekly value increased by $2.05. In Rotterdam, SS Spread increased for the first time in three weeks, adding $4.00 (from $60.00 last week to 64.00). The average weekly value at the port, however, decreased by $5.17. In Singapore, the difference in the price of 380 HSFO/VLSFO continued to widen: plus $11.00 ($86.00 versus $75.00 last week), gradually approaching the $100.00 threshhold. The weekly average at the port added $7.83. Overall, the SS Spread has stabilized at these levels and hints at an upward correction. We anticipate the SS Spread to trend upward next week. More information is available in the “Differentials” section of www.mabux.com.
As of June 11, the EU’s gas storage sites were 72.3% full. The refilling season has commenced, elevating gas storage levels from 58% at the end of winter—a record-high for that period, attributable to a milder winter and reduced industrial demand. Despite this, the pace of gas inventory build-up has been slower than usual, contributing to rising European gas prices. This increase in prices also reflects recent supply risks from Norway and Russia. Additionally, Asia’s competition for LNG supply has intensified due to severe heat waves in South and Southeast Asia, leading to a diversion of cargoes away from Europe. During Week 25, the European gas benchmark TTF showed a slight increase, adding 0.415 EUR/MWh (34.700 EUR/MWh versus 34.285 EUR/MWh last week.
The price of LNG as bunker fuel in the port of Sines (Portugal) began to rise again, reaching 834 USD/MT on June 17 (plus 41 USD compared to the previous week). At the same time, the difference in price between LNG and conventional fuel on June 17 showed a 20 USD advantage for MGO LS, contrasting with a 4 USD advantage for LNG the week before. On that day, MGO LS was quoted in the port of Sines at 814 USD/MT. More information is available in the LNG Bunkering section of www.mabux.com.
In Week 25, the MDI index (the correlation ratio of market bunker prices (MABUX MBP Index) vs. MABUX digital bunker benchmark (MABUX DBP Index)) indicated underpricing of all types of fuel segments in the four largest hubs: Rotterdam, Singapore, Fujairah and Houston:
In the 380 HSFO segment, weekly underprice averages rose by 4 points in Rotterdam, 12 points in Singapore, 18 points in Fujairah, and 11 points in Houston.
In the VLSFO segment, average weekly undervaluation levels showed an increase of 18 points in Rotterdam, 8 points in Singapore, 12 points in Fujairah, and 13 points in Houston.
In the MGO LS segment, weekly averages grew by 16 points in Rotterdam, 13 points in Singapore, 26 points in Fujairah, and 10 points in Houston. The MDI index in Singapore exceeded the $100 mark once again.
By the end of the week, the pattern of undervaluation in all selected ports remained unchanged. We expect the trend of fuel underpricing to persist into the next week. We expect the fuel underpricing trend to continue next week.
For more details on the correlation between market prices and the MABUX digital benchmark, visit the “Digital Bunker Prices” section on www.mabux.com.
Since October 2023, Integr8 Fuels has reported a significant shift in shipping routes, with many vessels now opting to navigate around Africa instead of using the Red Sea. This change has resulted in a notable increase in the demand for HSFO (High Sulphur Fuel Oil). Concurrently, ports along the African coast and nearby Spain have experienced a 30% rise in VLSFO (Very Low Sulphur Fuel Oil) sulphur off-specification incidents. The primary cause has been traced to contamination from barges also transporting HSFO. Currently, sulphur levels are the most common off-spec issue for VLSFO. Blending practices aim for a 0.50% sulphur limit, but straying too far from this target can affect shipowners’ profit margins. Over the past six months, there has been an observed increase in average sulphur content in VLSFOs in both the ARA (Amsterdam-Rotterdam-Antwerp) and Singapore regions. In Singapore, the likelihood of encountering VLSFO with a sulphur content of 0.51-0.53% has more than doubled in the past six months. Despite this, only 0.3% of VLSFOs in Singapore exceed the sulphur specification. In contrast, the ARA region has seen 2% of VLSFOs test off-spec for sulphur.
Source: MABUX



Related News.
Predicting the Future or Preparing for It? Cyprus Marine Club Explores the Power of Adaptability with Natasa Pilides
In a world where uncertainty has become the new normal, is predicting the future really the best strategy, or is the ability to adapt the greater…
Greece and Egypt in talks to extend EEZ Eastwards towards Cyprus following Libya’s move on Turkish Maritime Pact
Athens and Cairo have agreed to advance bilateral consultations aimed at extending the geographical scope of their 2020 Exclusive Economic Zone (EEZ)…
Seafarers face widening competency gap as digital shipping accelerates, recent research finds
Eighty two per cent of maritime professionals surveyed say current training does not adequately prepare crews for the realities of modern,…
Wärtsilä and WinGD sign new Service Framework Agreement to ensure long-term continuity and support for the global fleet
Technology groups Wärtsilä and WinGD have entered into a new long-term Service Framework Agreement, reaffirming their shared commitment to supporting…
Seatrium and Karpowership sign contract for a series of whale class Powership Conversion and Integration Projects
Seatrium and its strategic partner, floating power leader Karpowership, have strengthened their longstanding collaboration with the award of a…
ClassNK releases Handbook Supporting Consideration of Onboard Carbon Capture “Onboard Carbon Capture Systems Implementation Framework”
Bringing together technical, infrastructure, regulatory and emissions assessment considerations across the OCCS value chain - ClassNK has released a…
HHLA lowers earnings forecast for the 2026 financial year
Based on the business development to date and updated estimates for the fourth quarter of 2026, the Executive Board of Hamburger Hafen und…
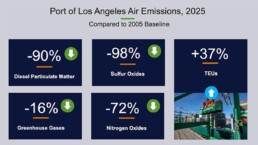
Port of Los Angeles reports lowest emissions per Container on Record
The Port of Los Angeles continued to make clean air gains in 2025, recording its lowest emissions per container on record, according to the Port's…
Drewry World Container Index – 22 Oct
WCI increased for the second consecutive week, the highest in 15 weeks. See detailed commentary below. Drewry World Container Index…
Mammoet, Port of Argentia and Argentia Capital Partner to Advance Floating Dry Dock and Marine Repair Facility
Partnership builds on Mammoet’s established presence at Port of Argentia and shared confidence in the growing market for ship repair and marine…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
