Oversupply of containers leading to second-hand container market price correction says a Container xChange analysis

The oversupply of containers is contributing to second-hand container market prices plummeting, Container xChange shared in a recent analysis.
“The current situation of oversupply of containers is a result of a series of reactionary market disruptions that began soon after the outbreak of the pandemic in early 2020. With the rise in demand, congestion at ports increased and the container capacity was held up for a considerably long period of time. This led to the panic ordering of new boxes at record levels. With time, as markets reopen and demand softens, the oversupply is a natural outcome of demand-supply forces balancing at new levels.” said Christian Roeloffs, Cofounder and CEO of Container xChange, a tech platform that simplifies the logistics of container movement.
“The oversupply situation does not come as a surprise because the average container prices and leasing rates have been declining globally since Sept-Oct 2021.” added Roeloffs.
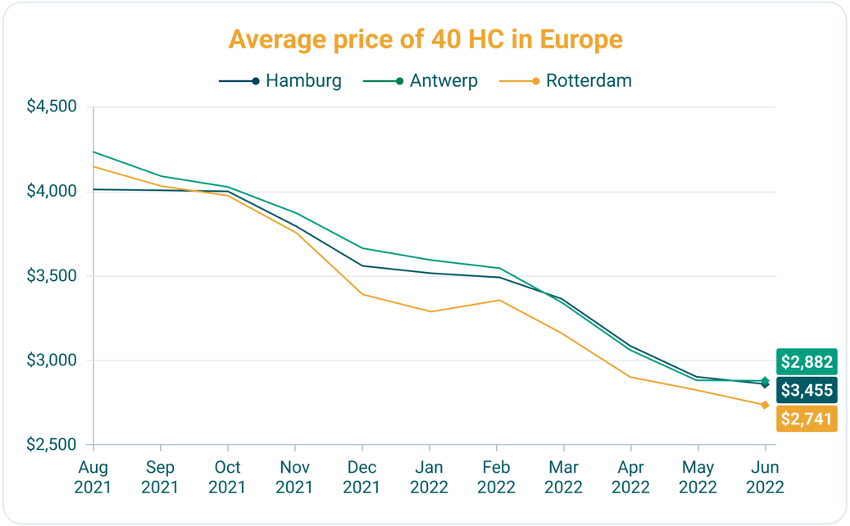
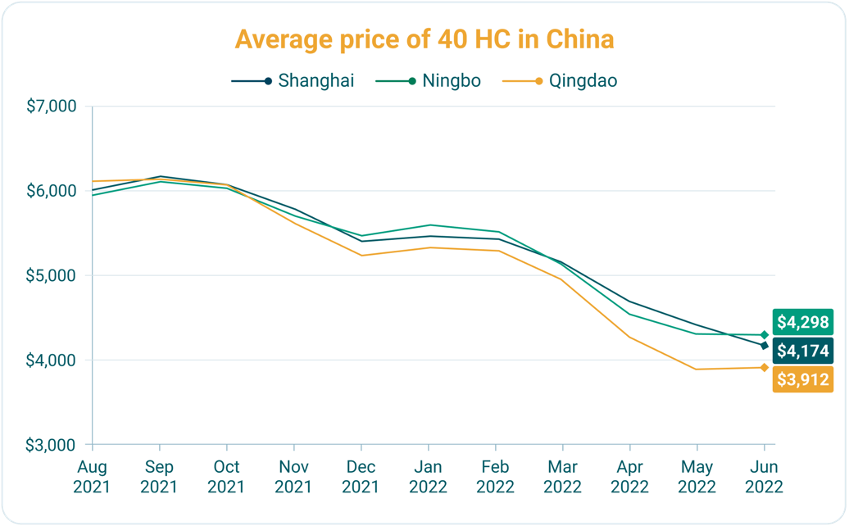
(More details on pricing and leasing rates, container availability fluctuations across China, India, Indian Subcontinent and the Middle East in the monthly container logistics report by Container xChange here – https://www.container-xchange.com/reports/monthly-container-logistics-update/ )
Short to mid-term outlook on freight rates, spot rates and container rates
Freight rates have come down by approximately an average of 20% since the beginning of the year 2022 and these will continue to slide gradually, but there will not be a massive decrease because the underlying disruptions in the supply chain are still there. Inflation, for one, has started to create build stress on the US economy and the EU. With inflation and pandemic-induced lockdowns, disruptions will continue to change the equation between supply, demand and prices. In the longer term, these will phase out and create a new normal balance of supply and demand.
Fresh data published by Drewry indicates an excess of 6 million TUEs of capacity in the global fleet of containers. Container xChange analysis further states that the oversupply will obviously lead to the requirement of more depot space which is already scarce. And in a scenario where we assume that the global supply chain disruptions will fade away with time, there will be higher box productivity and we will need fewer boxes per unit of cargo.
As we witness the easing of supply chain disruptions in the coming months it will lead to higher box productivity and a structural surplus of containers. If we also see further softening of demand, this will increase the supply of containers available for cargo.
There is a high possibility of a scenario where the equipment capacity will not get soaked.
“This situation will lead to tighter depot space, carriers will rush to get rid of their older equipment, second-hand container prices will continue to slide gradually only to reach a new normal level and the new market will dry up.”
The situation can be studied from the perspective of the market forces of demand and supply. If the demand for containers falls (resulting from the decline in consumer demand over the course of the next few months considering, the rising inflation which could contribute to negative consumer sentiment), then the supply of containers will naturally increase. Also, price is a function of demand and supply. If demand falls and supply increases, prices will fall. And that is what is currently happening with the container prices.
The shape of the Peak Season
We’ve said it before that the main factor that has driven up prices much more than the historical levels has been a supply-side crunch over the past two years because of lengthening turnaround times of containers caused by supply chain congestions. That still holds true. We still have about 10% of transport capacity tied up and removed from the value chain. Demand on the other hand has softened now.
U.S. Imports decreased by 2.4% between March and April. Purchases of goods went down USD 0.1 billion as higher imports of industrial supplies and materials (up 1.8 billion) were offset by lower imports of consumer goods (down 1.5 billion). source: U.S. Census Bureau
An interesting point is that in the long run, ocean freight demand is forecasted as a multiplier of global GDP growth. And if global GDP doesn’t plummet by for instance 5%, the global demand for shipping capacity will not significantly plummet.
“To sum up, we foresee a significant rise in the pent-up, peak season demand. This will likely keep container prices potentially stable (prevent them from falling further down or skyrocketing) in the short term as we inch closer to the peak season.”
“What remains to be seen is how the geopolitical circumstances and the pandemic-induced lockdowns (for instance, in China) play out in the coming months.”



Related News.
The Swedish Club marks official opening of New York office
The Swedish Club has officially opened its new office in New York City, marking an important step in the Club’s continued development across the…
Port of Long Beach breaks all-time cargo record in September
The Port of Long Beach achieved its busiest month in its 115-year history by moving nearly 1 million container units in September, a milestone fueled…
TD34 Forward Freight Agreement trades outpace TD3C in debut week as market seeks greater Gulf freight cover
The launch of the Forward Freight Agreement for the Baltic’s TD34 route by Intercontinental Exchange (ICE) has seen near-record volumes since its…
Black Sea Steel Flows Weaken as Shipping Risks Rise
Recorded Black Sea steel loadings declined sharply in Q3 2026. Volumes, including scrap, fell 65.6% y/y to 0.65 Mt across 51 voyages, compared with…
Fincantieri accelerates Robotics and Physical AI to Build the Shipyard of the Future
Fincantieri, a global leader in high-complexity shipbuilding, is accelerating the transformation of its shipyards through the integration of…
Advanced Navigation is bringing the World’s Most Complex Navigation Technology to Huntsville, Alabama
The race to deploy autonomous systems is exposing a critical constraint: production of the vital navigation technology required is not keeping pace…
GT Wings expands product range with launch of new lightweight AirWingTMS to reduce emissions for smaller vessels
GT Wings has announced the latest addition to its wind- assisted propulsion product range, AirWingTMS, a new compact and lightweight Jet Sail…
LD Armateurs’ world’s largest wind-propelled cargo vessel fitted with Norsepower Rotor sails™
LD Armateurs and Norsepower are proud to announce the completed installation of six Norsepower Rotor Sails™ on board Spirit of Toulouse, the lead…
DEME wins contract for wind turbine installation at the Zeevonk Offshore wind farm
DEME has signed a sizable1 contract for the transportation and installation of 69 wind turbines at the Zeevonk offshore wind farm in the…
MOL Group inaugurated its first biomethane plant in Szarvas
MOL Group has inaugurated its first biomethane plant in Szarvas. As a result of the investment of more than HUF 2.7 billion, the facility can now…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
