Intermodal Weekly Market Report for week 46 2020

Please find below the Intermodal market report for week 46 2020.
Intermodal Report Week 46 2020
Market insight
By George Kallianiotis
Valuation Department
As we are moving towards the end of the year, the overall deal landscape of the dry bulk sector corresponding to the second half of 2020 (up to date), offers a further analysis when it comes to comparison with the first. Specifically, the table below illustrates that the S&P activity during the second half of 2020 has been significantly increased by 38% as to the first, with almost one and a half months remaining for further developments.
Approximately 35% of the SnP deals during this period took place within October, whilst July and September accounted for an equal and approximate 20% of the overall deal realm. As anticipated, the lowest activity levels have been detected during August with only 12% of the reported deals being occurred at that time. However, November comes with a downturn in the S&P activity which constituted 9% of the reported transactions up to date while we expect – under normal circumstances this proportion not to exceed the volume of October but it will be in similar levels to July and September.
Handysize and Supramax vessels remain best sellers totalling 56% of the reported sales. The already significant amount of Handysize sales increased by 10% compared to the first half while Supramax sales increased by 37%. It is worth mentioning that the sales corresponding to all the other segments have increased by excessive rates, with the exception of Panamax vessels whose S&P activity has dropped by 15%. Finally, 53% of all confirmed sales are related to Greek and Chinese buyers; 36% and 17% respectively.
Greek buyers were – as usual – involved in acquisitions across all segments and ages and they were responsible for 64%, 72%, and 42% of the Panamax, Kamsarmax, and Capesize vessels, respectively. However, they were mostly after 10-year-old vessels especially in the Handysize and the Supramax segment. Chinese buyers were behind many sales of 10-year-old Supramax, vintage Panamax, and modern Kamsarmax tonnage. The remaining S&P realm was filled by various Far and Middle Eastern buyers with the latter possessing a significant amount of purchases in the Ultramax tonnage.
Nevertheless, the spread of COVID-19 strained the S&P activity with crew changes in the usual delivery ports being ineffective thus despite the significant increase – in terms of deals during the last months, we anticipate that the overall secondhand transactions that will occur during 2020 will be at lower levels comparing to the last years similar to 2015.
Chartering (Wet: Soft- / Dry: Soft-)
The Dry bulk index moved further south, with Capesize performance paving the way for this downward trajectory. Panamax and Handysize segment proved to be more resistant positionally while Supramax rates subdued to pressure last week. The BDI (17/11/2020) closed at 1,112 points, up by 1 point compared to Monday’s (16/11/2020) levels and decreased by 88 points when compared to previous Tuesday’s closing (10/11/2020). A mixed picture emerged in the crude carrier market, with VLCC earnings losing further ground while the rest of the sizes witnessed a surge. Nevertheless, average T/C earnings for all sectors are still hovering below OPEX levels. The BDTI (17/11/2020) closed at 432, an increase of 27 points, and the BCTI at 345, an increase of 19 point compared to previous Tuesday’s (10/11/2020) levels.
Sale & Purchase (Wet: Stable+ / Dry: Firm+)
Bulkers continue to dominate the SnP market with the Kamsarmax and Supramax sectors gathering most of the interest. Action on the Tanker SnP front has slowed down last week. In the tanker sector, we had the sale of the “SRI VISHNU” (152,923dwt-blt ‘00, S. Korea), which was sold to undisclosed buyers, for a price in the region of $11.5m. On the dry bulker side sector, we had the sale of the “APOLLO” (77,326dwt-blt ‘06, Japan), which was sold to Chinese buyers, for a price in the region of $9.3m.
Newbuilding (Wet: Stable+ / Dry: Stable+)
A good number of newbuilding orders was observed with large size units made the headlines in the list of recently reported deals. On the dry bulk side, the number of the Capesize vessel that has been ordered last week could give us the impression of a strong freight market; while rates in the respective sector are on a downward trend, the revived love for big bulkers could reflect an optimism among owners regarding the future of the dry bulk market. At the same time, the appetite for newbuilding Container vessels remains strong with another order, which consists of six large boxship units, being materialized the past days. A far as the asset values are concerned, it seems that prices for newbuilding units remain steady for the time being despite the negative outlook that both the dry bulk and tanker markets have displayed recently.
Demolition (Wet: Stable+ / Dry: Stable+)
The demolition market continues to see high level of bids during the past week. Indian Sub-Continent breakers appear to be fairly strong with high price offering close to 400$/ldt levels. As always Pakistani cash buyers lead in bids with improved steel prices providing support to their voracious appetite for fresh tonnage. Bangladeshi breakers are still trying to figure out how the price settler Cartel will affect their profits which is in fact the main reason behind the continuing decline of their market share. India remains the best demo destination for HKC units. However, as it will be on holiday (Diwali festival) for the coming week, it will be interesting to see how that will affect prices offered by its main counterparts. Lastly, positive fundamentals in Turkey (Turkish Lira enjoyed an upward momentum during the previous week while steel prices increased as well) helped local breakers to improve their bids after weeks of steady levels. Average prices in the different markets this week for tankers ranged between 215-370/ldt and those for dry bulk units between $205-355/ldt.


Related News.
Global Flag State Ranking 2026 who is up, who is down
Lorrendraaier publishes Global Flag State Ranking 2026: 148 flags measured on objective data, Singapore leads, Pakistan falls 35 places, the Dutch…
Will Germany have enough gas this winter?
As of mid-September 2026, Germany had stored just about 141 terawatt-hours of gas, accounting for around 57% of the country’s total storage…

Record diesel prices put US policy options in focus
Record-high diesel prices and tight inventories have put US exports under scrutiny, but keeping more barrels at home may offer only temporary…
IUMI elects Sean M. Dalton as President and says farewell to Frédéric Denèfle
The International Union of Marine Insurance (IUMI) has elected Sean M. Dalton as its new President. The election took place today at a meeting of the…
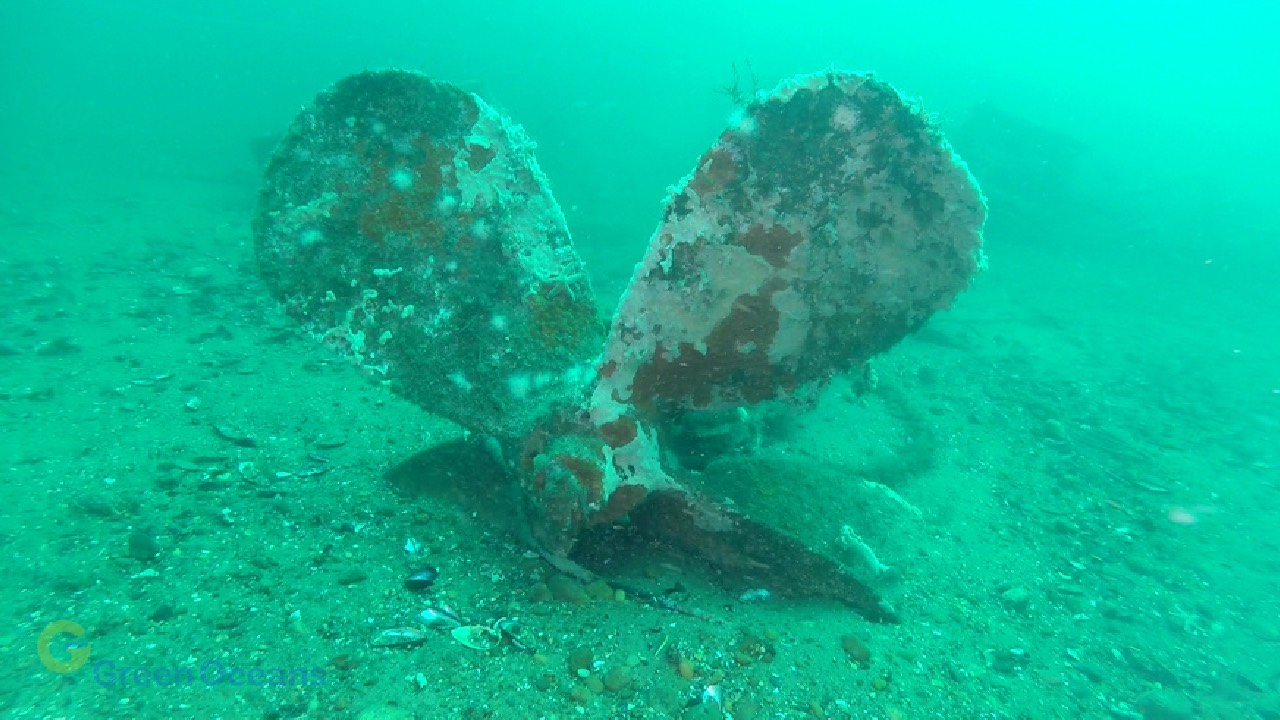
F/V MISTRESS Shipwreck ‘Lost’ Near Block Island Located After Seven Years
Green Oceans’ Underwater Investigation Reveals a Shipwreck Presumed to be the F/V Mistress found at the Base of Block Island Turbine #1 - Asks…
OCEAN at 50 celebrating a proud past and Maritime Future
OCEAN, the European sub-committee of ISSA, celebrated half a century of service to Europe’s ship supply sector with a landmark anniversary conference…

DORIC MONTHLY BRAZIL BAROMETER SEPTEMBER 2026
Pls find below the DORIC MONTHLY - BRAZIL BAROMETER SEPTEMBER 2026 BRAZIL_BAROMETER_SEPTEMBER_2026

Steel flows face fresh challenges in the final quarter of 2026
Steel flows slip into negative growth in July 2026 Global steel flows fall 1% y/y in July 2026 to reach 22.2 Mt. China’s share of global steel…

Insurance must shift “from repair to prevention”, says IUMI
Marine insurers will need to place greater emphasis on loss prevention as risks become more complex and costly to insure, according to Pascal Dubois,…

BIMCO’s Container Shipping Market Overview & Outlook September 2026 is out
Container Shipping Market Overview & Outlook Supply pressure is mounting "Disruptions and strong growth in head-haul trades continue to support…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
