Intermodal Weekly Market Report for week 44 2020

Please find below the Intermodal market report for week 44 2020.
Intermodal Report Week 44 2020
Market insight
By Ilias M. Lalaounis
SnP Broker
As the end of the year approaches, one would definitely notice that the newbuilding orderbook for bulk carriers is significantly smaller compared to the levels of the same period last year; a year where newbuilding orders were also down compared to the year before.
Starting with the Handysize sector, a total number of 109 units are on order compared to the 127 units for the same period last year (5% vs 4% today in terms of orderbook to fleet ratio). In the Supra-Ultra segment, 233 ships were on order last year vs 188 units until today (5% of the fleet today vs 7% the year before). Moreover, regarding Panamax-Kamsarmax front is concerned, from a total orderbook of 193 ships last year, the current one now consists of 121 ships (9% vs 5% today). Finally, the orderbook of Capes/Newcastlemax stands today at 126 units vs 201 ships during the same period last year (7% and 12% of the existing fleet respectively).
Although the slow newbuilding contracting activity is evident and welcomed by all dry bulk ship owners, it is very interesting to undergo a more detailed research of the reasons that led to the above slump of orders. Initially, the fresh capital that used to come from investors, who are not directly related to the shipping industry, has dried up. With returns falling below expectations or being negative, the appetite for participation in newbuilding projects has gradually decreased.
Another reason is the absence of a breakthrough technology that would bring a meaningful improvement in new building designs, which are pretty much the same during the past 5 years. Notwithstanding that the most important “known- unknown” is still the next modus of propulsion. As a result, the shipping industry’s “divided” view on the commercial and long-term implementation feasibility of ESG in maritime transportation remains present, with shipping participants unable to reach a consensus on what type of fuel will the next generation ships use. Hence several owners adopt a “wait and see” approach while monitoring the new developments in the sector.
In addition to the above, another important reason why newbuilding orders are low, is definitely the low price of 5-yrs old ships compared to newbuilding prices. Ship builders are more inelastic on prices compared to the prices of modern second hand units which in today’s dynamic SnP market fluctuate in line with the freight market that has been extremely volatile over the past two years. Consequently, a significant amount of SnP transactions of modern ships have materialized. Specifically, 44 ships less or equal to 5-yrs old have been sold during 2019 and 44 in 2020 so far with prices mainly trading at a discount over newbuilding prices, which is as a disincentive for owners to order new ships.
All in all, bearing in mind all the above and in combination with the current low fleet-orderbook ratio, it seems that dry bulk owners should stop worrying about the supply of new ships, and focus on how many ships exit the market for recycling. That being said, an increase in scrapping activity will definitely boost freight rates further, and a bull market might be just around the corner.
Chartering (Wet: Soft- / Dry: Soft-)
With the exception of Panamax rates that have only managed to move positively, earnings for the rest of the sizes in the dry bulk market remained on a downward path during the last week. The BDI today (03/11/2020) closed at 1263 points, down by 21 points compared to Monday’s (02/11/2020) levels and decreased by 150 points when compared to previous Tuesday’s closing (27/10/2020). The negative sentiment in the crude carrier market was evident for yet another week, with VLCC sector underperformed the rest of its counterparts. The BDTI today (03/11/2020) closed at 405, decreased by 21 points and the BCTI at 313, a decrease of 17 point compared to previous Tuesday’s (20/10/2020) levels.
Sale & Purchase (Wet: Stable – / Dry: Firm+)
SnP activity sustained its dry bulk volume last week, with owners showing increased appetite across the geared candidates, while a healthy number of Container secondhand sales materialized as well. In the tanker sector, we had the sale of the “SKOPELOS” (319,360dwt-blt ‘02, S. Korea), which was sold to Malaysian buyers, for a price in the region of $25.0m. On the dry bulker side sector, we had the sale of the “CSSC WAN MEI” (176,460dwt-blt ‘12, China), which was sold to Singaporean owner, Berge Bulk, for a price in the region of low $18.3m.
Newbuilding (Wet: Firm+ / Dry: Soft-)
In the newbuilding front, appetite for tanker vessels seems to be growing, with a pair of VLCC, Suezmax and Aframax units being ordered during the previous week. Sentiment continues to be weak in the newbuilding dry bulk market as contracting activity remains at very low levels. The uncertain atmosphere that surrounds the dry bulk freight market has pushed owners to the side-lines as far as the newbuilding front is concerned; however, we are witnessing a very busy secondhand activity with owners willing to exploit the relatively low secondhand asset values. At the same time, increased competition among shipbuilding yards has resulted at reduced newbuilding prices with current ships being offered by shipbuilding players at discounts prices compared to the average levels of the past two years.
Demolition (Wet: Stable+ / Dry: Stable+)
Cash buyers in the Indian subcontinent demolition market are still offering scrap prices at high levels. The number of units coming up as demo candidates is admittedly lower compared to the previous weeks; as a result, breakers have maintained their bids at the improved levels that we are witnessing during the past weeks despite the negative fundamentals that prevail in the market. Pakistan remains the most lucrative destination with breakers in the region offering the highest market premia. In Bangladesh, breakers seem unable to compete with their subcontinent counterparts; the cartel has not managed to provide any meaningful profit with a very low number of units destined for recycling in the region. India market is struggling due to the lack of positive fundamentals; both local currency and steel prices followed a downward path during the previous week; however, a coetaneous decrease in tonnage supply have increased offered scrap prices especially for HKC units. On the Turkish front, an overall steady sentiment was observed with scrap prices remaining constant with the TYR (which now trade close to 8.5 TRY/USD) adding further pressure to local cash buyers. Average prices in the different markets this week for tankers ranged between 210-370/ldt and those for dry bulk units between $200-355/ldt.


Related News.
Global Flag State Ranking 2026 who is up, who is down
Lorrendraaier publishes Global Flag State Ranking 2026: 148 flags measured on objective data, Singapore leads, Pakistan falls 35 places, the Dutch…
Will Germany have enough gas this winter?
As of mid-September 2026, Germany had stored just about 141 terawatt-hours of gas, accounting for around 57% of the country’s total storage…

Record diesel prices put US policy options in focus
Record-high diesel prices and tight inventories have put US exports under scrutiny, but keeping more barrels at home may offer only temporary…
IUMI elects Sean M. Dalton as President and says farewell to Frédéric Denèfle
The International Union of Marine Insurance (IUMI) has elected Sean M. Dalton as its new President. The election took place today at a meeting of the…
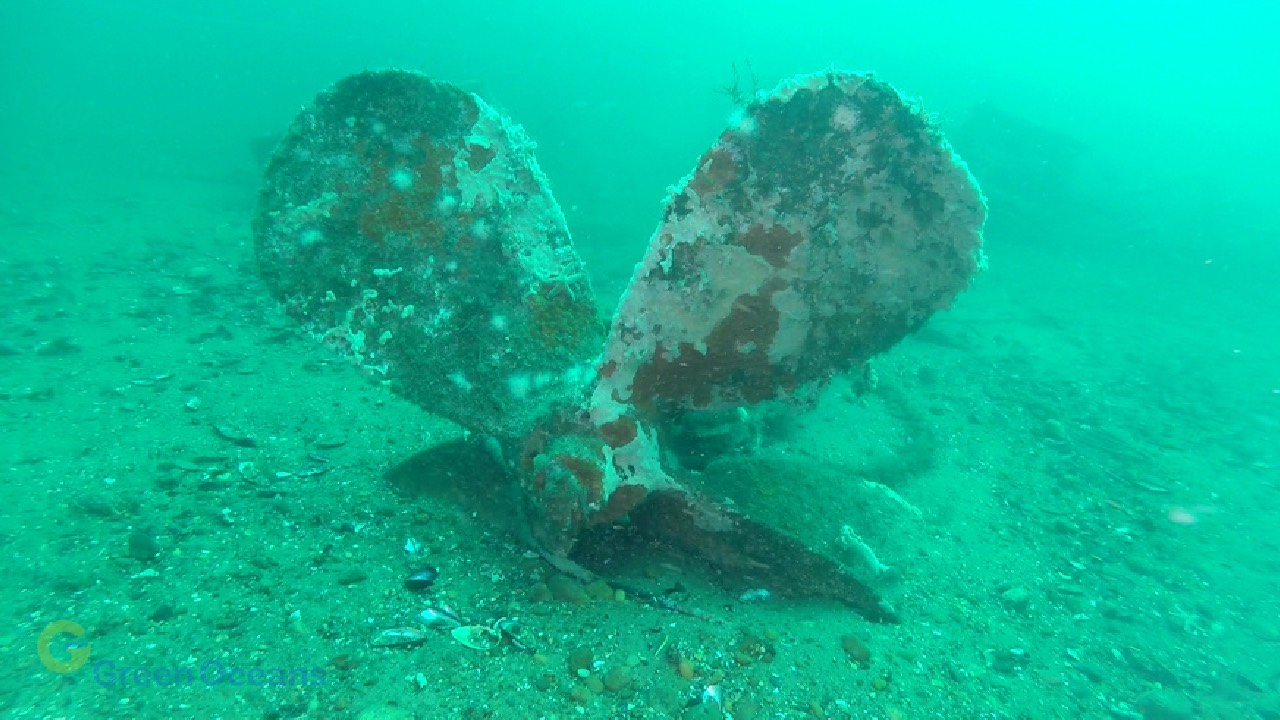
F/V MISTRESS Shipwreck ‘Lost’ Near Block Island Located After Seven Years
Green Oceans’ Underwater Investigation Reveals a Shipwreck Presumed to be the F/V Mistress found at the Base of Block Island Turbine #1 - Asks…
OCEAN at 50 celebrating a proud past and Maritime Future
OCEAN, the European sub-committee of ISSA, celebrated half a century of service to Europe’s ship supply sector with a landmark anniversary conference…

DORIC MONTHLY BRAZIL BAROMETER SEPTEMBER 2026
Pls find below the DORIC MONTHLY - BRAZIL BAROMETER SEPTEMBER 2026 BRAZIL_BAROMETER_SEPTEMBER_2026

Steel flows face fresh challenges in the final quarter of 2026
Steel flows slip into negative growth in July 2026 Global steel flows fall 1% y/y in July 2026 to reach 22.2 Mt. China’s share of global steel…

Insurance must shift “from repair to prevention”, says IUMI
Marine insurers will need to place greater emphasis on loss prevention as risks become more complex and costly to insure, according to Pascal Dubois,…

BIMCO’s Container Shipping Market Overview & Outlook September 2026 is out
Container Shipping Market Overview & Outlook Supply pressure is mounting "Disruptions and strong growth in head-haul trades continue to support…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
