Crude Tanker Rates Reach Record Levels


Clarksons Research, the data and intelligence arm of the Clarksons Group, have reported all-time highs for crude transportation costs following further disruption in the Middle East Gulf region.
Reviewing the all-time high rates for crude tankers, Steve Gordon, Global Head of Clarksons Research, commented:
- Crude tanker rates hit all-time highs on Friday 12th September, supported by improved export volumes and heightened disruption as shipping markets continue to provide the logistical flexibility needed to deliver oil “to market”.
- Global average Very Large Crude Carrier (VLCC) earnings rose by 68% w-o-w to a fresh high of $451,000/day.
- Record VLCC rates in the West (USG-China freight: $37.5m, $19/bbl) and East (Oman–Korea: $572,000/day).
- Our cross-sector ClarkSea Index is up 91% y-o-y to $56,567/day, the highest level on record, supported by the crude tanker market surge and with rates in containers, bulkers, LPG and car carriers also at, or close to, multi-year highs.
Middle East Update …
Developments in the Middle East have again been hugely volatile this week, with an escalation in vessel attacks, oil prices pushing through $100/bbl (despite good crude flows departing the Gulf region) and now building geo-political risk in the Red Sea. Tanker markets continue to sit at hugely elevated levels, with the disruption helping VLCC rates surge further to fresh record highs
Attacks & Transits …
In an escalation in tensions this week, a further 8 ships were reported damaged in the Gulf (bringing total ships reported damaged / arrested to >100). “Visible” (AIS-on) transits via Hormuz remain highly limited but the good flow of VLCCs “shuttling” crude through Hormuz for STS transfer in the Gulf of Oman seems to be continuing for now. Other ship types / commodities seem more constrained (the first LNG carrier left the Gulf in nearly a month this week, 2 VLGCs crossed Hormuz “visibly” this week vs 33 typically). Red Sea traffic also remains disrupted, with Yemen’s Houthi group seizing cities close to the Bab-El-Mandeb. The disruption focus here is VLCC traffic through the Bab-El-Mandeb, now 80% below Q2 (and attacks on Saudi’s East-West pipeline are still a risk). Houthi advances may also threaten the revival in container Gulf of Aden transits (now >2x Q2, if 59% below the 2023 “normal”).
Energy Markets…
Despite major disruption, energy markets, supported by the logistical flexibility shipping markets provide, continue to show resilience in getting oil “to market”. We estimate ~8m bpd of crude is now passing via Hormuz (down “only” 7m bpd vs pre-conflict), alongside 2.5m bpd from Fujairah / Oman pipeline (+0.5m bpd) and 3m bpd from Yanbu (+2m bpd) boosting overall Middle Eastern crude outflows to 13.5m bpd (18m bpd pre-conflict). An extra ~0.75m bpd of underlying export growth (e.g. from Brazil) has supported (albeit US Gulf exports are down on their May peak). However, while a drop in Chinese imports (which were running 3-4m bpd below pre-conflict in Q2) kept oil prices “in check” for much of the summer, Chinese demand now seems to be firming, and alongside increased attacks and indications from the US administration that the conflict may be more prolonged, Brent has risen to $104/bbl. With Atlantic diesel prices at record highs, macro-economic indicators (e.g. upcoming central bank rate meetings, inflation rising, US 10-year treasuries at ~5%) need careful review.
Shipping Markets ….
The crude tanker market is again at extraordinary rate levels. The combination of both “enough” volume (Mid. East crude flows are “only” 4.5m bpd down) and major inefficiencies as the tanker market provides the logistical flexibility needed has developed. With voyages lengthening further (e.g. ~50% of Red Sea oil now heading to Asia via the SUMED pipeline (or Suez) and then the Cape of Good Hope to bypass the Houthi threat) and inefficiencies related to STS transfers building (e.g. ~15% of the VLCC fleet is now off Oman, start-July: 10%), global VLCC earnings rose by 68% to a fresh high of $451,000/day amid records in the West (USG-China freight: $37.5m, $19/bbl) and East (Oman–Korea: $572,000/day). Gains have filtered down through the sizes, with global Suezmax earnings up 94% w-o-w to a record $343,000/day. Across other energy shipping segments, VLGC rates remain elevated at $163,000/day amid continued disruption at Panama (5% of VLGC fleet waiting to transit Panama earlier this week, 2% in August), but LNG carrier spot rates are now soft ($27,000/day) with more US LNG being shipped shorter-haul to Europe (stocks are at a >10-yr seasonal low). So, with energy markets increasingly factoring in a prolonged conflict and while building macro-economic risks need close attention, for now crude tanker markets seem to be benefiting from an economic “sweet spot” of “just enough” volume and plenty of disruption (see SIN for full weekly recap).
Our best wishes to anyone who has been directly impacted by the conflict.
Further context on the crude tanker market is below and attached :


Related News.
CSN London Maritime Forum “Shipping: Predicting an Unpredictable Future”, 13 October – Save the Date
“Shipping: Predicting an Unpredictable Future” Date: 13 September 2026 Time: 09:00-16:00 Venue: Marriott Hotel Regent's Park Following the…
Cyprus Shipping Chamber continues 30 year Charity Tradition through its Beach Volley Tournament
The Cyprus Shipping Chamber (CSC) successfully organised, once again, its annual Charity Beach Volley Tournament, which took place on 5, 6 and 13…
Connecting Cyprus to the World: The Strategic Partnership Between the Cyprus Chamber of Commerce and Industry and the Cyprus Diaspora Forum
A shared vision transforming diaspora engagement into economic opportunity When the Cyprus Diaspora Forum was established in 2024, its ambition was…
Safe navigation and crew preparedness for operations in polar waters
Operations in the Arctic and Antarctic regions present unique navigational, operational, and environmental challenges that require thorough…
Global coal demand set to increase this year amid Middle East conflict
The IEA Mid-Year Update sees higher natural gas prices spurring a shift towards coal in some regions in 2026, with the Strait of Hormuz situation…
Mental Health Support Solutions calls for mandatory mental-health training for senior officers to help reduce suicide risk
Mental Health Support Solutions (MHSS), part of OneCare Group, is calling on shipping companies to prioritise mental health and suicide prevention…
VIKAND launches VIPHARMA to strengthen global maritime medical supply chain
VIKAND, a global leader in maritime healthcare, today announces the launch of VIPHARMA, a new subsidiary providing global medical and pharmaceutical…
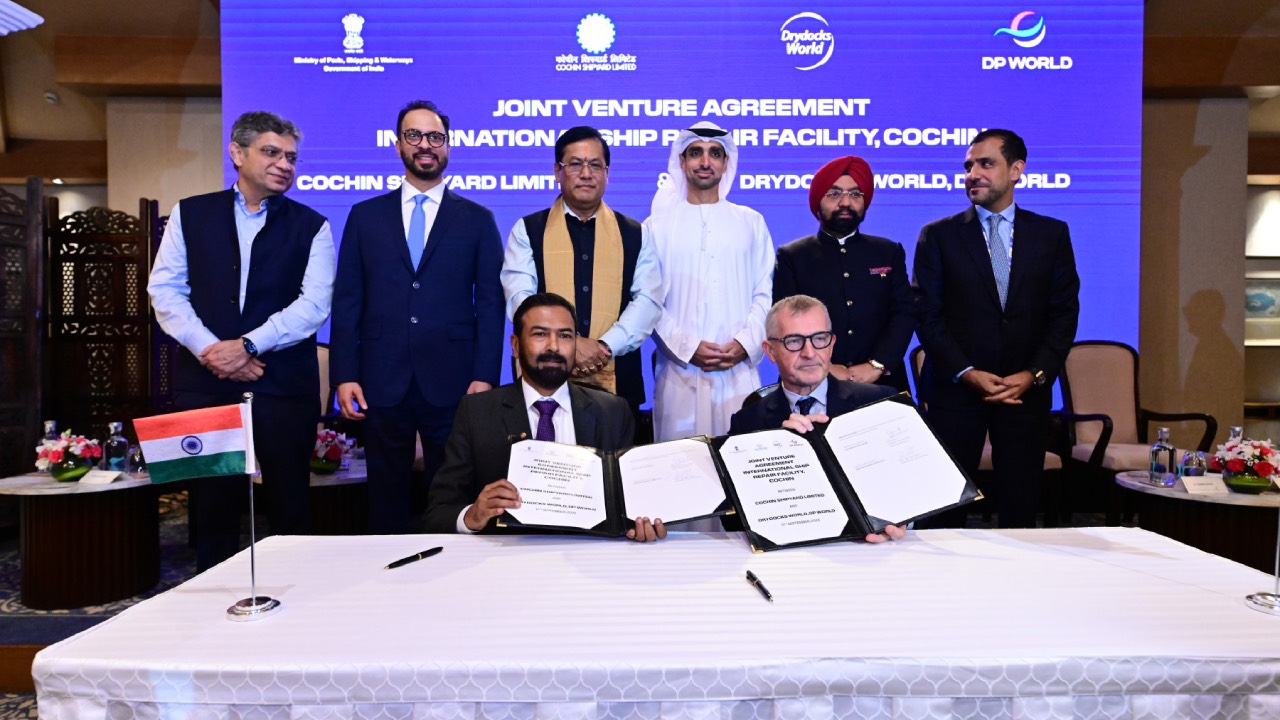
Drydocks World and Cochin Shipyard form joint venture strengthen India’s ship repair industry
Drydocks World, a DP World company, and Cochin Shipyard Limited announced the signing of a joint venture agreement to operate and expand the…
USPS Salutes the U.S. Coast Guard Academy’s 150 Years
The stamp celebrates all the cadets whose dedication embodies the Coast Guard motto: Semper Paratus (Always Ready) The Postal Service continues its…

Getting to Zero Coalition calls on IMO Member States to secure an investable Net-Zero Framework
The Getting to Zero Coalition welcomes continued efforts to find common ground on a global framework for shipping’s energy transition, following the…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
