Dry Bulk Market: Capesize Market Softening


Capesize
The market closed the week on a softer footing, with the BCI 182 5TC easing from just under $50,000 at the start of the week to $44,374, reflecting a clear loss of momentum as the week progressed. Trading conditions were characterised by persistently thin liquidity, disrupted participation due to Posidonia, and generally subdued miner engagement, which together left the market vulnerable to downside pressure. In the Pacific, sentiment weakened steadily as the week unfolded, with a gradual erosion in C5 levels driven by limited cargo emergence and a lack of consistent support from major miners. Fixtures progressively printed lower, from mid-to-high $15 early in the week to a tick below $14 by the close. The South Brazil and West Africa to China market followed a similar, albeit more gradual, weakening trend, with index dates on C3 drifting lower and spreads widening before settling into the low-to-mid $36s range on later stems. The North Atlantic initially showed relative resilience, briefly supported by short-duration TA activity, but this strength faded as the week progressed and sentiment softened in line with the broader market. Fronthaul activity remained notably quiet throughout.
Panamax-Kamsarmax
The week opened on a subdued note, influenced by regional holidays and Posidonia, with limited activity prompting many participants to reassess positions. Despite an early P5TC uptick, sentiment quickly softened as the week progressed. In the Atlantic a growing tonnage list, particularly in the North Continent, combined with relatively limited mineral and grain cargoes, placed downward pressure on rates. Owners gradually revised expectations lower, especially for prompt positions, while fronthaul activity remained muted. Pacific trade provided some initial support, driven by steady Indonesian and Australian exports, though sentiment became mixed midweek as bid levels weakened. While owners resisted significant rate declines, this resulted in a widening bid-offer gap and limited fixtures. As the week progressed, broader negative momentum set in across both basins, with softer East Coast South America demand and continued Pacific easing. Overall, declining indices reflected persistent oversupply and subdued enquiry, leaving the market on a cautious footing heading into the following week.
Ultramax/Supramax
This week’s Supramax/Ultramax market developed gradually after a subdued start, with Posidonia events in Athens and a holiday in Singapore limiting early momentum. Overall sentiment improved modestly as the week progressed, particularly in the Atlantic, where the US Gulf remained the key source of support. Brokers continued to report firmer rate ideas from the Gulf and steady underlying activity in the South Atlantic, although much of the fixing remained undisclosed. The Continent-Mediterranean market stayed broadly balanced. In Asia, conditions were initially mixed, with stronger demand in the north offset by pressure in the south due to prompt tonnage, but sentiment improved later in the week as fresh enquiry returned. Notable fixtures included coal and grain business in both basins, alongside limited short-period interest. By week’s end, the 11TC average had edged up from $19,847 to $20,067, reflecting a firmer but still cautious overall market tone.
Handysize
This week, the Handysize market remained broadly subdued, though signs of gradual improvement were evident beneath the surface. Activity across the Atlantic basin was generally limited, as Posidonia and other industry events kept many participants away from their desks, leaving the Continent and Mediterranean largely positional while the South Atlantic remained under pressure from ample tonnage and muted fresh demand. A 36,000-dwt vessel was fixed for a trip from Upriver to Venezuela at around $20,850. The US Gulf, however, maintained a slightly firmer tone, supported by tightening supply and renewed enquiry, with a 35,000-dwt vessel heard fixed for a trip from the US East Coast to ARAG with coal at $20,000. In Asia, sentiment remained comparatively more supportive throughout the week, underpinned by steady demand and tightening tonnage in parts of the region, with rates gradually trending upward. A 43,000-dwt vessel open in Chiba on 3/6 June was fixed via North Australia to China-Japan at $19,000.
Source: Baltic Exchange



Related News.

Allied – Weekly Market Review – Week 38
Please find below the Allied Weekly Report for Week 38 | 2026 ALLIED - Weekly Market Report- Week 38

Record year on the Northeast Passage but Arctic shipping remains very limited
In 2025, a record 103 transit voyages were made via the Northeast Passage. However, this is still equivalent to only around a day and a half of…

[xclusiv] S&P Report 21th September 2026
Please find below the [xclusiv] latest Weekly S&P Report [xclusiv] 2026_09_21 Market Commentary: VLCCs: Freight Boom Reprices the Fleet The VLCC…

Grain in Focus US Soybean Sailings to China recover through September
Grain in Focus - US Soybean Sailings to China Recover Through September US soybean sailings to China recovered in September, following the subdued…

Marine cargo insurance market continues to soften, reports IUMI
2025 global marine cargo insurance premium indicates that the cargo market softened in that year despite continued growth in the overall premium…
Navigator Gas Returns to PrimeServ for New Ethane Retrofits
Eight years of proven service prompt upgrading of two further vessels using Everllence’s trusted retrofit platform Everllence PrimeServ –…
LR study points to 200,000m³ LNG carriers as viable next step for global LNG fleet renewal
New analysis finds larger LNG carriers could deliver greater transport efficiency while retaining access to most key LNG terminals worldwide. Lloyd’s…
Ocean hull market faces growing risk pressures despite global premium growth, reports IUMI
The global ocean hull insurance market is continuing to soften despite apparent growth in the overall premium base, according to Ilias P.Tsakiris,…
Saildrone USVs Receive Danish Flag Registration for European Operations
Saildrone announced that the first four Saildrone Voyager USVs (unmanned surface vehicles) have been registered in Denmark and will operate under…
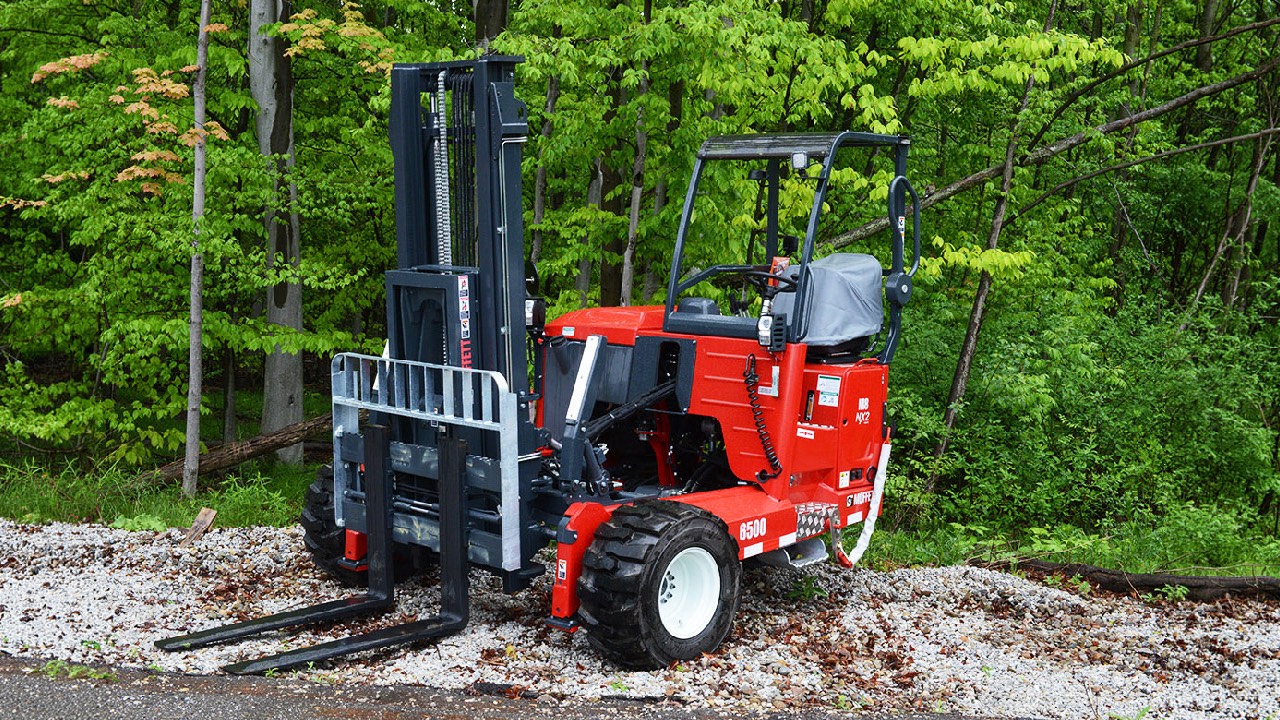
Hiab Unleashes Next-Level Productivity with the MOFFETT M8 NX2: 6,500 lb Powerhouse for North America
Higher Capacity, Same Compact Transport Weight, Delivering Unmatched Job Site Speed, Single-Side Offloading Efficiency, Lower Total Cost of…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
