Offshore vessel fleets tighten amid sustained supply discipline

Across offshore energy markets, vessel fundamentals are entering a more nuanced phase of recovery. While macroeconomic and geopolitical forces continue to weigh on oil prices and capital allocation, utilisation trends across offshore support, wind and service fleets point to a tightening supply-demand balance through 2026 and beyond. Fleet ageing, constrained reactivation, and selective newbuild ordering are increasingly shaping utilisation outcomes rather than demand growth alone.
Offshore support vessels: Maturing fleet, improving balance
The global offshore support vessel (OSV) market posted modest but meaningful improvement in 2025. Demand days increased by 2% year-on-year, lifting marketed utilisation to an average of 76%. Westwood’s MarineLogix data underscores a steadily tightening market, particularly when viewed against the backdrop of a maturing fleet.
More than half of the operational OSV fleet is now over 15 years old. Nevertheless, the operational fleet expanded slightly in late 2025 to 3,209 units due to newbuild deliveries, while the laid-up fleet declined marginally. The net reactivation of only two vessels highlights a key theme: utilisation is improving not because of aggressive reactivation or scrapping cycles, but because accessible and commercially viable supply is increasingly limited.
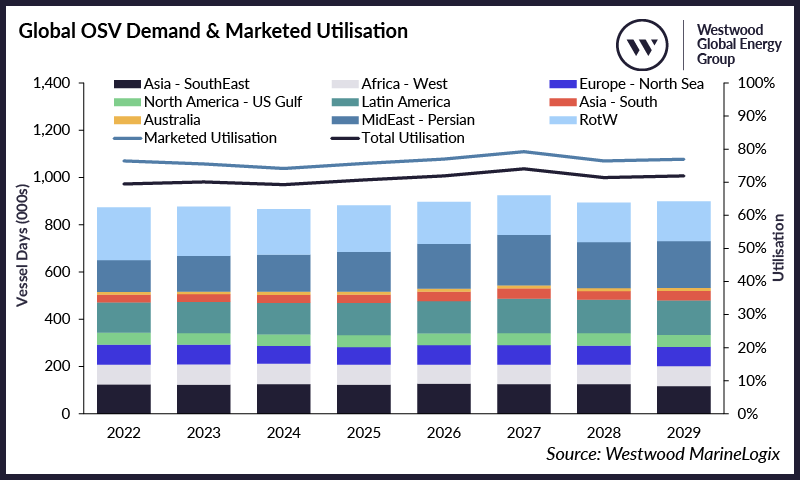
GLOBAL OSV DEMAND & MARKETED UTILISATION OUTLOOK
SOURCE: WESTWOOD MARINELOGIX
Regionally, demand remains concentrated in the Middle East, Latin America and Southeast Asia, together accounting for close to half of global OSV demand days. Operational fleet movements have been uneven. South Asia and West Africa recorded net inflows of active tonnage, while the North Sea saw the largest outflow, reflecting both regulatory pressure and continued redeployment.
The laid-up fleet has fallen sharply from more than 1,500 vessels during the COVID-19 downturn to fewer than 400 units by 4Q 2025. However, demolition activity remains muted, constrained by low scrap steel prices and uncertainty around future utilisation. This has preserved optionality within the supply side but at the cost of higher average fleet age.
Looking ahead, marketed utilisation is forecast to rise to 77% in 2026 and exceed 79% in 2027. With the OSV orderbook standing at 216 vessels – mostly AHTS vessels and PSVs – incremental supply growth remains manageable. In essence, incremental demand growth is translating more directly into utilisation upside than at any point in the past decade.
Offshore wind vessels: Capacity constraints emerge
Major offshore wind markets across the UK, Europe and APAC (excluding Mainland China) are increasingly aligning and streamlining policy frameworks to support project execution, in contrast to the US where regulatory uncertainty continues to weigh on market momentum. Marketed utilisation for wind turbine installation vessels (WTIVs) engaged in transport and installation (T&I) activities moderated to 64% by end 2025, down from 70% in 2024, before rebounding to c.79% in 2026.
This acceleration is primarily driven by a step-up in turbine and foundation installation activity. Installation volumes in 2026 are expected to nearly double year on year, while cumulative installed offshore wind capacity is forecast to exceed 236GW by 2030. Although the near-term project pipeline has softened marginally, the medium to long term outlook remains structurally robust, underpinned by continued capacity expansion and policy support.
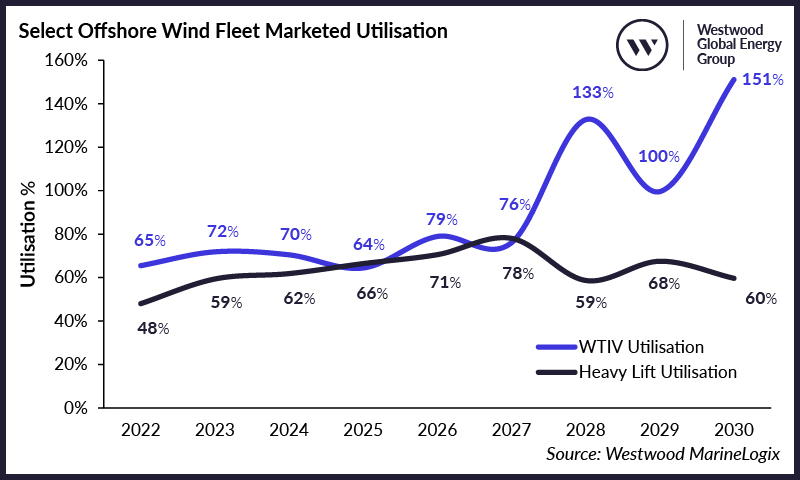
SELECT OFFSHORE WIND FLEET MARKETED UTILISATION OUTLOOK
SOURCE: WESTWOOD MARINELOGIX
In 2025, a greater share of heavy lift vessel activity was driven by offshore wind projects relative to 2024. Looking ahead, demand is expected to be supported by a resurgence in oil and gas workscopes, with utilisation projected to reach approximately 78%.
Fleet fundamentals reinforce this utilisation outlook. At the end of 2025, the global operational fleet (excluding Mainland China) comprised 38 WTIVs, 51 heavy lift vessels, and 87 commissioning service operation vessels (C/SOVs). The WTIV and heavy lift orderbook remains limited with only five WTIVs and seven heavy lifts on order respectively, whereas the C/SOV segment is experiencing a pronounced build cycle with 58 firm orders.
Over the medium term, the WTIV T&I segment is expected to remain structurally undersupplied based on the currently visible fleet, with the heavy lift market also showing signs of tightening. While some incremental capacity may be unlocked through the retrofitting of Mainland China units or the redeployment of vessels from the oil and gas sector, such measures are expected to provide only limited relief and remain dependent on vessel suitability and regulatory compliance.
Offshore service vessels: Selective supply tightness
In 2025, marketed utilisation averaged 73% for pipelay vessels, while ROV support vessels (ROVSVs) and saturation dive support vessels (Sat DSVs) recorded 75% and 73% respectively.
These segments have exhibited disciplined fleet expansion, with newbuild activity remaining constrained due to the significant capital intensity required. The current operational fleet comprises 105 pipelay vessels, 207 ROVSVs and 74 Sat DSVs. Orderbook visibility is limited across most segments, with the exception of ROVSVs, and only a single pipelay vessel is currently under construction.
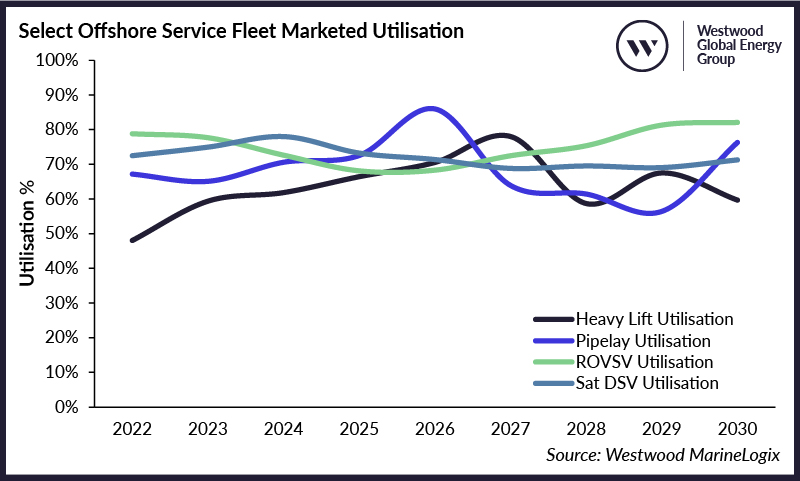
SELECT OFFSHORE SERVICE FLEET MARKETED UTILISATION OUTLOOK
SOURCE: WESTWOOD MARINELOGIX
ROVSVs and Sat DSVs are expected to sustain elevated utilisation levels, underpinned by ongoing brownfield activity, IRM requirements, and continued offshore wind development. The inherent versatility of ROVSV units enables deployment across offshore wind workscopes, including cable installation support and walk-to-work accommodation. Demand for Sat DSVs is expected to be further supported by project activity in the Gulf Cooperation Council region and across Asia.
While the Middle East and Asia continue to account for the majority of pipelay activity, 2026 is expected to see increased contributions from regions such as Africa, Latin America and Australia, driving utilisation up to approximately 86%.
A converging theme: Utilisation optimisation and strategic positioning
While macroeconomic risks persist, particularly around price volatility and policy uncertainty, underlying vessel markets are increasingly characterised by tightening fundamentals. For owners and investors, the next phase of the cycle is expected to be defined less by rapid fleet expansion and more by optimising utilisation, advancing fleet renewal, diversifying geographically, and strategically positioning for structurally tighter market conditions through the latter half of the decade.
How MarineLogix supports market interpretation
This analysis forms part of the quarterly market reports included in the MarineLogix subscription, which also provides:
- Global vessel demand and utilisation analytics
- Vessel specifications, ownership and tracking
- Daily fleet movements and proximity tools
- Integrated offshore oil and gas infrastructure mapping
MarineLogix brings together AIS intelligence, vessel specifications, utilisation analytics and market insights – giving subscribers a unified, data‑driven view of the offshore marine landscape.
Source: Westwood Energy



Related News.

Navigating the Multi-Orbit Era: In Conversation with Intellian’s Jon Harrison at SMM 2026
At SMM 2026 in Hamburg, the rapid evolution of maritime satellite communications took centre stage. Across the exhibition halls, discussions among…

Cyprus ports need joint energy and investment strategy, shipping agents chief says
Cyprus needs a coordinated strategy for shipping, energy and environmental protection to support port investment and modernisation, Cyprus shipping…

MASO Public Affairs introduces MASO Regulatory Intelligence
A new subscription service helping businesses understand what is changing and what it means for them MASO Public Affairs introduces MASO Regulatory…

Anglo-Eastern helps turn CMBTECH’s ammonia ambition into an operational reality
From early feasibility study and risk-based design to newbuilding supervision, crew readiness and technical management, Anglo-Eastern drew on its…

Escalation of attacks threatens to derail recovery in Middle East oil exports
World oil demand is forecast to fall by 2.5 mb/d y-o-y in 4Q26 and 2.6 mb/d on average in 2026. As the Iran war manifests itself through restricted…

New study finds shipping pays twice its share to EU ETS earmarked revenues should triple to help build market for sustainable fuels and technologies
Shipping is responsible for around 10% of EU ETS emissions but pays almost 20% of the ETS bill. Unlike other sectors, it has never received free…

MSARC strengthens maritime mass rescue readiness through training and national live exercise off Dakar, Senegal
Joint MSARC–FHAS programme combines three days of SAR training with a national multi-agency live exercise The Maritime Search and Rescue Council ,…

Sogese report deliveries are still being delayed as container freight rates fluctuate
FOR IMPORTERS Spot rates into the Mediterranean are back at January levels, Far East to Europe reliability sits at pandemic lows, and nearly…

Glencore begins trading on Australian Securities Exchange
Glencore has begun trading on the Australian Securities Exchange under the ASX code GLC. Gary Nagle, Glencore’s CEO, said it was an exciting day for…

BIMCO Shipping Number of the Week
Suez Canal container ship transits exceed 50% of pre-disruption levels "During the first two weeks of October, weekly container ship capacity…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
