Drewry World Container Index – 22 Oct

WCI increased for the second consecutive week, the highest in 15 weeks. See detailed commentary below.
Drewry World Container Index (US$/40ft)
WCI Trade Routes from Shanghai (US$/40ft)
Source: Drewry World Container Index, Drewry Supply Chain Advisors
Detailed assessment for Thursday, 22 Oct 2026
- The Drewry World Container Index (WCI), the benchmark widely referenced by procurement teams, increased 2% to $4,585 per 40ft container, driven by higher rates on the Asia to Europe and Transpacific trade routes.
- On the Transpacific trade route, rates from Shanghai to Los Angeles rose 2% to $8,007 per 40ft container and those from Shanghai to New York inched up 1% to $10,166 per 40ft container. According to Drewry’s Container Capacity Insight, only two blank sailings have been announced for next week, down from six this week, indicating more effective capacity. Since strong US import demand continues to support freight rates, Drewry expects rates to remain stable next week.
- On the Asia–Europe trade route, rates from Shanghai to Rotterdam increased 3% to $3,632 per 40ft container and those from Shanghai to Genoa grew 5% to $4,152 per 40ft container. According to Drewry’s Container Capacity Insight, eight blank sailings have been announced for next week, up from two this week, indicating tight capacity. Carriers are reducing capacity via blank sailings to put upwards pressure on freight rates. Meanwhile, congestion at key Asian ports has eased, with vessel waiting times at Shanghai falling from 97 hours in Week 38 to 38 hours in Week 42, indicating significant improvement in port operations. Drewry expects rates to increase slightly next week amid tight capacity.
- The East-West container freight market remains uncertain. Security risks and attacks on ships continue to affect vessel movements through the Gulf, with only two containerships sailing into the Gulf in Week 42, down from five the previous week. Meanwhile, sailings through the Suez Canal increased slightly, from 54 in Week 41 to 55 in Week 42. Transpacific rates continue to receive support from US import demand, while carriers are attempting to sustain Asia–Europe rates through capacity management and surcharges. Although easing congestion at key Asian ports is improving vessel waiting times, the outlook remains dependent on demand, capacity adjustments and developments in regional security.
Spot freight rates by major route
Our assessment across eight major East-West trades
Source: Drewry Supply Chain Advisors
WCI Methodology
Ocean spot market freight rates against 6,700 global port pairs
If you need spot market container freight rate information on other routes to those above, find out more about our Container Freight Rate Insight (CFRI) online service, which covers 6,700 global port pairs updated monthly (2,450 updated fortnightly).
Source: Drewry



Related News.
Predicting the Future or Preparing for It? Cyprus Marine Club Explores the Power of Adaptability with Natasa Pilides
In a world where uncertainty has become the new normal, is predicting the future really the best strategy, or is the ability to adapt the greater…
Greece and Egypt in talks to extend EEZ Eastwards towards Cyprus following Libya’s move on Turkish Maritime Pact
Athens and Cairo have agreed to advance bilateral consultations aimed at extending the geographical scope of their 2020 Exclusive Economic Zone (EEZ)…
Seafarers face widening competency gap as digital shipping accelerates, recent research finds
Eighty two per cent of maritime professionals surveyed say current training does not adequately prepare crews for the realities of modern,…
Wärtsilä and WinGD sign new Service Framework Agreement to ensure long-term continuity and support for the global fleet
Technology groups Wärtsilä and WinGD have entered into a new long-term Service Framework Agreement, reaffirming their shared commitment to supporting…
Seatrium and Karpowership sign contract for a series of whale class Powership Conversion and Integration Projects
Seatrium and its strategic partner, floating power leader Karpowership, have strengthened their longstanding collaboration with the award of a…
ClassNK releases Handbook Supporting Consideration of Onboard Carbon Capture “Onboard Carbon Capture Systems Implementation Framework”
Bringing together technical, infrastructure, regulatory and emissions assessment considerations across the OCCS value chain - ClassNK has released a…
HHLA lowers earnings forecast for the 2026 financial year
Based on the business development to date and updated estimates for the fourth quarter of 2026, the Executive Board of Hamburger Hafen und…
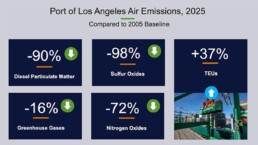
Port of Los Angeles reports lowest emissions per Container on Record
The Port of Los Angeles continued to make clean air gains in 2025, recording its lowest emissions per container on record, according to the Port's…
Mammoet, Port of Argentia and Argentia Capital Partner to Advance Floating Dry Dock and Marine Repair Facility
Partnership builds on Mammoet’s established presence at Port of Argentia and shared confidence in the growing market for ship repair and marine…
DORIC WEEKLY INSIGHT 23 OCTOBER 2026
Please find Below the DORIC Market Insight for the week ending 23rd October 2026. Weekly Report 23.10.2026
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
