Rising Atlantic ballasters, Gladstone congestion highs, and Russian grain flows.

|
EGYPT| Top Destination for Russian Wheat Egypt’s near-doubling of Russian wheat imports in November is consistent with the country’s renewed buying spree, as state buyer Mostakbal Misr secured roughly 500,000 tonnes of Black Sea wheat, including a large share from Russia, for December–January delivery, while Egypt intensified purchases to stabilise domestic supply. Recent reports also note that Ukraine and Bulgaria have increased shipments to Egypt, but Russia remains the dominant supplier, reinforced by high-level negotiations and deepening economic ties highlighted during Russia’s November delegation visit to Cairo. Together, these developments confirm the sharp year-on-year rebound in Egypt’s intake of Russian wheat and its continued role as Moscow’s top overseas market. FREIGHT MARKET Mixed The Capesize freight market gained significant momentum. In contrast, the Panamax and Supramax sectors exhibited weaker momentum, particularly for routes from the East Coast of South America (ECSA) and the US Gulf (USG) to the Far East.
Capesize | Firmer
Panamax | Weaker
Supramax | Weaker
BALLASTERS OVERVIEW Capesize | Vessel count grows in Australasia
Handysize | Vessel count grows in North Atlantic
The Capesize segment takes center stage regarding demand, focusing on the increase in tonne-days relative to the Baltic Capesize Index. The tighter supply of ballasters in the South Atlantic combined with the rise in tonne-days, has positively impacted the freight market sentiment.
The Baltic Capesize Index (BCI) has now reached its highest level of the year, supported by a steady recovery in tonne-days. Tonne-days for Capesize vessels have risen consistently from the late-August lows, currently holding above 130M after briefly approaching 140M at the end of October. As we enter the final stretch of Q4, market sentiment has turned more positive. This shift comes even as China’s property sector continues to influence expectations for steel production and iron ore demand. Meanwhile, seaborne supply from Brazil, Australia, and South Africa remains firm, with export programmes indicating stable flows into year-end. CONGESTION | Gladstone
|


 Congestion at Gladstone is clearly elevated and accelerating into December 2025, with the number of vessels rising sharply from mid-November to early December and reaching just above 50 ships, well above the 35–45 range seen through 2024 and marking the highest level in two years. The latest surge appears to align with earlier-year throughput weakness, supply-chain delays, and a strong Q4 push in coal and bauxite exports.
 The significant escalation in dry bulk traffic is highlighted by week-on-week and month-on-month jumps of 31% and 28%, suggesting this rise is more substantial than typical seasonal variation. The majority of this traffic involves Panamax, Post-Panamax, and Capesize vessels. Furthermore, the cargo composition intensifies the pressure: metallurgical coal constitutes approximately 40% of port activity, with bauxite following at 20%, thermal coal at 16%, and alumina at 13%.
Source: Signal Ocean



Related News.
European Shipowners call on MEPs to back Commission proposal to include two Indian yards in the EU ship recycling list
The Environment Committee of the European Parliament votes on 4 November on a motion for resolution objecting to the Commission’s proposal to add two…
Oversea signs commercial agreement with UECC following Successful Pilot
Following a successful pilot onboard Auto Advance, UECC has chosen to enter into a commercial agreement with Oversea. The pilot demonstrates how…
First NABEP Crude Cargo Under U.S. Agreement Arrives in Texas
Shipment of 1 million barrels arrived as NABEP production passes 223,000 barrels of oil equivalent per day. Two tankers carrying 1 million barrels of…
LNG carrier prices fall to $245 million, threatening Korean Shipbuilders’ Margins
Prices for high-value vessels, including liquefied natural gas carriers and ultra-large container ships, have begun to decline despite rising…
Vehicle Carrier Safety Forum publishes new Fire Drill Guidelines for vehicle carrying vessels
The Vehicle Carrier Safety Forum has published new Fire Drill Guidelines for Vehicle Carrying Vessels, providing vessel operators with a practical…
Is an Atlantic Basin crude glut on the cards?
Atlantic crude discounts fail to offset high freight to Asia, raising the risk of a regional glut as VLCC availability tightens. Freight…
The future of trade infrastructure in Europe is connectivity
One year after its inauguration, Rijeka Gateway offers a glimpse into the future of European trade. On 10 September last year,…
Allied – Weekly Market Review – Week 43
Please find below the Allied Weekly Report for Week 43 | 2026 ALLIED - Weekly Market Report- Week 43
Intermodal Report – Week 43 2026
Please find below the Intermodal market report for week 43 2026. Intermodal Report Week 43 2026
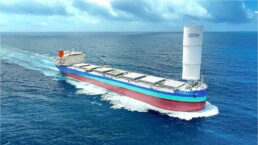
Wind Challenger-Equipped LNG Dual-Fueled Coal Carrier ‘MAIZURU KAZENOMAI’ Delivered
-While Supporting a Stable Energy Supply, Reducing Environmental Impact - Mitsui O.S.K. Lines announced the delivery and entry into service of an…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
