BIMCO Shipping Number of the Week
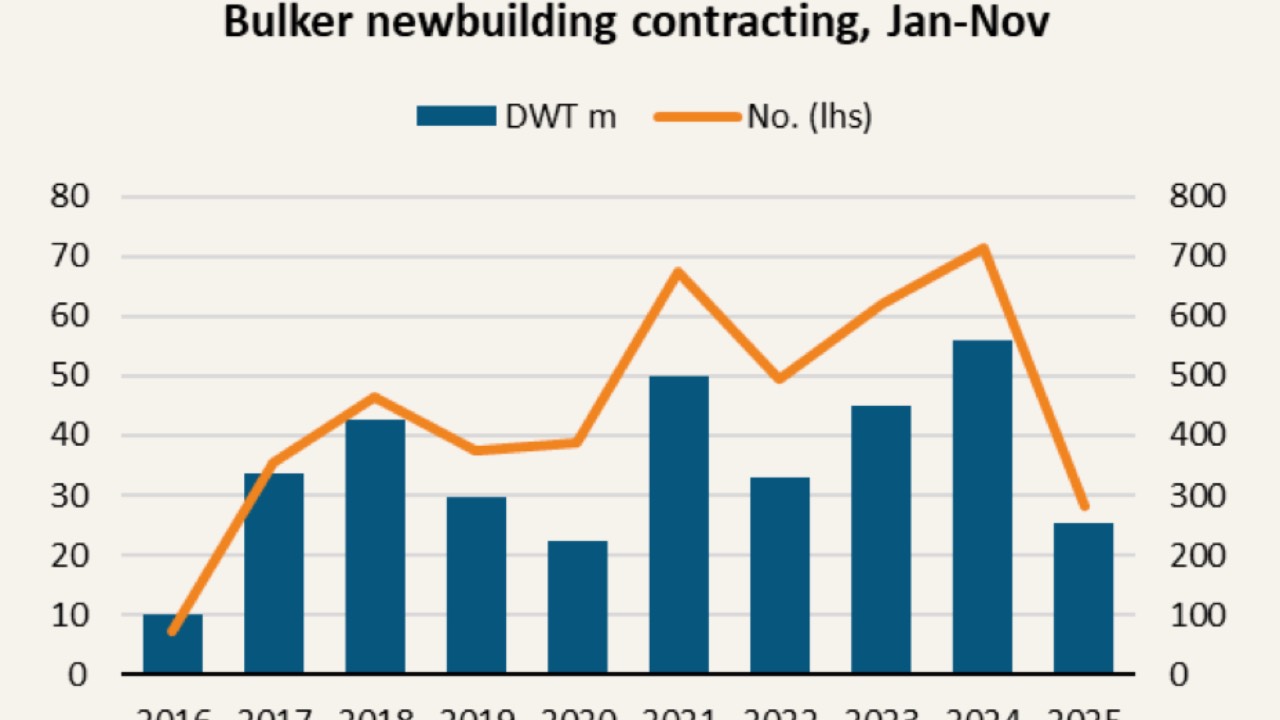

Bulker newbuilding contracting drops 54% to five-year lo
“Between January and November 2025, the capacity of bulker newbuilding contracting has fallen 54% y/y to 25m DWT, reaching its lowest level since 2020. Consequently, the dry bulk orderbook is now 4% smaller than a year ago, accounting for 11% of the dry bulk fleet. Contracting has likely eased due to a cloudy market outlook,” says Filipe Gouveia, Shipping Analysis Manager at BIMCO.
The number of ships contracted has seen an even steeper decline, down 61% y/y so far in 2025. Only 281 ships have been ordered, the lowest number since 2016. While contracting has fallen across all segments, orders in the capesize segment, which contains the largest ships in the dry bulk fleet, have been comparatively higher.
The outlook for freight rates over the next two years appears strongest for the capesize segment. Cargo demand growth could soften but sailing distances are expected to lengthen, boosting tonne mile demand. Furthermore, supply growth is estimated be low amid limited deliveries. Capesize ships face the longest lead times with 77% of contracting so far this year scheduled to be delivered after 2027.
“Contracting in the supramax and panamax segments has declined significantly, falling 76% y/y and 55% y/y respectively. Both segments have comparatively large orderbooks and therefore an expected increase in ship deliveries in 2026 and 2027. In addition, their demand outlook appears weak, while a potential return of ships to the Red Sea poses a further downside risk to demand for these segments. These factors could lead to weaker freight rates over the next two years, which might be discouraging newbuilding contracting,” says Gouveia.
Chinese shipyards have received 81% of new orders in terms of ship capacity, up nine percentage points compared to 2024, at the cost of Japan’s market share. China has thereby remained by far the most dominant shipbuilding nation in the bulk sector in 2025, despite the previous announcement of the now suspended USTR port fees on Chinese built ships. Shipments to or from the US only account for 8% of global cargoes, which, paired with several fee exemptions, likely contributed to continued preference for Chinese yards.
One factor supporting newbuilding contracting is a 3% drop in prices since the start of 2025, compared to a 4% increase in five-year-old second-hand prices. Currently, a five-year-old second-hand ship will on average sell for 93% of the price of a newbuilt. This is a reflection of a strengthening of market conditions and freight rates during the second half of the year. While lower prices could theoretically encourage contracting, lead times for new orders remain high. Therefore, ships ordered today may be delivered under vastly different market conditions.
“In 2025, the share of contracted capacity designed to use alternative fuels has decreased, but the share designed to allow for future retrofitting has increased. This could reflect lingering uncertainty over the availability of alternative fuels. Overall, 12% of the current orderbook could use alternative fuels upon delivery, of which 48% could use methanol, 37% LNG and the rest could use ammonia,” says Gouveia.
Source:BIMCO



Related News.

ISLAND OIL: Unveiling of the Sculpture “Cyprus’s Journey Through the Ages” in Protaras – A Tribute and Landmark to Cyprus’s Historical Memory and Cultural Heritage
In a modest ceremony marked by a moving atmosphere, the sculpture “Cyprus’s Journey Through the Ages”, created by acclaimed Cypriot sculptor…

World Maritime Day 2026 from Policy to Practice – powering Maritime Excellence
Global regulations will deliver safer, more resilient shipping when they are implemented worldwide. The international maritime community marks…

Diana Shipping announces Time Charter Contract for m/v DSI Polaris with Dai An Ocean Shipping
Diana Shipping , a global shipping company specializing in the ownership and bareboat charter-in of dry bulk vessels, announced that, through a…

Chief Economists Expect Global Economy to Stabilize, but Fiscal Constraints, Rising Living Costs and AI Investment Uncertainty Threaten Growth
The global economy is stabilizing, but the fiscal support that cushioned successive shocks since 2020 is unlikely to play the same role in the year…

V. welcomes its new graduate cohort as programme expands across the group
Twelve graduates from nine nationalities join 11th year of V.’s expanded international management programme. V., the global ship manager and marine…

From Policy to Practice: Why Seafarers Are the Key to Maritime Excellence
The shipping industry is no stranger to regulation. Seafarers and ship operators work within a vast framework of international conventions, national…

Intermodal Report – Week 38 2026
Please find below the Intermodal market report for week 38 2026. Intermodal Report Week 38 2026 Market Insight By Nikos Tagoulis, Head of…

Allied – Weekly Market Review – Week 38
Please find below the Allied Weekly Report for Week 38 | 2026 ALLIED - Weekly Market Report- Week 38

Record year on the Northeast Passage but Arctic shipping remains very limited
In 2025, a record 103 transit voyages were made via the Northeast Passage. However, this is still equivalent to only around a day and a half of…

[xclusiv] S&P Report 21th September 2026
Please find below the [xclusiv] latest Weekly S&P Report [xclusiv] 2026_09_21 Market Commentary: VLCCs: Freight Boom Reprices the Fleet The VLCC…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
