Commencement of operations at the Simandou mine unlocks a new era of long-haul iron ore flows

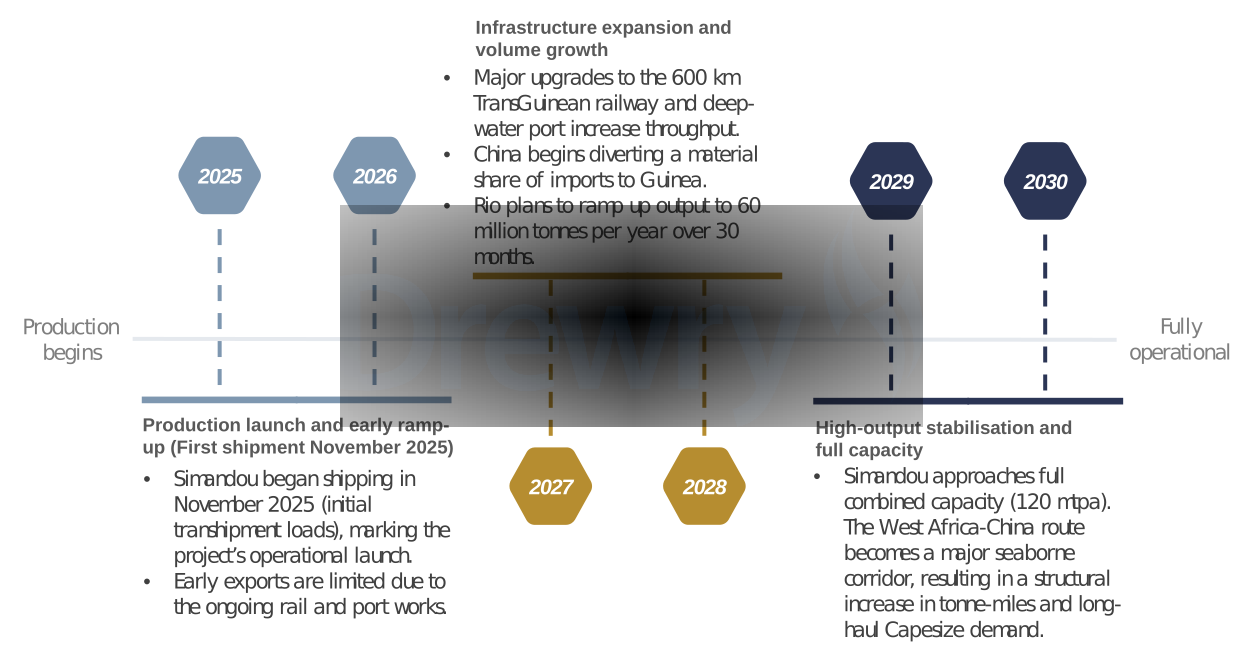
The emergence of the Guinea–China long-haul iron ore trade will structurally support global Capesize demand, supporting freight rates across all major routes and creating one of the strongest tonne-mile expansions in recent dry bulk history. It will also help China to reduce its reliance on Australia to some extent.
Simandou is one of the world’s biggest and highest-grade iron (65% Fe content) ore deposits, located in southeast Guinea. The first iron ore shipment from the Simandou project was shipped in November 2025. The ore was transported from the SimFer mine via the newly constructed Trans-Guinea railway to the Morebaya port, one of the key export facilities built as part of the Simandou project, and loaded onto a bulk carrier for shipment to China.
Simandou is divided into two zones: Blocks 1-2 are operated by the China-aligned WCS consortium and have a reserve of 1.8 billion tonnes, while Blocks 3-4 are led by the Rio Tinto-Chalco joint venture, having reserves of 1.5 billion tonnes, with Guinea holding a 15% stake. Although Rio Tinto is a major partner in the southern blocks, Chinese entities collectively have the largest strategic influence across the entire project through both mine ownership and shared control of the rail-port infrastructure. China is the largest combined strategic stakeholder across all four blocks.
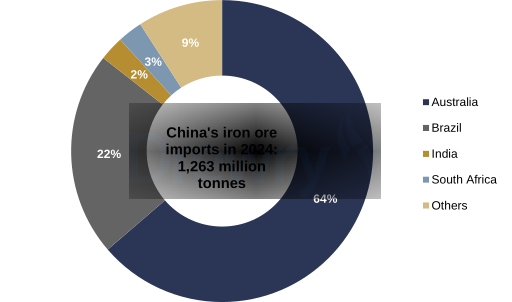
China’s shifting iron ore import strategy
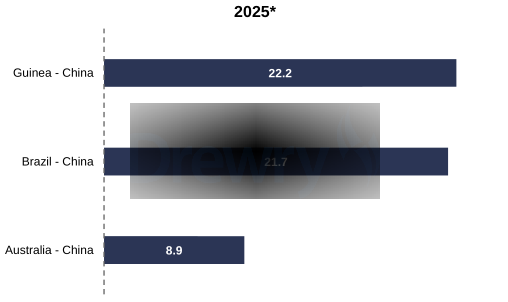
In Brazil, Vale supplies more than 80% of the country’s iron ore and has shipping arrangements with COSCO and other Chinese companies. Therefore, a spike in iron ore imports from Guinea is unlikely to cause a decline in the iron ore trade on the Brazil-China route. Since China is involved in Guinea’s iron ore investment, most of the Guinean iron ore is likely to be exported to China. Meanwhile, China’s political relations with Australia have been strained, and it is more probable that a rise in Guinea’s iron ore supply will prompt Chinese importers to shift away from Australia to Guinea, boosting shipping demand.
Figure 2: Australia has the long-standing dominance in China’s iron ore market
Source: Drewry Maritime Research
Additionally, high-Fe content iron ore provide the high-grade input required for low-emission steel, making it crucial for the global green steel transition.
DRI-EAF and hydrogen-based steelmaking needs DR-grade ore (67%+ Fe), but such ore is extremely scarce, and only a small share of the global seaborne market meets this threshold. Without high-grade ore, green hydrogen DRI cannot scale. Net-zero pathways (2050) call for a major shift from blast furnaces to DRI-EAF. The structural shortage of DR-grade projects makes high-grade deposits such as Simandou (65% Fe, near DR-grade) strategically critical for green steel.
With trade routes getting longer, Capesizes get stronger
Assumption: A spike in imports from Guinea will lead to an equivalent decline in China’s iron ore imports from Australia.
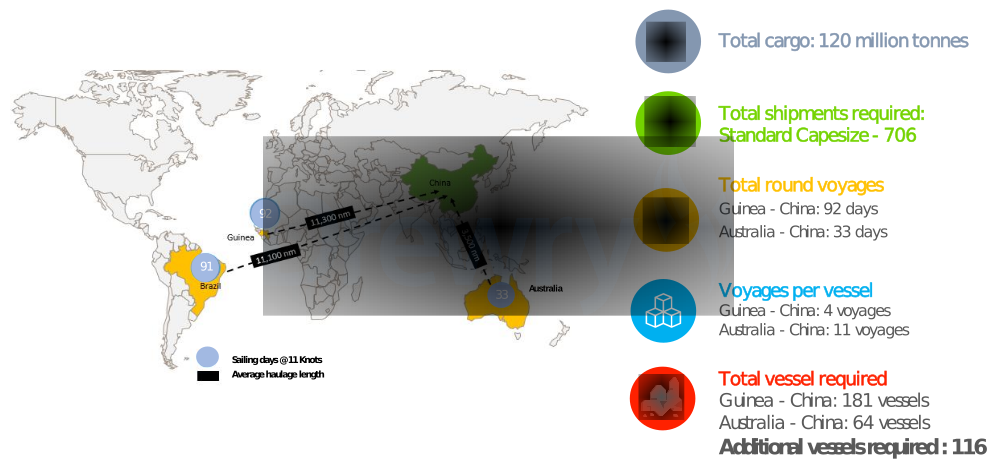
The shift in iron ore trade flows from Australia-China to Guinea-China will boost the vessel utilisation of Capesizes. Once Simandou reaches its targeted 120 million tonnes of annual exports, most likely by 2030, the Guinea-China route will require almost 180 Capesizes compared to 64 vessels needed to transport the same volume from Australia due to the significantly shorter sailing distance. The Guinea-China round voyage is more than 90 days, almost three times the 30-35 days Australia-China rotation.
As a result, each Capesize operating on this route completes fewer voyages per year, increasing vessel demand for the same volume of trade. This shift in trade will lead to a net demand of 116 additional Capesize vessels, representing one of the largest single tonne-mile expansions anticipated in the dry bulk sector in this decade.
Figure 3: Longer-haul trade flows to strengthen Capesize utilisation
Source: Drewry Maritime Research
Although the freight rate between Australia-China is one-third compared to Guinea-China, making Guinea’s ore seemingly more expensive, China is still likely to prioritise sourcing from Guinea. This is because Guinea will supply high-grade, low-impurity iron ore (65% Fe), a similar edge that Brazil has, compared to Australia’s predominantly 59–61% Fe ores, which requires more blending to meet the required quality standards.
Consequently, the shipping cost structure of Brazil and Guinea will be broadly comparable, and once Simandou reaches full-scale production, its cost curve is expected to be similar to Brazil (if not low). Moreover, China’s objective of diversifying away from Australian supply, combined with its massive investment in Guinea’s rail and port infrastructure, makes economic and strategic sense.
This will push charter rates up on major routes and not only on West Africa-China, as fewer ships remain available for flexible deployment. Overall, the development of Simandou will create a structurally stronger Capesize freight market, with strong earnings across global routes for years to come.
Figure 4: Spot rates on major ore routes ($/tonne)
* YTD average.
Source: Clarkson’s, Drewry Maritime Research
Conclusion
Simandou’s emergence marks a fundamental reshaping of long-haul iron ore trade flows, creating a structural uplift in global Capesize demand and supporting freight markets for the rest of the decade. Its high-grade ore also aligns with China’s decarbonisation path, reinforcing its strategic value.
Source: Drewry



Related News.
European Shipowners call on MEPs to back Commission proposal to include two Indian yards in the EU ship recycling list
The Environment Committee of the European Parliament votes on 4 November on a motion for resolution objecting to the Commission’s proposal to add two…
Oversea signs commercial agreement with UECC following Successful Pilot
Following a successful pilot onboard Auto Advance, UECC has chosen to enter into a commercial agreement with Oversea. The pilot demonstrates how…
First NABEP Crude Cargo Under U.S. Agreement Arrives in Texas
Shipment of 1 million barrels arrived as NABEP production passes 223,000 barrels of oil equivalent per day. Two tankers carrying 1 million barrels of…
LNG carrier prices fall to $245 million, threatening Korean Shipbuilders’ Margins
Prices for high-value vessels, including liquefied natural gas carriers and ultra-large container ships, have begun to decline despite rising…
Vehicle Carrier Safety Forum publishes new Fire Drill Guidelines for vehicle carrying vessels
The Vehicle Carrier Safety Forum has published new Fire Drill Guidelines for Vehicle Carrying Vessels, providing vessel operators with a practical…
Is an Atlantic Basin crude glut on the cards?
Atlantic crude discounts fail to offset high freight to Asia, raising the risk of a regional glut as VLCC availability tightens. Freight…
The future of trade infrastructure in Europe is connectivity
One year after its inauguration, Rijeka Gateway offers a glimpse into the future of European trade. On 10 September last year,…
Allied – Weekly Market Review – Week 43
Please find below the Allied Weekly Report for Week 43 | 2026 ALLIED - Weekly Market Report- Week 43
Intermodal Report – Week 43 2026
Please find below the Intermodal market report for week 43 2026. Intermodal Report Week 43 2026
Wind Challenger-Equipped LNG Dual-Fueled Coal Carrier ‘MAIZURU KAZENOMAI’ Delivered
-While Supporting a Stable Energy Supply, Reducing Environmental Impact - Mitsui O.S.K. Lines announced the delivery and entry into service of an…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
