OPEC lifts 2026 oil demand view

Oil Market Highlights
Crude Oil Price Movements
In July, the OPEC Reference Basket (ORB) value increased by $1.24 month-on-month (m-o-m), to average $70.97/b. The ICE Brent front-month contract dropped by 25¢, m-o-m, to average $69.55/b, and the NYMEX WTI front-month contract dropped by 9¢, m-o-m, to average $67.24/b. However, the GME Oman’s front-month contract increased by $1.93, m-o-m, to average $71.42/b. The ICE Brent-NYMEX WTI first-month spread narrowed by 16¢, m-o-m, to average $2.31/b. The ICE Brent and NYMEX WTI forward curves slightly flattened in July, m-o-m, but remained in strong backwardation, while the GME Oman forward curve further strengthened, moving into more pronounced backwardation. Hedge funds and other money managers significantly raised their bullish bets on ICE Brent but sharply lowered their NYMEX WTI net long positions.
World Economy
The global economy is expected to maintain its stable growth trajectory, as supported by the consistent and strong momentum observed in 1H25. The global economic growth forecast for 2025 is revised up slightly to 3.0%, while the forecast for 2026 remains at a robust 3.1%. The US economic growth forecast is revised up slightly to 1.8% for 2025 but remains at 2.1% for 2026. Japan’s economic growth forecasts remain unchanged at 1.0% for 2025 and at 0.9% for 2026. The Eurozone economic growth forecasts are revised up slightly to 1.2% for both 2025 and 2026. China’s economic growth forecast is revised up slightly to 4.8% for 2025, but remains at 4.5% for 2026. India’s economic growth forecasts remain at 6.5% for both 2025 and 2026. Brazil’s economic growth forecasts remain unchanged at 2.3% for 2025 and 2.5% for 2026. Similarly, Russia’s economic growth forecasts for 2025 and 2026 remain unchanged at 1.8% and 1.5%, respectively.
World Oil Demand
The global oil demand growth forecast for 2025 remains at 1.3 mb/d, y-o-y, unchanged from last month’s assessment. Some minor adjustments were made, mainly due to actual data received for 1Q25 and 2Q25. In the OECD, oil demand is forecast to grow by about 0.1 mb/d in 2025, while non-OECD oil demand is forecast to grow by 1.2 mb/d in 2025. In 2026, global oil demand is forecast to grow by 1.4 mb/d, y-o-y, revised up by 0.1 mb/d from last month’s assessment, on the back of supportive economic activities. The OECD is projected to grow by about 0.2 mb/d, y-o-y, while the non-OECD is expected to expand by 1.2 mb/d, y-o-y.
World Oil Supply
Non-DoC liquids production (i.e., liquids production from countries not participating in the Declaration of Cooperation) is forecast to grow by about 0.8 mb/d, y-o-y, in 2025, unchanged from last month’s assessment.
The main growth drivers are expected to be the US, Brazil, Canada and Argentina. The non-DoC liquids production growth forecast for 2026 is revised down slightly by 0.1 mb/d to average 0.6 mb/d, y-o-y, with Brazil, the US, Canada and Argentina as the main growth drivers. Meanwhile, natural gas liquids (NGLs) and non-conventional liquids from countries participating in the DoC are forecast to grow by 0.1 mb/d, y-o-y, in 2025, averaging 8.7 mb/d, followed by a similar increase of about 0.1 mb/d, y-o-y, in 2026, to average 8.8 mb/d.
Crude oil production by countries participating in the DoC increased by 335 tb/d in July, m-o-m, to average about 41.94 mb/d, according to available secondary sources.
Product Markets and Refining Operations
In July, Atlantic basin refinery margins recovered significantly m-o-m, given the robust middle distillate crack spread performance. All key products across the barrel showed gains on the US Gulf Coast (USGC).
Moreover, the lower diesel availability, as well as low fuel oil imports, led to upward pressure on refining margins.
In Rotterdam, middle distillates margins outperformed all other key products with the exception of High Sulphur Fuel Oil (HSFO), reflecting a tighter diesel market. In contrast, refining margins in Singapore declined m-o-m, as elevated product outflows from China weighed on markets, leading to weakness at the top and bottom sections of the barrel. The global refinery intake in July rose further to reach a record high of 83.6 mb/d, according to preliminary data. This was 884 tb/d higher, m-o-m, and 2.0 mb/d higher, y-o-y.
Tanker Market
Dirty tanker spot freight rates experienced m-o-m declines across all monitored routes in July, amid easing geopolitical concerns. VLCC rates saw the strongest decline, down 14% on average. The decrease was more pronounced on East of Suez routes, with VLCC spot freight rates on the Middle East-to-East route dropping by 20%, m-o-m, compared with a decline of 6% on the Middle East-to-West route. Suezmax rates saw a more moderate decrease, falling by around 5% in the Atlantic basin. In the Aframax market, spot freight rates on the Indonesia-to-East route were down by just 1%, m-o-m, while rates around the Mediterranean fell by about 2%, amid an uptick in activity toward the end of the month. In the clean tanker market, spot rates were mixed, with rates around the Mediterranean up by about 5%, m-o-m, while East of Suez rates declined by 11% on average.
Crude and Refined Product Trade
In July, US crude imports averaged 6.1 mb/d, broadly in line with the previous month’s level, although seasonally stronger, according to estimates based on preliminary data. US crude exports declined for the fifth month in a row to average just 3.3 mb/d, the lowest level since March 2022. Declines were driven by lower flows to Europe and Africa, particularly Nigeria. Product imports fell to an eight-month low of 1.6 mb/d, while US product exports dropped 3%, m-o-m, to remain at a still strong 6.7 mb/d. Preliminary estimates for OECD Europe indicate that crude imports experienced a seasonal decline in June. Product flows into the region fell 10%, m-o-m, with most major categories contributing, while exports picked up amid higher gasoline and diesel outflows. Official monthly data for Japan shows crude imports in June fell below 2 mb/d for the first time since June 2021. Japan’s product imports dropped to a 21-month low of 722 tb/d, while product exports recovered from a low level to average 405 tb/d. China’s crude imports jumped to a 22-month high in June, averaging 12.2 mb/d, with inflows supported by inventory fills. China’s product imports declined following a drop in LPG inflows, while product exports recovered, driven by a jump in fuel oil exports. India’s crude imports in June slipped just below 5 mb/d for the first time in five months. Product imports reached a seven-month high of 1.3 mb/d, supported by a 16% jump in LPG imports. Product exports from India fell by 3%, m-o-m, to average just under 1.4 mb/d, amid lower flows to Asia and Europe.
Commercial Stock Movements
Preliminary June 2025 data show that OECD commercial inventories stood at 2,789 mb, which is 3.2 mb lower than the previous month. At this level, commercial stocks in the OECD were 57.9 mb lower than the same month last year, 91.7 mb lower than the latest five-year average, and 158.6 mb below the 2015–2019 average. Within components, crude stocks fell 9.6 mb, while product stocks rose by 6.3 mb, m-o-m. OECD crude oil commercial stocks stood at 1,348 mb. This was 12.2 mb lower than a year ago, 47.3 mb below the latest five-year average, and 117.4 mb less than the 2015–2019 average. OECD total product stocks stood at 1,441 mb. This is 45.7 mb lower than a year ago, 44.4 mb less than the latest five-year average, and 41.2 mb below the 2015–2019 average.
In terms of days of forward cover, OECD commercial oil stocks fell by 0.1 days, m-o-m, in June to stand at 60.2 days. This is 1.4 days lower than the level registered in June 2024, 3.9 days less than the latest five-year average, and 1.6 days lower than the 2015–2019 average.
Balance of Supply and Demand
Demand for DoC crude (i.e., crude from countries participating in the Declaration of Cooperation) remains unchanged from the previous month, standing at 42.5 mb/d in 2025. This represents an increase of 0.4 mb/d compared to the 2024 estimate. The demand for DoC crude in 2026 is revised up by 0.2 mb/d from the previous month, to 43.1 mb/d—approximately 0.6 mb/d higher than the 2025 projection.
Source: OPEC



Related News.
Navigating the Multi-Orbit Era: In Conversation with Intellian’s Jon Harrison at SMM 2026
At SMM 2026 in Hamburg, the rapid evolution of maritime satellite communications took centre stage. Across the exhibition halls, discussions among…
Cyprus ports need joint energy and investment strategy, shipping agents chief says
Cyprus needs a coordinated strategy for shipping, energy and environmental protection to support port investment and modernisation, Cyprus shipping…
MASO Public Affairs introduces MASO Regulatory Intelligence
A new subscription service helping businesses understand what is changing and what it means for them MASO Public Affairs introduces MASO Regulatory…
Anglo-Eastern helps turn CMBTECH’s ammonia ambition into an operational reality
From early feasibility study and risk-based design to newbuilding supervision, crew readiness and technical management, Anglo-Eastern drew on its…
Escalation of attacks threatens to derail recovery in Middle East oil exports
World oil demand is forecast to fall by 2.5 mb/d y-o-y in 4Q26 and 2.6 mb/d on average in 2026. As the Iran war manifests itself through restricted…
New study finds shipping pays twice its share to EU ETS earmarked revenues should triple to help build market for sustainable fuels and technologies
Shipping is responsible for around 10% of EU ETS emissions but pays almost 20% of the ETS bill. Unlike other sectors, it has never received free…
MSARC strengthens maritime mass rescue readiness through training and national live exercise off Dakar, Senegal
Joint MSARC–FHAS programme combines three days of SAR training with a national multi-agency live exercise The Maritime Search and Rescue Council ,…
Sogese report deliveries are still being delayed as container freight rates fluctuate
FOR IMPORTERS Spot rates into the Mediterranean are back at January levels, Far East to Europe reliability sits at pandemic lows, and nearly…
Glencore begins trading on Australian Securities Exchange
Glencore has begun trading on the Australian Securities Exchange under the ASX code GLC. Gary Nagle, Glencore’s CEO, said it was an exciting day for…
BIMCO Shipping Number of the Week
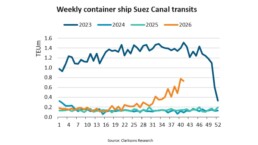
Suez Canal container ship transits exceed 50% of pre-disruption levels "During the first two weeks of October, weekly container ship capacity…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
