Chart of the Week: Spotlight on Capesize Tonne Days to the Far East and C3 Market Rates

|
This week’s Chart Monitor highlights a continued upward trend in tonne-day growth for the Capesize segment during Q2 2025, particularly on voyages from the Atlantic Americas to the Far East. However, the recent surge in demand on the C3 route (Brazil to China) raises concerns about its durability as we move into the third quarter. This week, C3 rates saw a downward trend as ballast vessel activity in the South Atlantic increased, potentially signaling a build-up of supply pressure in the weeks ahead. Meanwhile, Rio Tinto reported its lowest first-half profit in five years, at $4.81 billion, marking a ~16% year-on-year decline. The drop was driven by softer iron ore prices and persistent oversupply from key exporting regions, Australia, Brazil, and South Africa. The company also cut its interim dividend and reported higher unit costs, citing cyclone disruptions and reduced shipments from its Pilbara operations. Global iron ore production stays elevated. Major miners, including Fortescue, Rio Tinto, and BHP, have kept overall iron‑ore output steady or at record levels, while Vale has trimmed its high‑grade pellet guidance. That persistent volume amid soft Chinese steel demand is exacerbating oversupply pressures and capping the scope for a sustained iron‑ore price rebound. Looking ahead, bullish sentiment for Q3 appears increasingly fragile, especially as macroeconomic signals from China continue to weaken. The Chinese manufacturing PMI has remained below the 50-point threshold for several months, registering 49.3 in June, indicating contraction in industrial activity and softening steel demand beyond just construction. Seasonal factors also weigh on steel consumption in July–August, driven by high temperatures, heavy rainfall, and routine maintenance shutdowns, typically resulting in a 5–10% dip in demand. This year, however, the usual seasonal slowdown is compounded by structural economic weakness, exerting further downward pressure on iron ore prices. China’s property sector, responsible for roughly 35–40% of domestic steel and iron ore demand, continues to deteriorate. In Q1 2025, new residential construction starts fell ~24% year-on-year, while property investment dropped ~16–17%. Despite government stimulus efforts, including a ¥4 trillion loan facility and tax incentives, buyer interest remains subdued. A backlog of unsold homes and ongoing developer bankruptcies continue to drag on construction activity and raw material consumption. Finally, China’s portside iron ore inventories climbed to 133–136 million tonnes before the end of June, around 12% above the five-year average, underlining subdued offtake and deepening demand-side risks, rather than any sign of market stabilization.
For more information on this week’s freight, supply, and demand shipping trends, see the analysis sections below. You can also log in to our Newsroom page under Insights & News to stay updated with the latest reports.
SECTION 1/ Freight Rates ($/t) ‘The Big Picture’ – Capesize SofterRemark: Freight market price trends depicted are based on Signal Ocean Assessments. For real-time updates and historical comparisons, access our Freight Market Analytics dashboard here: Signal Ocean Freight Market Analytics. On the C3 and C5 routes, signs of a downward correction are evident, with rates at $23/ton for Brazil–China and $10/ton for Australia–China. Oversupply issues continue in the South Atlantic, as shown by the rising number of ballasters, which has reached a high of 270, while daily loaded volumes stay low at around 1.1M mt. Panamax – ECSA / Far East | USG / China Weaker Supramax spot rates from the U.S. Gulf to the Far East continued their downward trajectory, settling at $40/tonne, mirroring the trend observed the previous week. The ECSA–Far East route also softened further, with rates declining to $36/tonne. Concurrently, daily loading volumes from the USG/USEC fell below 0.3 million tonnes, extending the decline. However, the recent drop in Supramax supply to USG/USEC following the early June spike is providing some support in an otherwise markedly weakening market. SECTION 2/ SUPPLY
Panamax Ballasters Overview (# Vessel Count): Mixed
Supramax Ballasters Overview (# Vessel Count): Increasing
Handysize Ballasters Overview (# Vessel Count): Increasing
SECTION 3/ DEMAND (Capesize) The tonne-days seasonal analysis for steel cargo has shown a significant increase throughout the year, surpassing last year’s second-quarter levels and recently reaching a three-year high. This upward trend is likely to persist, with the Supramax segment continuing to consolidate its role in carrying steel cargoes in the months ahead. Latest estimates reveal a 70% increase compared to the levels observed at the end of July 2023. SECTION 4/ CONGESTION
This week, we highlight the port congestion status for North China, with Tianjin ranking as the most congested port in terms of both waiting and operating Supramax vessels. When comparing recent congestion levels as a percentage of the fleet, we observe that from mid-March to mid-May, congestion hovered around or slightly above 4.5%, exceeding the corresponding period last year. As of the latest estimate on 28th July, congestion stands at 5.5%, now higher than the same period in 2023 and 2024, and approaching 2022 levels. Although this trend is upward, the Baltic Supramax Index, while higher than at the start of the year, has not yet shown a spike that would suggest direct market impact from congestion alone. |


SOurce: Signal Ocean



Related News.
European Shipowners call on MEPs to back Commission proposal to include two Indian yards in the EU ship recycling list
The Environment Committee of the European Parliament votes on 4 November on a motion for resolution objecting to the Commission’s proposal to add two…
Oversea signs commercial agreement with UECC following Successful Pilot
Following a successful pilot onboard Auto Advance, UECC has chosen to enter into a commercial agreement with Oversea. The pilot demonstrates how…
First NABEP Crude Cargo Under U.S. Agreement Arrives in Texas
Shipment of 1 million barrels arrived as NABEP production passes 223,000 barrels of oil equivalent per day. Two tankers carrying 1 million barrels of…
LNG carrier prices fall to $245 million, threatening Korean Shipbuilders’ Margins
Prices for high-value vessels, including liquefied natural gas carriers and ultra-large container ships, have begun to decline despite rising…
Vehicle Carrier Safety Forum publishes new Fire Drill Guidelines for vehicle carrying vessels
The Vehicle Carrier Safety Forum has published new Fire Drill Guidelines for Vehicle Carrying Vessels, providing vessel operators with a practical…
Is an Atlantic Basin crude glut on the cards?
Atlantic crude discounts fail to offset high freight to Asia, raising the risk of a regional glut as VLCC availability tightens. Freight…
The future of trade infrastructure in Europe is connectivity
One year after its inauguration, Rijeka Gateway offers a glimpse into the future of European trade. On 10 September last year,…
Allied – Weekly Market Review – Week 43
Please find below the Allied Weekly Report for Week 43 | 2026 ALLIED - Weekly Market Report- Week 43
Intermodal Report – Week 43 2026
Please find below the Intermodal market report for week 43 2026. Intermodal Report Week 43 2026
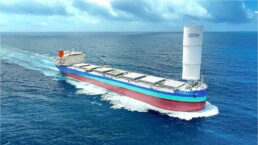
Wind Challenger-Equipped LNG Dual-Fueled Coal Carrier ‘MAIZURU KAZENOMAI’ Delivered
-While Supporting a Stable Energy Supply, Reducing Environmental Impact - Mitsui O.S.K. Lines announced the delivery and entry into service of an…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
