WEEKLY DRY MARKET MONITOR by Signal Ocean

 https://go.signalocean.com/e/983831/amic-drybulkflows-downloadable/2r9gl1/512481828/h/mxzXY7iZZUkITIG4_wMRV-xq_np-WC4J7AlCa2Uxnqk |
| This week’s Chart Monitor highlights a continued upward trend in Brazilian iron ore shipments. Since the end of Q1, each month’s closing volume has exceeded levels seen in previous years. The first quarter of 2025 closed with approximately 70 million tons shipped, followed by over 80 million tons in Q2. These figures are notably higher than the lows recorded in 2021—around 50 million tons in Q1 and 67 million tons in Q2.
Looking ahead, recent news from Vale’s Q2 production report adds to the bullish sentiment. The Brazilian miner reported 83.6 million metric tons of iron ore output in Q2, a 3.7% year-on-year increase. The growth was largely attributed to a new second-quarter production record at the S11D mine in northern Brazil, Vale’s largest operation, and a strong performance at the Brucutu mine in the southeast. With production ramping up and iron ore flows increasing, we are likely to see continued upward pressure on the C3 route in the coming weeks, as tightening vessel supply and rising cargo volumes converge to support a firmer freight market. For more information on this week’s freight, supply, and demand shipping trends, see the analysis sections below. You can also log in to our Newsroom page under Insights & News to stay updated with the latest reports. |
Freight Market, Supply and Demand
SECTION 1/ Freight Rates ($/t)‘The Big Picture’ – Capesize Firmer |
 Remark: Freight market price trends depicted are based on Signal Ocean Assessments. For real-time updates and historical comparisons, access our Freight Market Analytics dashboard here: Signal Ocean Freight Market Analytics. |
|
On the C3 and C5 routes, we’ve seen signs of firmness, with rates surpassing $20/ton for Brazil–China and $10/ton for Australia–China. A comparison of the number of ballasters versus Baltic rates suggests that the recovery on the C5 route is primarily driven by a decline in available ballasters. In contrast, the recent strength on the C3 appears to be more sentiment-driven for now, as there hasn’t been a notable drop in the number of vessels ballasting toward the South Atlantic. This sentiment may be partly fueled by the recent news of Vale’s iron ore production update, which has raised forward expectations for increased iron ore cargo flows. Panamax – ECSA / Far East Softer Panamax spot rates from East Coast South America (ECSA) to the Far East, after peaking in mid-July, have started to gradually soften, although levels remain significantly higher than the lows recorded at the beginning of June. ECSA–Far East rates are still around 9% higher than a month ago, which can be partially supported by forward optimism linked to the U.S. summer crop season. Additionally, Panamax vessel supply to ECSA has seen a continuous downward trend since March, while the daily loaded volume has remained consistently noticeable throughout the year.
SUPRAMAX – Softer Supramax spot rates from the U.S. Gulf to the Far East declined to $40/tonne this week, marking an 8% drop from the previous week. A similar softening is observed on the ECSA–Far East route, where rates fell to $37/tonne, though still approximately 20% higher than a month ago. The recent bullish sentiment appears to stem from a tightening supply, with the number of available vessels falling below 90. Meanwhile, daily loading volumes from the USG/USEC have recently eased, dropping to under 0.3 million tonnes.
|


| SECTION 2/ SUPPLY
Capesize Ballasters Overview (# Vessel Count) Mixed |

|
|
Capesize ballasters view: Capesize ballast availability in the Atlantic remained tight. In contrast, the Pacific continued to see elevated ballast vessel counts, particularly in Australasia. Meanwhile, ballaster activity in the Indian Ocean and South Africa began to ease, with a 6% week-on-week decline.
|
|
Panamax Ballasters Overview (# Vessel Count) Mixed |
 |
|
Panamax ballasters view: An oversupply emerged in the Atlantic, while ballast numbers in the Indian Ocean/South Africa and Australasia declined by 6% and 10% week-on-week, respectively.
|
|
Supramax Ballasters Overview Increasing |
 |
|
Supramax ballasters view: Oversupply appeared in both basins. In the Atlantic, ballast supply increased significantly by 20% in the North and 10% in the South. Meanwhile, the Pacific market saw significant increase, with the Indian Ocean/South Africa rising 25% and Australasia increasing 20% week-over-week.
|
|
Handysize Ballasters Overview Increasing |
 |
|
Handysize ballasters: Vessel oversupply has seen continuous and significant increases in both the Pacific and North Atlantic basins. Ballasters in the North Atlantic increased by 24% and in the Far East/NOPAC region by 17%.
|

|
Toward the end of Q2 this year, we began to observe a rise in Capesize tonne-day demand on the Brazil-to-China route, aligning closely with last year’s trend around the 37 million mark. This increase appears to be supported by stronger iron ore output from Vale, Brazil’s leading miner. |
|
|

Source: Signal Ocean



Related News.
European Shipowners call on MEPs to back Commission proposal to include two Indian yards in the EU ship recycling list
The Environment Committee of the European Parliament votes on 4 November on a motion for resolution objecting to the Commission’s proposal to add two…
Oversea signs commercial agreement with UECC following Successful Pilot
Following a successful pilot onboard Auto Advance, UECC has chosen to enter into a commercial agreement with Oversea. The pilot demonstrates how…
First NABEP Crude Cargo Under U.S. Agreement Arrives in Texas
Shipment of 1 million barrels arrived as NABEP production passes 223,000 barrels of oil equivalent per day. Two tankers carrying 1 million barrels of…
LNG carrier prices fall to $245 million, threatening Korean Shipbuilders’ Margins
Prices for high-value vessels, including liquefied natural gas carriers and ultra-large container ships, have begun to decline despite rising…
Vehicle Carrier Safety Forum publishes new Fire Drill Guidelines for vehicle carrying vessels
The Vehicle Carrier Safety Forum has published new Fire Drill Guidelines for Vehicle Carrying Vessels, providing vessel operators with a practical…
Is an Atlantic Basin crude glut on the cards?
Atlantic crude discounts fail to offset high freight to Asia, raising the risk of a regional glut as VLCC availability tightens. Freight…
The future of trade infrastructure in Europe is connectivity
One year after its inauguration, Rijeka Gateway offers a glimpse into the future of European trade. On 10 September last year,…
Allied – Weekly Market Review – Week 43
Please find below the Allied Weekly Report for Week 43 | 2026 ALLIED - Weekly Market Report- Week 43
Intermodal Report – Week 43 2026
Please find below the Intermodal market report for week 43 2026. Intermodal Report Week 43 2026
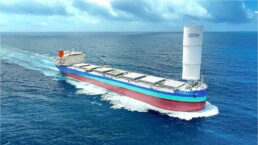
Wind Challenger-Equipped LNG Dual-Fueled Coal Carrier ‘MAIZURU KAZENOMAI’ Delivered
-While Supporting a Stable Energy Supply, Reducing Environmental Impact - Mitsui O.S.K. Lines announced the delivery and entry into service of an…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
