Dry Weekly Market Monitor – Week 09, 2025 by Signal Ocean

 |
|
Recent observations indicate that imported iron ore stocks at China’s major ports have seen a slight decrease, dropping by 529,900 tonnes, or 0.3% week-on-week, to a total of 153.4 million tonnes as of February 20. This reduction occurs even as both the incoming and discharged volumes of iron ore have risen in recent weeks, suggesting that while port operations are strong, there is a clear drawdown in overall stockpiles. This modest dip in port inventories appears to indicate that China’s immediate demand for iron ore imports is being met by its existing substantial stockpiles. The increase in throughput, combined with the fall in stocks, implies that current inventories are satisfying import needs without necessitating additional shipments. This situation points to a market where the dependency on stored inventory is rising, potentially lessening the demand for new shipment imports.Moreover, these dynamics hold significant implications for the Capesize freight market. With China effectively utilizing its reserves, the demand for new iron ore shipments decreases, creating a scenario where surplus shipping capacity may become apparent. This is reflected in an increase in ballaster activity, as vessels are increasingly repositioning due to lower immediate demand. Consequently, the equilibrium between supply and demand in the freight market shifts, likely exerting further downward pressure on freight rates. In summary, the interaction between steady throughput, the strategic use of port stockpiles, and rising ballaster numbers hint at a transitional phase in the market. If these trends persist, the Capesize segment may witness ongoing declines in freight prices, prompting shipping companies to reevaluate their capacity deployment and pricing strategies in a market where supply increasingly surpasses fresh demand. By the end of the month, ballasters in the South Atlantic recorded a modest 5% decrease from their previous highs, though levels remain significantly above the record lows observed at the start of the year. It remains uncertain whether the March trend will continue to decline, potentially boosting C3 freight rates.
For more information on this week’s freight, supply and demand shipping trends, see the analysis sections below. You can also log in to our Newsroom page under Insights & News to stay updated with the latest reports. |
SECTION 1/ FREIGHT – Freight Rates ($/t) Firmer‘The Big Picture’ – Capesize and Panamax Bulkers and Smaller Ship Sizes |
 |
|
The trend for Capesize rates from Brazil to North China strengthened before the end of the month, while signs of recovery in other vessel size categories have now been confirmed, gaining further momentum from the third week’s end.
|
| SECTION 2/ SUPPLY – Ballasters (# vessels) Decreasing Supply Trend Lines for Key Load Areas |
 |
|
|

The decline in tonne-days persisted in the Capesize segment, but signs of recovery are emerging, suggesting that levels may have bottomed out since mid-February.
|
|
|

Source: Signal Ocean



Related News.
ECB keeps rates on hold as Christine Lagarde announced her resignation
With still very little knock-on effects from higher energy prices and headline inflation on the rest of the economy, the ECB kept interest rates on…
ASA SC highlights geopolitical risks to seafarers while tackling workforce and regulatory challenges
The 33rd Interim Meeting of the Asian Shipowners’ Association (ASA) Seafarers Committee (SC) convened online on 16 October 2026, hosted by the China…
US awards $498m to 35 port projects across 19 states
The round uses the last US$450 million of the infrastructure law's port grant commitment. Alaska's Whittier receives US$50.6 million to replace the…
Maritime leaders push for stronger action on global shipping rules in Busan
World Maritime Day Parallel Event spotlights theme “From Policy into Practice: Powering Maritime Excellence”. International delegates meeting in…
Hapag-Lloyd strengthens its position in Italian ports
Italian export volumes of Hapag-Lloyd continue its upward trend, with a further relevant growth expected in 2026 compared with 2025, bringing…
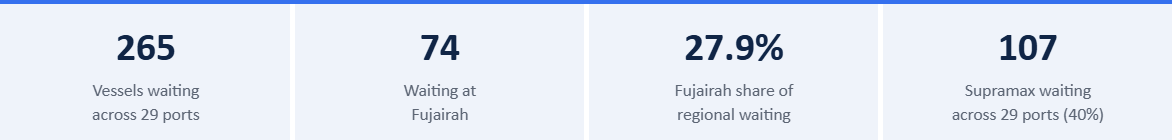 Fujairah…
DORIC MONTHLY CHINA BAROMETER OCTOBER 2026
Pls find below the DORIC MONTHLY - CHINA BAROMETER OCTOBER 2026 CHINA_BAROMETER_OCTOBER_2026
BIMCO Dry Bulk Shipping Market Overview & Outlook
Escalating attacks on ships heighten uncertainty "Geopolitical disruptions continue to cloud the dry bulk market outlook. The effective closure of…
Nor-Shipping aims to demystify ship recycling with new conference for 2027
With industry estimates suggesting more than 15,000 vessels will need to be recycled by 2032*, more than double the number recycled in the previous…
San Pedro Bay Ports outline path for Cleaner Marine Fuels
The ports of Long Beach and Los Angeles have released a comprehensive report identifying promising clean marine fuels for oceangoing vessels and…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
