Arabian Gulf dirty oil shipments to all destinations

 |
|
As August draws to a close, the earlier weakening momentum on the VLCC AG-China route appears to have stabilised to a firmer momentum. Despite this stabilisation, the weekly percentage growth in demand tonne days has not yet surpassed previous weeks, indicating that a strong recovery remains elusive. On the demand side, the persistently weak Chinese economic environment continues to pose significant challenges. China’s sluggish economic performance, marked by slow industrial output and a decline in new home prices, is dampening the demand for crude oil imports. This, in turn, affects the VLCC market, as China is one of the largest consumers of crude oil transported via this route. The ongoing uncertainty in China’s economic outlook adds to the difficulty of predicting a near-term rebound in VLCC demand. As refineries in China continue to operate at reduced capacity due to weak fuel demand, the pressure on the VLCC AG-China route is likely to persist. Market participants are closely monitoring economic indicators and potential policy responses from the Chinese government, which could influence oil demand in the coming weeks. However, without a significant improvement in China’s economic conditions, the VLCC market may struggle to regain strong upward momentum in the short run. Data from last week revealed that China’s economy lost significant momentum in July, marked by the sharpest decline in new home prices in nine years and a slowdown in industrial output. In response to weak domestic fuel demand, Chinese refineries have significantly reduced their crude processing rates. This downturn has raised concerns about the broader implications for the global oil market. Goldman Sachs analysts have projected that Brent crude prices could fall to $68 per barrel by late 2025 if China’s oil demand remains stagnant through the end of next year. The bank noted that “soft China oil demand and downside risks to China GDP growth strengthen our view that the risks to our $75-$90 Brent range in 2025 skew to the downside.” Goldman Sachs estimates that China’s year-on-year oil demand growth sharply slowed to 200,000 barrels per day in the first half of this year, with an expected year-on-year decline during the summer. For more information on this week’s freight supply and demand trends, see the analysis sections below. You can also log in to our Newsroom page under Insights & News to stay updated with the latest reports. |
 |
The dirty freight market sentiment appears to be stabilising before the end of August, as evidenced by a recent uptick in VLCC MEG-China rates. These rates have shown an increase compared to the lower levels observed at the beginning of the month, suggesting a potential shift towards a more robust market.
|
 |
 |
 |
 |
The supply trend for crude tankers shows a decline for Suezmax vessels in the West Africa-to-Continent route and Aframax vessels in the Mediterranean and Baltic regions. However, VLCCs from Ras Tanura have experienced an uptick in August, with supply levels close to surpassing the annual average by the end of the third week of the month.
|
 |
 |
 |
|
 |
|
Source: The Signal Group



Related News.
Global study finds Cyprus ranks SEVENTH and set for $1.1 billion AI GDP boost
Cyprus beats India and New Zealand to come SEVENTH in major AI study – with potential €1.1 billion GDP boost and youth jobs opportunity Some 86% of…
Global shipping’s trillion dollar climate bill according to Zero Carbon Analytics
A new study by Zero Carbon Analytics finds that emissions from international shipping cost the global economy around USD 963 billion between 1990…
Keeping Children Safe Online at Sea Seafy® earns friendly WiFi Certification across 26 vessels
Seafy becomes Friendly WiFi’s first partner in the maritime sector, helping protect kids from harmful content online. Friendly WiFi is delighted…
ShipManager joins Star Information Systems to accelerate the maritime industry’s transition to cloud
CFARER, a DNV Company selects Star Information Systems as the longterm home for ShipManager and its cloud future Star Information Systems (Star)…
Seafarer experience must shape maritime technology, initial STEER Project report finds
New research finds technology can shift rather than remove risk as The Nautical Institute, with support from Lloyd’s Register Foundation, calls for…
New LR service targets cargo disruption when trade routes fail
New LR Advisory service helps ports, governments and logistics operators respond to disruption, protect critical cargo flows and strengthen trade…
DORIC WEEKLY INSIGHT 06 NOVEMBER 2026
Please find below the DORIC Market Insight for the week ending 06th November 2026. Weekly Report 06.11.2026
BIMCO Shipping Number of the Week
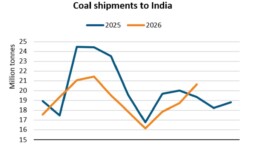
Coal shipments to India drop 7%, but limited recovery may lie ahead "Between January and October, coal shipments to India dropped 7% y/y due to the…
Hapag-Lloyd marks 20 years in South Africa and targets further growth
South Africa has become a cornerstone of Hapag-Lloyd's business in Africa Hapag-Lloyd surpasses 1 million TEU in Africa for the first time in its…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
