
trend indicated another decrease in the number of ballast vessels, but the recent firmness in the freight market has not yet matched the peak observed at the end of November 2023, when $/mt freight rates reached 30.In the third week of June, significant developments are observed in the Capesize vessel rates on the Brazil to North China route, as well as in the Panamax Cont FE routes, indicating a stronger momentum for larger vessel size segments as we approach the end of the month. Specifically, the Panamax P6 route in ECSA shows promising signs for the firming of freight rates in the coming days, supported by a notable decrease in the number of ballast vessels from their peaks in mid-February and before mid-March. Looking ahead, June appears poised to conclude with an upward trend in the growth of dry bulk demand tonne days. If this trend continues, it could lead to higher vessel employment utilisation in both the Atlantic and Pacific markets, setting the stage for a potentially robust July.
On the macro side, Chinese economic development continues to disappoint with its indicators for the future steel and iron ore demand needs. Iron ore futures prices declined on Monday following disappointing economic data from China, amidst ongoing challenges like floods and high temperatures affecting near-term demand prospects. The most actively traded September iron ore contract on China’s Dalian Commodity Exchange (DCE) closed daytime trading 1.63% lower at 813 yuan ($112.05) per metric ton. Meanwhile, the benchmark July iron ore contract on the Singapore Exchange, SZZFN4, fell 2.51% to $104.8 per ton as of 0710 GMT.
Market sentiment was notably impacted by weaker-than-expected data from China’s property sector, which is a major consumer of steel. Despite intensified efforts by policymakers to bolster the struggling sector and boost consumer confidence, property investment in China dropped by 10.1% in the first five months of 2024 compared to a year earlier, following a 9.8% decline in January-April, according to statistics bureau data. The combination of these factors contributed to a downturn in iron ore prices, reflecting market concerns over the economic outlook and demand conditions in China. The major iron ore producers listed on the ASX 200—BHP Group (ASX: BHP), Rio Tinto (ASX: RIO), and Fortescue Metals Group (ASX: FMG)—are currently navigating the repercussions of an economic deceleration in China.
SECTION 1/ FREIGHT – Market Rates ($/t) Firmer
‘The Big Picture’ – Capesize and Panamax Bulkers and Smaller Ship Sizes
In the third week of June, the Capesize Brazil to North China route showed signs of gaining strength, while Panamax Cont FE freight rates reversed course and began to climb. The sustainability of this momentum is yet uncertain, amid indications of declining ballast vessel numbers and an accelerated growth in tonne days expected by month-end.
Capesize vessel freight rates shipments from Brazil to North China are now at around $27 per ton, marking a 27% annual increase.
Panamax vessel freight rates from the Continent to the Far East rose above $ 40 per ton. Recent data indicate a 27% surge compared to the rates observed a year ago.
Supramax vessel freight rates on the Indo-ECI route held levels around $11 per ton over the last four weeks, marking a 36% increase compared to a comparable week from a year ago.
Handysize freight rates for the NOPAC Far East route have maintained stability, echoing the sentiment of the past five weeks, holding steady at around $35 per ton. This represents a significant 30% increase compared to rates observed a year ago.
SECTION 2/ SUPPLY – Ballasters (# vessels) Decreasing
Supply Trend Lines for Key Load Areas
In the third week of June, there was a continued decrease in the number of ballast ships across all vessel size segments, except for indications of an increase in the Supramax segment in Southeast Asia.
Capesize SE Africa: The number of ballast ships has dropped to nearly the annual average of 107, marking a decrease of approximately 40 from the peak observed nearly four weeks ago.
Panamax SE Africa: The number of ballast ships has fallen below the annual average to 125, approximately 10 vessels fewer than the annual average and about 55 vessels lower than the peak observed in week 20.
Supramax SE Asia: The count of ballast ships has risen to above 110, signaling the first signs of an immediate increase before the end of the month compared to the low recorded in week 23.
Handysize NOPAC: Since the end of week 17, the count of ballast ships has consistently remained below the annual average of 80, with the past two weeks seeing levels decrease to around 70.
SECTION 3/ DEMAND – Tonne Days Increasing
Summary of Dry Bulk Demand, per Ship Size
In the third week of June, the outlook for dry tonne days began to show signs of an upward trend, building on the momentum observed at the end of the first half of the year.
Capesize: The latest estimates in tonne day growth spark optimism for the end of June, marking the first upward trend after consecutive weekly decreases since the last peak observed at the end of week 13.
Panamax: Last week’s indications of a reversal in the decline of tonne-day growth have been strongly confirmed at the start of the third week of June. The upward trend over the past two weeks has not only persisted but has also surpassed the low point observed in week 20.
Supramax: The growth rate has begun to show the first signs of an upward trend, improving from the low point observed at the end of week 21.
Handysize: The upward trend is also evident in the handysize vessel segment, which has seen a growth rate recording a higher weekly percentage increase compared to the supramax segment.
SECTION 4/ PORT CONGESTION – No of Vessels Increasing
Dry bulk ships congested at Chinese ports
The upward trend observed in the first half of June has continued into the start of the third week, as Chinese dry bulk congestion continues to rise significantly across all vessel size segments.
Capesize: Capesize ship congestion increased to 120, marking a rise of nearly 10 compared to the levels observed the previous week.
Panamax: The number of Panamax vessels continued to increase, surpassing 260 and approaching 270, which is almost 20 more than the previous week.
Supramax: Congestion levels showed signs of surpassing the 260 mark in the last week, ultimately settling just below 260, with a tendency to increase further in the coming days of June.
Handysize: Congestion levels maintained a similar upward trend from the previous week, reaching around 180, which marks an increase of 10 compared to the previous week.
Source: By Maria Bertzeletou, Signal Group



Related News.
Global study finds Cyprus ranks SEVENTH and set for $1.1 billion AI GDP boost
Cyprus beats India and New Zealand to come SEVENTH in major AI study – with potential €1.1 billion GDP boost and youth jobs opportunity Some 86% of…
Global shipping’s trillion dollar climate bill according to Zero Carbon Analytics
A new study by Zero Carbon Analytics finds that emissions from international shipping cost the global economy around USD 963 billion between 1990…
Keeping Children Safe Online at Sea Seafy® earns friendly WiFi Certification across 26 vessels
Seafy becomes Friendly WiFi’s first partner in the maritime sector, helping protect kids from harmful content online. Friendly WiFi is delighted…
ShipManager joins Star Information Systems to accelerate the maritime industry’s transition to cloud
CFARER, a DNV Company selects Star Information Systems as the longterm home for ShipManager and its cloud future Star Information Systems (Star)…
Seafarer experience must shape maritime technology, initial STEER Project report finds
New research finds technology can shift rather than remove risk as The Nautical Institute, with support from Lloyd’s Register Foundation, calls for…
New LR service targets cargo disruption when trade routes fail
New LR Advisory service helps ports, governments and logistics operators respond to disruption, protect critical cargo flows and strengthen trade…
DORIC WEEKLY INSIGHT 06 NOVEMBER 2026
Please find below the DORIC Market Insight for the week ending 06th November 2026. Weekly Report 06.11.2026
BIMCO Shipping Number of the Week
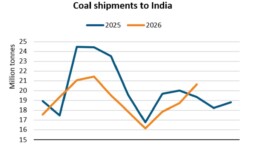
Coal shipments to India drop 7%, but limited recovery may lie ahead "Between January and October, coal shipments to India dropped 7% y/y due to the…
Hapag-Lloyd marks 20 years in South Africa and targets further growth
South Africa has become a cornerstone of Hapag-Lloyd's business in Africa Hapag-Lloyd surpasses 1 million TEU in Africa for the first time in its…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
