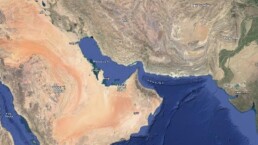

In 2023, Qatar exported about 81 million tonnes of LNG and the UAE exported 4 million tonnes, contributing 21% to the global supply. Any supply blockage will not only hurt exporters of these two countries but will also compel key importers to scout for new sources. Between Asia and Europe, the former will have a much greater impact as 70% of Qatar’s volumes are exported to Asia while 20% to Europe.
Some countries, such as India and China, will be at high risk as these countries source about 45% and 25% of their total LNG imports from Qatar every year, respectively (based on the 2023 trade statistics).
Meanwhile, European importers including, the UK, Italy and Belgium, will also need to source LNG from other countries, if supply from Qatar becomes impassable.
We believe that a complete closure of the Strait of Hormuz is highly unlikely as Iran exports all of its oil and LPG cargoes through it and other Middle Eastern countries traversing via SoH will have severe repercussions if it is blocked. Meanwhile, the global economy will be hit by a massive supply deficit of natural resources as 30% of oil, 20% of LNG and 40% of LPG will be affected by the potential closure. However, this will have short-term repercussions on LNG.
Iran-Israel conflict: Impact on LNG market and shipping
LNG prices spike: Asian Spot and TTF* were up 14% and 15% WoW, respectively, on 20 April 2024 amid the escalated tensions in the Middle East. Prices are now more than $10 per MMBtu, after hovering below this level for the last three months. We expect LNG prices to be volatile in tandem with prolonged conflict in the Middle East, threatening supply cuts, which will keep LNG players on the edge.
We also expect Asian spot to maintain its premium over TTF as any supply cut from the Middle East will impact Asian buyers more than European ones. However, the growth in LNG prices will be moderate due to high storage and stable gas demand in Europe.
The extent of supply shortage will depend on the duration of SoH closure: According to Drewry AIS, Qatar exports about 0.2 million tonnes of LNG per day, while the UAE exports nearly 10 thousand tonnes per day. We believe the impact of any supply disruption from these countries will be directly proportional to the duration of the closure. If Iran blocks SoH for a few days or weeks, we expect no major impact on the LNG market and shipping as currently, demand remains stable in Europe and Asia.
However, the situation could deteriorate if the closure extends to several weeks or months, stalling about 5-6 million tonnes of supply per month from Qatar and the UAE. In terms of LNGC loadings, about 16-17 LNGCs will be idled if supply is halted for a week, while 60-70 LNGC loadings will be affected in a month.
LNG shipping could reap benefits in the benefits of short/partial closure of the SoH: So far, LNGC spot rates have not shown any reaction to the escalated situation. Rates have continued to slide since the beginning of this month due to tepid demand, mild weather and ample inventories.
We believe the partial closure of the SoH could support LNG shipping amid vessels diverting away from the Middle East in search of new employment as importers will seek substituted cargoes from other destinations, leading to some shifts in current trade patterns. Although the shift in trade will be sustainable for a short period (assuming up to five months), we expect an increased US-Asia trade, providing impetus to LNG shipping rates – mainly due to huge vessel absorption as US shipments will continue to take the COGH instead of the Panama and Suez Canals, generating extra tonne-mile demand.
Thus, short-term supply disruption will lead to demand alternation, supporting LNG shipping and aiding LNG prices.
However, we are pessimistic about LNG shipping if the complete closure of the SoH extends for a longer period (assuming one year). Any supply shortage for a long duration will harm LNG shipping, further tightening the market. On the other hand, fleet availability will grow with several vessels being idled due to LNG supply shortage while about 60 new LNGCs are expected to join the current fleet this year. Consequently, this will lead to vessel oversupply, which inevitably will dent the LNG shipping rates.
Source: Drewry



Related News.
RINA’s Hellenic Technical Committee puts energy-efficient newbuilding design and AI in focus
Project Mermaid, battery integration and practical AI applications highlight opportunities for more efficient ship design and fleet operations…
From mine to market – NORDEN connects Comilog’s manganese ore with global markets
NORDEN’s dedicated transhipment operation in Gabon, run under a long term contract with long-standing customer Comilog, has loaded more than 54…
Oldendorff reflags two capesize vessels to Germany
Oldendorff Carriers is reflagging two of its Capesize bulk carriers to Germany, underlining the company’s long standing ties to the country and its…
AskChief surpasses 100-vessel milestone in under a year and opens its specialised maritime AI to the wider market
Putting each company’s own knowledge to work for maritime Technical and HSQE teams. AskChief, Specialised AI for maritime Technical and HSQE…
Dalian Maritime University’s Yu Jiajia receive 2027 IMO Gender Equality Award
From the bridge to the classroom, Ms Yu has helped build a more inclusive maritime sector in China, serving as a role model for the global maritime…
“K” LINE releases video update on forecasts for FY2026 and progress of the medium-term management plan
Kawasaki Kisen Kaisha, has released a video on its official website explaining its forecasts for FY2026 and progress of its Medium-Term Management…
 …
MOL and MOL CAREER sign 3-way deal with Nagasaki Prefecture to promote recruitment and retention of foreign workers
Mitsui O.S.K. Lines, and MOL CAREER, have entered into a tripartite partnership agreement with Nagasaki Prefecture to promote the revitalization of…
Hapag-Lloyd completes acquisition of 25% stake in APM Terminals Maasvlakte II
Transaction successfully completed following antitrust approval Investment strengthens Hapag-Lloyd’s terminal portfolio and position in Rotterdam…
11th chainPORT annual meeting at Tanger Med Focuses on scaling AI in ports
Representatives from leading ports around the world gathered in Tangier, Morocco, on 29 and 30 October for the 11th chainPORT Annual Meeting, hosted…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
