Geopolitical conflict threatens yet another shipping choke point
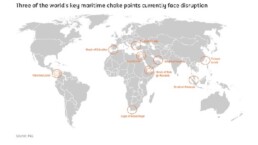

It’s a stark fact: more than 80% of global goods trade is transported by sea. And any disruption in maritime trade can have a profound impact on the worldwide economy. The latest potential flashpoint is the Strait of Hormuz. It’s a vital artery that carries around a fifth of the world’s oil. It’s been at the centre of numerous geopolitical tensions for many years. Any disruption could have yet another negative economic impact on the global economy, hampering vital trade routes and lengthening transit times, resulting in production delays and higher inflation.
But the Strait is not the only place where there’s deep concern about security.
For some time now, the Strait of Bab el-Mandeb-Suez Canal, which handles around 15% of global maritime trade, has seen significant disruption due to attacks by Houthi rebels on ships in the region. The Red Sea is still largely being avoided, with daily transits down two-thirds year-on-year, according to IMF PortWatch data. On the other side of the globe, a drought at the Panama Canal, which handles 5% of global maritime trade, is slowly improving as daily transits have risen to 27 in March from 24 in January and 22 in December 2023. Yet, capacity is still off the normal daily average of 34-40 transits, a level currently only expected to be reached again by 2025. And next to this, shallow waters in the world’s main inland shipping waterways could easily return over the course of this year.
Due to the mounting tension in the Middle East, those risk-laden waters have spread from the Red Sea to the Gulf of Aden, and the vital Strait of Hormuz could be caught up in it too. It was only days ago that Iranian forces seized the MSC Aires container vessel. We know from all the disruption in the Red Sea that elevated risks could quickly impact trade routes once seafarers and cargo are threatened and insurance risk premiums go up. As such, trade has become increasingly politicised. It’s worth noting here that another maritime area in the scope of geopolitical risks is the Taiwan Strait, which is a gateway to large Chinese ports.
When it comes to international trade, it’s difficult to quantify the financial effect of one or two events, whether they’re geopolitically related or not. That said, you may recall the blockage of the Suez Canal by a container ship, Ever Given, in 2021. That led to an estimated loss of 0.2 to 0.4 percentage points in global trade. Low water levels in the Rhine in Germany had a negative impact of 0.3% on GDP numbers due to higher transport and trade costs and production delays.
The Strait of Hormuz is a key route for global oil and LNG transport
Here’s why the Strait of Hormuz, that key maritime choke point connecting the Persian Gulf with the Gulf of Oman, is in trade watchers’ focus. The Strait is critical for transporting oil, petroleum products and LNG. Saudi Arabia, Iraq, UAE, Kuwait, Iran and Qatar produced 22.8 million barrels of oil a day, and some 20 million were transported daily via this route. That equates to 20% of global crude and refined product consumption.
If Iran were to attempt to disrupt or block oil flows through the Strait of Hormuz, the country itself wouldn’t be the only one which would suffer. Iraq, Qatar and Kuwait would be severely disrupted as these countries usually transport 100% of their crude oil exports through the Strait of Hormuz. Unlike the Red Sea, there’s no real alternative for shipments through this channel. To some extent, the East-West crude pipeline (Abqaiq-Yanbu) across the Arabian Peninsula and the Abu Dhabi Crude Oil pipeline are alternatives for Saudi Arabia and the United Arab Emirates. The former, however, leads into the already circumvented Red Sea.
In addition, a significant amount of LNG passes through the Strait of Hormuz. Qatar, the third largest LNG exporter in 2023, shipped 108bcm of Liquefied Natural Gas through the choke point, which is around 20% of total global LNG trade. Given that Qatar is set to boost capacity to more than 170bcm by 2027, the Strait will become even more important for LNG flows. Clearly, with Europe increasingly more reliant on LNG since the Russia/Ukraine war, any disruptions to the LNG market will be felt more in Europe.
Tensions have already been reflected in somewhat higher oil prices, with a large risk premium already priced in before last weekend. This could easily lead to supply concerns should the situation escalate. According to LSEG Oil Research, most of the crude and condensates shipped through the Strait of Hormuz went to Asian markets, putting those economies more at risk of a potential supply cut. However, given the global nature of the oil market, all regions would be affected by higher oil prices in the event of a blockade.
For the tanker shipping market, this means yet another headache it could do without after sanctions on Russia already led to significant shifts in oil trade patterns and much more sea mileage. These new tensions will keep tanker rates elevated and may even send them higher still.

For the time being, oil supply remains intact, although the risk of tensions in the Middle East making things much worse is growing. The lack of any significant price reaction following Iran’s recent attack on Israel is largely due to a large risk premium already having been priced into the market. ICE Brent rallied from a little more than $86/bbl at the start of April to over $90/bbl in anticipation that Iran would respond to Israel’s suspected airstrike on its embassy in Syria.
Secondly, the market is also in limbo, still waiting to see how Israel will respond to the aggression. The longer the market waits, the more likely the risk premium starts to fade. Risks to oil supply are at their highest since October last year. Any further escalation would only bring the oil market closer to actual supply losses. We believe there are three key supply risks facing the oil market as a result of current tensions, which we discuss in this article.
On the demand side, ongoing economic headwinds might also offset supply restrictions to some extent, with the Chinese and eurozone economic growth path improving but remaining subdued overall. With plenty of risk facing the market, we will not be the only ones closely monitoring the tensions in the Middle East and those crucial maritime choke points.
Source: ING



Related News.
RINA’s Hellenic Technical Committee puts energy-efficient newbuilding design and AI in focus
Project Mermaid, battery integration and practical AI applications highlight opportunities for more efficient ship design and fleet operations…
From mine to market – NORDEN connects Comilog’s manganese ore with global markets
NORDEN’s dedicated transhipment operation in Gabon, run under a long term contract with long-standing customer Comilog, has loaded more than 54…
Oldendorff reflags two capesize vessels to Germany
Oldendorff Carriers is reflagging two of its Capesize bulk carriers to Germany, underlining the company’s long standing ties to the country and its…
AskChief surpasses 100-vessel milestone in under a year and opens its specialised maritime AI to the wider market
Putting each company’s own knowledge to work for maritime Technical and HSQE teams. AskChief, Specialised AI for maritime Technical and HSQE…
Dalian Maritime University’s Yu Jiajia receive 2027 IMO Gender Equality Award
From the bridge to the classroom, Ms Yu has helped build a more inclusive maritime sector in China, serving as a role model for the global maritime…
“K” LINE releases video update on forecasts for FY2026 and progress of the medium-term management plan
Kawasaki Kisen Kaisha, has released a video on its official website explaining its forecasts for FY2026 and progress of its Medium-Term Management…
 …
MOL and MOL CAREER sign 3-way deal with Nagasaki Prefecture to promote recruitment and retention of foreign workers
Mitsui O.S.K. Lines, and MOL CAREER, have entered into a tripartite partnership agreement with Nagasaki Prefecture to promote the revitalization of…
Hapag-Lloyd completes acquisition of 25% stake in APM Terminals Maasvlakte II
Transaction successfully completed following antitrust approval Investment strengthens Hapag-Lloyd’s terminal portfolio and position in Rotterdam…
11th chainPORT annual meeting at Tanger Med Focuses on scaling AI in ports
Representatives from leading ports around the world gathered in Tangier, Morocco, on 29 and 30 October for the 11th chainPORT Annual Meeting, hosted…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
