With hundreds of Australian wells stopping production soon, a multi-billion P&A market emerges
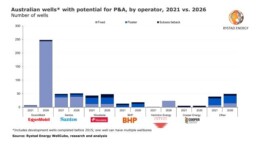

Australia is about to see its largest-ever wave of offshore development wells that reach the end of their producing life and need to be for decommissioned. This task is both adding headaches for producers and creating a multibillion-dollar opportunity for plugging and abandonment (P&A) suppliers. A Rystad Energy report shows that Australia’s number of such wells will jump from 160 today to more than 440 by 2026, with a further 172 offshore exploration wells waiting in the queue.
The Australian decommissioning market may exceed a total of $40 billion due to the country’s sizeable offshore P&A liabilities and its non-producing onshore assets. The figure could even double, depending on how many decommissioning projects materialize.
“Recent developments have made it more difficult for operators to sidestep decommissioning obligations by selling ageing assets, as the market appetite for such assets is drying up. Many producers will have to deal with the issue in coming years, with ExxonMobil having the lion’s share of liabilities in Australia,” says Jimmy Zeng, senior analyst at Rystad Energy’s upstream team.
Rystad Energy’s analysis of the P&A potential takes into account the production status of each operator’s offshore wells, the likelihood of producing fields ceasing output in the coming five years, wells that have been already suspended but not yet abandoned, along with partially abandoned wells. While development wells make up the bulk of the total, exploration wells are also in need of P&A to a lesser extent even though we do not expect strong exploration growth in Australia in coming years.
Turning our attention to development wells, we estimate 890 offshore wells in total were drilled in Australia before 2015, of which 108 have been permanently abandoned. Of the 782 wells not yet abandoned, we have identified a group of wells that we consider good candidates for P&A activity in the years ahead. We define a well as a collection of one or more wellbores with the same top-hole location.
Filtering out wells that are more likely to be identified for upcoming P&A, we end up with 440 wells that are P&A candidates, the majority of which are in the Gippsland Basin.
The dominance of the Gippsland basin is to be expected given the legacy of offshore development in the region, driven by ExxonMobil and BHP’s Gippsland Basin Joint Venture (GBJV). The area has been a key source of domestic gas supplies going back to 1964, and output is expected to go into long-term decline over the next decade.
Within the Gippsland group, most wells are located on fixed platform facilities, while in other basins the distribution of facility types is more mixed. New resource developments in the Gippsland Basin are becoming more capital intensive, but the outlook for P&A opportunities in the area should prove attractive to service suppliers.
In the North Carnarvon Basin group, we see an age distribution that shows non-producing wells are relatively “younger” than those in the Gippsland, with the majority being no more than 20 years old. Even so, various measures intended to ensure operators fully decommission facilities and wells are likely to provide a tailwind for service suppliers seeking P&A mandates in the North Carnarvon basin as well – spurred by the industry controversy over Northern Oil & Gas’s inability to fund its decommissioning of the Northern Endeavour FPSO and associated wells.
Given its large legacy position in the Gippsland, it is no surprise that ExxonMobil leads the way in its decommissioning liabilities, with a rapid increase in the number of wells likely to cease production over the next five years. While this is indubitably a high-cost endeavor, we note that most of these wells are platform-based, where per-well abandonment costs are likely to be significantly lower than for subsea wells. Furthermore, regulatory pressure on ExxonMobil to decommission these wells has increased significantly lately.
Outside of ExxonMobil’s high well burden, operators Santos, Woodside, BHP and Vermillion Energy will also experience growing decommissioning obligations in the next five years, measured by the increase in wells within our “potential for P&A” grouping. Woodside and BHP have mostly subsea wells in this category, which could mean their decommissioning bills will be higher on a per-well basis. Woodside recently communicated its intention of starting abandonment of up to 18 subsea wells on the Enfield field from 2022 to 2024.
More insights from Jimmy Zeng on Australia and its future as one of the world’s top LNG suppliers will be available during our “Our Business – Progress or Pivot?”session on 16 June at 11:15am AWST at APPEA 2021. Meet us at booth #228 to learn more.
For more analysis, insights and reports, clients and non-clients can apply for access to Rystad Energy’s Free Solutions and get a taste of our data and analytics universe.
Source: Rystad Energy



Related News.
Global study finds Cyprus ranks SEVENTH and set for $1.1 billion AI GDP boost
Cyprus beats India and New Zealand to come SEVENTH in major AI study – with potential €1.1 billion GDP boost and youth jobs opportunity Some 86% of…
Global shipping’s trillion dollar climate bill according to Zero Carbon Analytics
A new study by Zero Carbon Analytics finds that emissions from international shipping cost the global economy around USD 963 billion between 1990…
Keeping Children Safe Online at Sea Seafy® earns friendly WiFi Certification across 26 vessels
Seafy becomes Friendly WiFi’s first partner in the maritime sector, helping protect kids from harmful content online. Friendly WiFi is delighted…
ShipManager joins Star Information Systems to accelerate the maritime industry’s transition to cloud
CFARER, a DNV Company selects Star Information Systems as the longterm home for ShipManager and its cloud future Star Information Systems (Star)…
Seafarer experience must shape maritime technology, initial STEER Project report finds
New research finds technology can shift rather than remove risk as The Nautical Institute, with support from Lloyd’s Register Foundation, calls for…
New LR service targets cargo disruption when trade routes fail
New LR Advisory service helps ports, governments and logistics operators respond to disruption, protect critical cargo flows and strengthen trade…
DORIC WEEKLY INSIGHT 06 NOVEMBER 2026
Please find below the DORIC Market Insight for the week ending 06th November 2026. Weekly Report 06.11.2026
BIMCO Shipping Number of the Week
Coal shipments to India drop 7%, but limited recovery may lie ahead "Between January and October, coal shipments to India dropped 7% y/y due to the…
Hapag-Lloyd marks 20 years in South Africa and targets further growth
South Africa has become a cornerstone of Hapag-Lloyd's business in Africa Hapag-Lloyd surpasses 1 million TEU in Africa for the first time in its…
Subscribe to our newsletter!
if you dont want to swim alone in the ocean of news, sign up for the newsletter, and you will receive daily all the important news of world shipping!
